
- Market Size (2026)
- USD 3.8 Bn
- Forecast (2036)
- USD 6.5 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Baby Bottle Market in 2026?
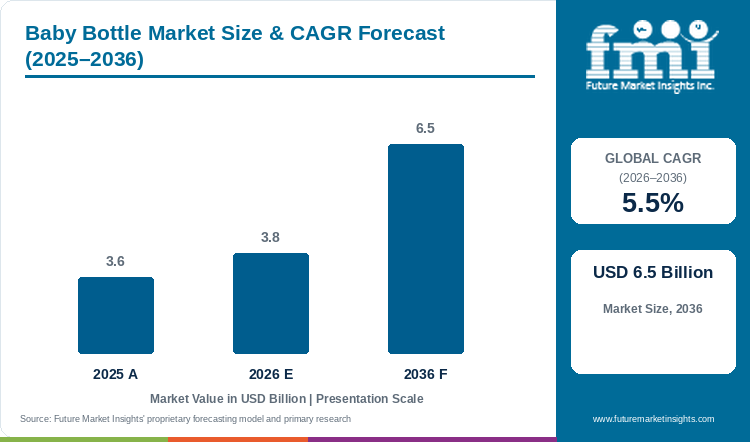
The baby bottle market valuation was valued at USD 3.6 billion in 2025 to USD 3.8 billion in 2026 and is estimated to reach USD 6.5 billion by 2036, expanding at a 5.5% CAGR during the forecast period.
The global baby bottle market was valued at USD 3.6 billion in 2025 and is estimated to reach USD 3.8 billion in 2026. Industry valuation is projected to reach USD 6.5 billion by 2036, expanding at a compound annual growth rate (CAGR) of 5.5% between 2026 and 2036. Polypropylene and polyphenylsulfone PPSU plastic vessels hold an estimated 58.0% share of 2026 demand, given that parents and maternity wards prioritize shatterproof bottles that tolerate daily boiling and steam sanitization. FMI demand analysis indicates that market growth is governed by multi-stage repurchase cadence rather than raw birth counts alone, since households buy three-bottle newborn kits at discharge and replace silicone teats every eight weeks as infant suction strength matures.
This baseline purchase pool is anchored by demographic records from the U.S. Centers for Disease Control and Prevention, which recorded 3,612,012 registered live births and a 76.3% first-trimester prenatal care initiation rate across the United States in 2025 [1]. Replacement-cycle economics also link the category closely to infant feeding accessories demand, as dual-income parents combine expressed breastmilk pumping with paced bottle feeding. Manufacturers are investing in medical-grade polymer upgrades and latch research to capture this trade-up, evidenced when Pigeon Corporation unveiled its 9th Medium-Term Management Plan in February 2026 to expand global nursing bottle sales across Western and Asian markets [2]. Brands that pair zero-leaching high-heat substrates with clinically validated anti-colic valves retain household loyalty across all three infant feeding stages through 2036.
Key Market Trends & Insights
- By bottle material: Polypropylene and Polyphenylsulfone PPSU Plastic holds an estimated 58.0% share in 2026 since amber-tinted PPSU and clarified PP resist impact drops and high-heat autoclaving.
- By nipple teat type: Silicone Orthodontic Anti-Colic Nipples represent 68.0% in 2026 owing to odorless medical-grade silicone elastomer resilience and built-in air-venting valves.
- By bottle capacity: Small Infant Bottles Below 150ml account for 52.0% in 2026 given that colostrum collection, preterm care, and newborn 60ml-to-120ml feeds require compact graduated vessels.
- By sales channel: Specialty Maternity and Baby Stores secure 44.0% in 2026 through curated prenatal registry consultations and tactile comparison of anti-colic vent assemblies.
- By neck configuration: Wide-Neck Ergonomic Bottles command 61.0% in 2026 supported by broad breast-shaped nipple bases that facilitate seamless breast-to-bottle switching.
Regional Highlights
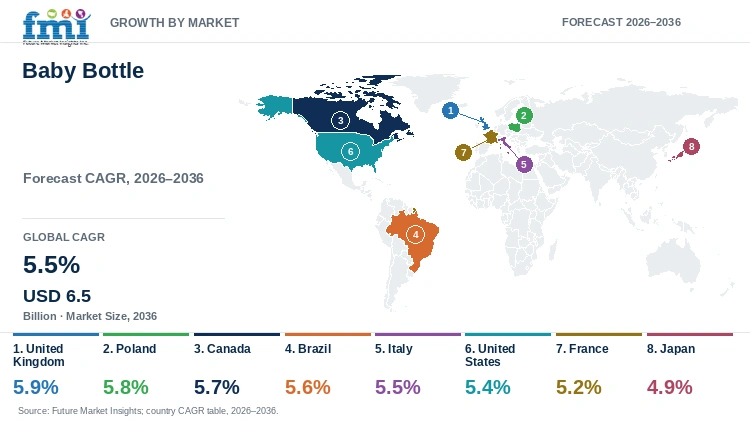
- Top national expansion: The United Kingdom leads national growth projections at a 5.9% CAGR through 2036 under rising combination-feeding adoption and premium PPSU and glass starter bundle sales.
- Broader country progression: Poland tracks at a 5.8% CAGR ahead of Canada at 5.7% and Brazil at 5.6%. Italy advances at 5.5% and the United States at 5.4%, followed by France at 5.2% and Japan at 4.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Baby Bottle Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.6 billion |
| Estimated Market Size in 2026 | USD 3.8 billion |
| Projected Market Size by 2036 | USD 6.5 billion |
| CAGR, 2026 to 2036 | 5.5% |
| Added Revenue, 2026 to 2036 | USD 2.7 billion |
Parental scrutiny over thermal polymer degradation during formula preparation is reshaping material selection across global nursery brands. When caregivers reconstitute powdered infant formula at 70 degrees Celsius or run electric steam sterilizers, standard homopolymer polypropylene experiences surface oxidation that releases microscopic particles into the feed. A December 2025 scoping review published in PubMed Central documented that infant feeding equipment and silicone-rubber teats subjected to repeated steam sterilization represent a primary early-life microplastic exposure pathway, producing 8 to 14 microparticles per day during routine milk preparation [3]. Consequently, maternity retail buyers and hospital procurement teams are shifting starter-kit assortments toward high-temperature polyphenylsulfone and borosilicate glass vessels paired with breastfeeding accessories.
Unit Shipment and Teat Replacement Sizing
Table 2: Unit Shipment and Teat Replacement Sizing for the Baby Bottle Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 3.6 | 3.8 | 6.5 |
| Global retail baby bottle shipments (million units) | 485.0 to 510.0 | 505.0 to 532.0 | 760.0 to 805.0 |
| Replacement silicone nipple volume (million units) | 720.0 to 765.0 | 755.0 to 802.0 | 1,180.0 to 1,245.0 |
| Average starter kit expenditure per infant (USD) | 44.0 to 52.0 | 46.5 to 55.0 | 68.0 to 79.0 |
Beyond initial vessel purchases, recurring sales in the infant feeding category depend on how effectively bottle substrates prevent particle migration while preserving breastmilk nutrients. In October 2025, biomedical investigators reporting in Molecular Cancer via PubMed Central documented that average daily infant consumption from plastic feeding bottles reached 1,580,000 microplastic particles during routine formula preparation [4]. This empirical finding explains why unit revenue in Table 2 expands faster than physical bottle shipments, as parents trade up from USD 5 commodity plastic tubes to USD 18 polyphenylsulfone and thermal-shock borosilicate bottles used with packaged infant milk.
Birth Cohort & Material Mix Indicators
Table 3: Birth Cohort and Material Mix Indicators for the Baby Bottle Market (births and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| U.S. registered live births baseline (million, CDC NCHS) | 3.61 | 3.63 | 3.78 |
| England and Wales live births baseline (thousand, ONS) | 585.4 | 588.0 | 605.0 |
| PPSU & borosilicate glass premium share (%) | 34.0% to 37.5% | 36.5% to 40.0% | 51.0% to 55.5% |
| Anti-colic internal-vent bottle penetration (%) | 64.0% to 67.0% | 66.5% to 69.5% | 78.0% to 82.0% |
Table 4: Neonatal Cohort & Channel Spending Indicators for the Baby Bottle Market (USD and institutional baselines), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 3.8 billion | 2026 global baby bottle valuation baseline |
| U.S. preterm birth share, 2025 | 10.41% of live births | CDC NCHS Data Brief No. 571 neonatal feeding cohort |
| Pigeon collected nursing bottles | 51,762 bottles | Pigeon Corporation December 2025 recycling registry across 141 sites |
| Specialty maternity & baby store revenue, 2026 | USD 1.67 billion | 44.0% specialty retail sales channel allocation |
Regulatory prohibitions on endocrine-disrupting monomers in infant feeding hardware continue to reinforce demand for trace-contaminant-free vessels and graduated hospital bottles. Federal food-additive regulations enforced by the U.S. Food and Drug Administration prohibit the use of bisphenol-A-based polycarbonate resins in baby bottles and sippy cups across commercial food-contact applications [5]. As North American and European authorities scrutinize polymer extractables across the feeding chain, parents purchasing commercial baby food actively verify that nursing bottles and silicone teats carry certified bisphenol-free compliance.
Analyst Perspective
"Parents no longer buy baby bottles as interchangeable plastic containers; they buy peace of mind against colic reflux, nipple confusion, and high-heat microplastic shedding. Brands that anchor their portfolios in medical-grade PPSU, borosilicate glass, and hospital-validated slow-flow silicone teats will capture outsized value growth even in low-fertility economies."
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Baby Bottle Market segmented?
The baby bottle market is segmented by bottle material, nipple teat type, bottle capacity, sales channel, and neck configuration. In 2026, Polypropylene and Polyphenylsulfone PPSU Plastic is projected at 58.0%, Silicone Orthodontic Anti-Colic Nipples at 68.0%, Small Infant Bottles Below 150ml at 52.0%, Specialty Maternity and Baby Stores at 44.0%, and Wide-Neck Ergonomic Bottles at 61.0%.
By bottle material: Polypropylene and Polyphenylsulfone PPSU Plastic, Borosilicate Tempered Glass, Food-Grade Liquid Silicone, and Stainless Steel Insulated.
By nipple teat type: Silicone Orthodontic Anti-Colic Nipples, Natural Rubber Latex Nipples, Variable Flow Controlled Teats, and Specialty Cleft and Preterm Teats.
By bottle capacity: Small Infant Bottles Below 150ml, Standard Bottles 150ml to 250ml, Toddler Large Bottles Above 250ml, and Ultra-Compact Colostrum Collectors.
By sales channel: Specialty Maternity and Baby Stores, Pharmacies and Drugstores, Supermarkets and Hypermarkets, and Online E-Commerce Portals.
By neck configuration: Wide-Neck Ergonomic Bottles, Standard Narrow-Neck Bottles, Angled Anti-Reflux Neck Bottles, and Disposable Liner Holder Shells.
Why does Polypropylene and Polyphenylsulfone PPSU Plastic lead the bottle material category?
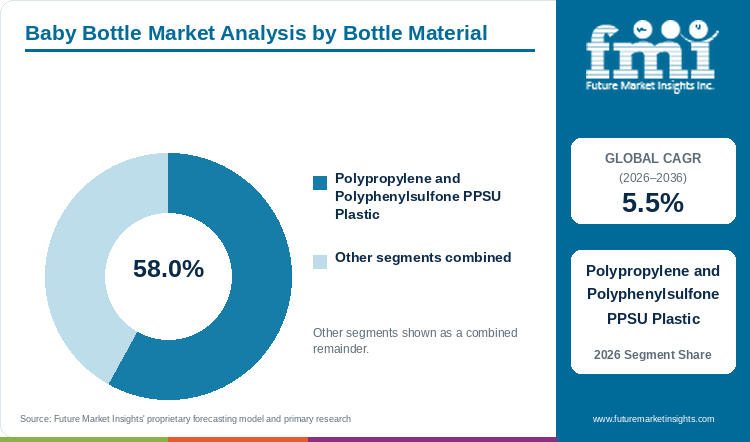
Polypropylene and Polyphenylsulfone PPSU Plastic holds an estimated 58.0% of bottle material demand in 2026, supported by shatter resistance and steam-sterilization durability.
Table 5: Bottle Material Share for the Baby Bottle Market (percentage share), 2026
| Bottle Material | Share (2026) |
|---|---|
| Polypropylene and Polyphenylsulfone PPSU Plastic | 58.0% |
| Other Segments Combined | 42.0%* |
| Total | 100.0% |
Table 6: Bottle Material Leadership and Market Growth for the Baby Bottle Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Segment | Polypropylene and Polyphenylsulfone PPSU Plastic |
Medical-grade polyphenylsulfone and clarified polypropylene anchor the bottle material category because they combine lightweight shatter resistance with high thermal deflection stability. While standard polypropylene serves price-sensitive mass retail channels, amber-colored PPSU withstands continuous steam sterilization up to 180 degrees Celsius without absorbing milk odors or warping. Caregivers transitioning infants toward prepared infant meals still face practical hurdles with standard polypropylene, as abrasive bottle brushes create micro-scratches that require vessel replacement every three to four months.
- Within the bottle material segment, Polypropylene and Polyphenylsulfone PPSU Plastic is projected to account for a leading 58.0% share in 2026, driven by unbreakable daycare compliance and rapid trade-up toward high-heat PPSU resins.
- A May 2026 systematic review in MDPI Nanomaterials reported that children face a 3.3-fold higher dietary microplastic intake per kilogram of body weight than adults as heated plastic infant feeding bottles release millions of particles per use, prompting brands to scale PPSU and cyclic olefin copolymer grades [6].
What sustains Silicone Orthodontic Anti-Colic Nipples leadership in the nipple teat type segment?
Silicone Orthodontic Anti-Colic Nipples represent an estimated 68.0% of the nipple teat type category in 2026, anchored by medical-grade peristaltic flexibility and zero latex allergen risk.
Liquid silicone rubber injection-molded into orthodontic anti-colic teats dominates caregiver preference because the material resists tearing, retains exact orifice geometry across hundreds of boiling cycles, and eliminates natural rubber latex protein allergies. Internal vent tubes and collapsible skirt valves integrated into the nipple base equalize air pressure inside the bottle, preventing vacuum formation that causes infants to swallow air and suffer post-feed colic. Clinical documentation from Handi-Craft Company in March 2026 confirms that pairing 100% medical-grade silicone nipples across six calibrated flow levels with internal vent systems reduces infant spit-up, burping, and gas while preserving consistent flow rates [7]. Mothers shopping for maternity care products nonetheless note that silicone teats can cloud over time from milk-fat lipids if not washed with enzymatic detergents.
- In 2026, Silicone Orthodontic Anti-Colic Nipples are anticipated to capture 68.0% of global nipple teat type demand, reflecting pediatric endorsement of vented peristaltic latches.
- Segment adoption is projected to strengthen further through 2036 as brands introduce asymmetric matte-textured silicone zones that mimic maternal areola elasticity during combination feeding.
How do Small Infant Bottles Below 150ml lead the bottle capacity category?
Small Infant Bottles Below 150ml account for an expected 52.0% of bottle capacity volume in 2026, driven by hospital maternity starter kits and frequent colostrum and newborn feeding schedules.
Small-capacity feeding vessels holding 60ml to 150ml generate the highest unit velocity across the industry because every newborn requires slow, frequent 60ml-to-90ml feeds during the first twelve weeks of life before graduating to larger containers. Hospital maternity wards, neonatal intensive care units, and prenatal gift registries include three to four small-capacity bottles in every starter bundle to minimize air headspace above the milk column and measure colostrum intake accurately. Mothers utilizing lactation nutrition products also keep 120ml vessels in breast-pump bags for direct expression and chilled storage, although short three-month usage windows require parents to purchase 240ml bottles once infant stomach capacity expands.
- By bottle capacity, Small Infant Bottles Below 150ml are estimated to reach 52.0% of category share in 2026, supported by universal inclusion in hospital discharge packs and newborn starter sets.
- National natality statistics published by the U.S. CDC NCHS in March 2025 confirmed that neonatal intensive care unit admission rates reached 51.6% among preterm infants and 51.7% among low-birthweight newborns requiring specialized small-volume graduated feeding vessels [8].
Why do Specialty Maternity and Baby Stores lead the sales channel category?
Specialty Maternity and Baby Stores secure an anticipated 44.0% of sales channel demand in 2026, supported by guided baby-registry consultations and multi-stage teat replacement assortments.
Specialty maternity and nursery chains retain the largest revenue share across distribution channels since first-time parents rely on in-store registry advisors to compare anti-colic vent assemblies, nipple flow stages, and sterilizer compatibility before childbirth. Unlike general supermarkets that stock only two or three fast-moving plastic SKUs, specialty baby retailers carry full multi-stage PPSU and borosilicate glass collections with spare replacement teats and breast-pump adapters. In October 2026, Artsana Group documented in its consolidated 2025 Sustainability Report that its Chicco omnichannel specialty retail and nursery network operates under strict ISO quality verification and eco-designed packaging standards across Europe and global markets [9]. High store-lease overheads in metropolitan shopping centers still challenge standalone boutiques, prompting specialty chains to link physical registry showrooms with mobile home-delivery apps.
- Strong prenatal registry conversion places Specialty Maternity and Baby Stores on course to hold an estimated 44.0% share of the sales channel category in 2026.
- Channel momentum through 2036 will depend on omnichannel baby-registry integration, where expectant parents inspect bottle ergonomics in person and automate recurring nipple replacement shipments online.
What gives Wide-Neck Ergonomic Bottles the leading position in neck configuration?
Wide-Neck Ergonomic Bottles command a projected 61.0% of neck configuration share in 2026, enabled by breast-like latch geometry and simplified powder-scoop filling.
Wide-neck feeding bottles with 50mm-to-65mm collar openings lead buyer selection given that a broad, naturally sloped nipple base encourages infants to open their mouths wide and achieve a deep peristaltic latch identical to breastfeeding. Caregivers preparing midnight feeds also favor wide-neck vessels since formula powder scoops drop cleanly into the mouth without spilling on kitchen counters, and bottle brushes reach the interior base without awkward angles. Mothers pairing expressed milk with lactation protein beverages face one minor trade-off, as wide-neck vessels require wider pockets in insulated diaper bags and specific adapter rings when connecting to standard-neck hospital breast pumps.
- Wide-Neck Ergonomic Bottles are predicted to secure 61.0% of neck configuration demand in 2026, supported by lactation-consultant recommendations for breast-to-bottle transition.
- In May 2025, Koninklijke Philips NV partnered with March of Dimes to integrate maternal and infant feeding guidance into its Philips Avent Pregnancy+ platform, reinforcing wide-neck Natural Response bottle adoption among expectant mothers [10].
What are the drivers, restraints, and opportunities in the Baby Bottle Market?
In the baby bottle market, rising dual-income maternal employment and clinical anti-colic vent engineering are projected to drive adoption, while microplastic leaching scrutiny under high-heat sterilization restrains low-grade homopolymer polypropylene and medical-grade PPSU and silicone formats create new premium replacement avenues.
- Driver: Rising maternal labor-force participation and clinical endorsement of combination breast-and-bottle feeding accelerate household purchases of anti-colic starter bundles and multi-stage silicone teats.
- Restraint: Scientific evidence of microplastic particle shedding from conventional homopolymer polypropylene during high-temperature steam sterilization restrains demand for low-cost plastic vessels.
- Opportunity: Expanding medical-grade polyphenylsulfone, silicone-sleeved borosilicate glass, and retail bottle-recycling take-back networks creates high-margin replacement demand across eco-conscious parents.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Short statutory maternity leave windows and rising dual-income household structures compel mothers returning to work within three to six months postpartum to adopt combination feeding regimens that pair breast expression with paced bottle feeding. To prevent nipple confusion that could prematurely end breastfeeding, pediatricians direct parents toward biomimetic wide-neck bottles featuring response valves that release milk only when the infant actively compresses the teat. In May 2025, the Seventy-Eighth World Health Assembly adopted a resolution extending global maternal and infant nutrition targets to 2030, setting a benchmark to raise exclusive and supported early-life breastfeeding rates to at least 60% while tightening digital marketing standards [11]. This clinical focus on preserving natural sucking physiology directly drives demand for premium peristaltic and anti-colic bottle systems that support combination-feeding families.
Risk Assessment of the Baby Bottle Market: Operational and Formulation Friction
Heightened toxicological scrutiny over microplastic shedding and endocrine-disrupting chemical migration during boiling and microwave steam sterilization is restraining sales of commodity plastic baby bottles. Simultaneously, strict hospital compliance with the WHO International Code of Marketing of Breast-Milk Substitutes restricts direct promotional sampling of standard feeding bottles inside maternity wards, squeezing mid-tier suppliers that lack differentiated clinical claims. Bottle manufacturers must therefore absorb higher resin certification costs and pair feeding vessels with digital pacifier thermometers and hospital-grade sterilization assurance to protect retail shelf space.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Nursery brands capture substantial margin expansion by transitioning parents from single-use commodity plastics into closed-loop bottle recycling programs, silicone-protected borosilicate glass, and medical-grade polyphenylsulfone vessels. Expectant Millennial and Gen-Z parents willingly pay a 40% to 70% retail price premium for bottles certified free of bisphenols, phthalates, and nitrosamines when accompanied by verifiable end-of-life circularity.
Baby Bottle Market by Country (2026 to 2036)
FMI country modeling indicates that the United Kingdom leads baby bottle market expansion at a 5.9% CAGR through 2036, followed closely by Poland at 5.8% and Canada at 5.7%. National growth rates reflect differences in hospital maternity discharge practices, pharmacy versus baby-registry retail concentration, and parental conversion from standard polypropylene to PPSU and glass vessels.
Table 7: Country CAGR and Primary Growth Levers for the Baby Bottle Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United Kingdom | 5.9% | 34.6% non-UK-born maternal birth share and high-street nursery bundle trade-up |
| Poland | 5.8% | Strict EU food-contact safety alignment and pharmacy-led infant feeding retail |
| Canada | 5.7% | 98.1% hospital delivery share across 374,708 births and bilingual registry retail |
| Brazil | 5.6% | 99%+ registered live-birth hospital coverage and drugstore installment plans |
| Italy | 5.5% | Older first-time maternal age profile driving premium borosilicate glass spend |
| United States | 5.4% | 3.61 million annual births and hospital NICU graduated-flow bottle protocols |
| France | 5.2% | 643,905 annual births and pharmacy dispensation of anti-reflux glass bottles |
| Japan | 4.9% | PPSU nursing bottle standardization and 141-site retail bottle recycling loops |
Source: Future Market Insights analysis
United Kingdom Baby Bottle Market Outlook (2026 to 2036)
Demand for baby bottles in the United Kingdom is projected to expand at a leading 5.9% CAGR between 2026 and 2036 as British parents trade up to multi-bottle anti-colic starter bundles and heat-sensing glass vessels. What distinguishes the United Kingdom from continental Europe is the high concentration of prenatal registry spending through national nursery chains and pharmacy-led NHS family hubs. Official demographic bulletins published by the UK Office for National Statistics in September 2026 recorded 585,396 live births across England and Wales in 2025, with 34.6% of births occurring to non-UK-born mothers and standardized mean maternal age rising steadily [14]. Older first-time British parents with higher disposable household incomes actively specify Tommee Tippee, Philips Avent, and MAM self-sterilizing and borosilicate glass bottle kits.
Key takeaway: In the United Kingdom, older maternal demographics and high-value prenatal starter kit bundles are projected to sustain a leading 5.9% CAGR through 2036.
Poland Baby Bottle Market Outlook (2026 to 2036)
Poland is anticipated to register a 5.8% CAGR in baby bottle sales from 2026 to 2036, outpacing Western European volume averages as domestic families shift expenditure toward pharmacy-verified orthodontic and anti-colic feeding systems. Compared with mature Western markets where mass supermarkets dominate basic plastic bottle sales, Polish caregivers purchase infant feeding hardware primarily through specialized dermo-pharmacies and maternity e-commerce portals. In December 2025, the USDA Foreign Agricultural Service documented Poland's updated 2025 packaging and food-contact compliance statutes aligning national food-contact inspection with European Union safety directives [15]. Strict enforcement of EU Regulation 10/2011 on plastic food-contact materials accelerates Polish retail replacement of legacy polycarbonate and low-grade plastics with imported German and Austrian PPSU and borosilicate glass bottles.
Key takeaway: In Poland, pharmacy-centered nursery shopping and strict EU food-contact compliance are anticipated to drive a 5.8% CAGR over the forecast period.
Canada Baby Bottle Market Outlook (2026 to 2036)
The Canadian baby bottle market is forecast to expand at a 5.7% CAGR between 2026 and 2036, anchored by near-universal hospital delivery care and strong omnichannel baby-registry adoption across major provinces. Canadian demand differs from European patterns due to generous twelve-to-eighteen-month federal parental leave combined with high rates of expressed breastmilk bottle feeding during winter travel and daycare transitions. In September 2026, Statistics Canada reported that 98.1% of all Canadian births in 2025 took place inside hospitals while only 6,976 babies or 1.9% were born outside hospital maternity wards [16]. Hospital lactation consultants across Canadian provinces routinely guide new parents toward slow-flow silicone nipple bottles that preserve breastfeeding latch mechanics.
Key takeaway: In Canada, hospital-guided lactation protocols and high breastmilk pumping rates are forecast to support a 5.7% CAGR through 2036.
Brazil Baby Bottle Market Outlook (2026 to 2036)
Sales of baby bottles in Brazil are estimated to grow at a 5.6% CAGR from 2026 to 2036, supported by Latin America's largest infant population and expanding private maternity hospital networks across southeastern urban centers. What sets Brazil apart from North American and European markets is the central role of national drugstore chains that offer interest-free credit installment plans on premium imported Philips Avent, Chicco, and MAM feeding sets. In May 2026, the Brazilian Institute of Geography and Statistics reported that national live-birth civil registration coverage surpassed 99% for the first time as maternal hospital delivery access expanded across all five macro-regions [17]. Mandatory ANVISA certification on bisphenol-free polymers and orthodontic nipple airflow perforations further channels Brazilian middle-class buyers toward branded pharmacy assortments.
Key takeaway: In Brazil, expanding private maternity care and drugstore installment financing for ANVISA-certified bottles are estimated to drive a 5.6% CAGR.
Italy Baby Bottle Market Outlook (2026 to 2036)
In Italy, the baby bottle market is projected to advance at a 5.5% CAGR over the 2026 to 2036 window as per-infant nursery expenditure rises sharply among older dual-income urban households. Even as national birth counts contract, Italian parents and extended family gift-givers allocate among Europe's highest per-child budgets toward pharmaceutical-grade borosilicate glass bottles and Italian-made Chicco PhysioForma silicone teats. Demographic data released by the Italian National Institute of Statistics in October 2025 recorded 369,944 resident births paired with one of Europe's highest mean maternal ages at childbirth [18]. Independent municipal pharmacies and prenatal boutiques across northern and central Italy capitalize on this demographic profile by merchandising hybrid glass-lined plastic bottles and clinical anti-regurgitation vessels.
Key takeaway: In Italy, concentrated gift spending per newborn and strong pharmacy loyalty to domestic nursery brands are projected to sustain a 5.5% CAGR.
United States Baby Bottle Market Outlook (2026 to 2036)
Commercial demand in the United States is anticipated to progress at a 5.4% CAGR between 2026 and 2036, representing the single largest national revenue pool for anti-colic internal-vent bottles and medical-grade silicone vessels. American purchasing patterns diverge from European norms because U.S. mothers frequently return to full-time employment within six to twelve weeks postpartum, creating intense demand for breast-pump-compatible wide-neck bottles and daycare-labeled multi-packs. In July 2025, the CDC National Center for Health Statistics documented in NCHS Data Brief No. 535 that U.S. general fertility stood at 53.8 births per 1,000 females aged 15 to 44 paired with rising maternal childbirth ages above 30 [19]. Higher-income older first-time American parents actively trade up from standard polypropylene toward Dr. Brown's borosilicate glass, Philips Avent Natural Response, and Comotomo liquid silicone bottles.
Key takeaway: In the United States, early maternal return-to-work pumping routines and FDA safety awareness are anticipated to anchor a 5.4% CAGR through 2036.
France Baby Bottle Market Outlook (2026 to 2036)
Market expansion in France is projected to record a 5.2% CAGR over the 2026 to 2036 horizon, anchored by Europe's second-highest fertility rate and a deeply entrenched culture of pediatric pharmacy consultation. French parents differ from mass-market buyers elsewhere by strongly preferring tempered borosilicate glass bottles manufactured domestically or within the European Union to avoid any potential bisphenol or microplastic migration. In July 2026, France's National Institute of Statistics and Economic Studies reported that 643,905 babies were born across France in 2025 while the national total fertility rate remained among the highest in the European Union [20]. Mandatory credentialing for French crèche childcare facilities also sustains multi-bottle household purchases as infants transition from maternity leave into municipal daycares at three to four months of age.
Key takeaway: In France, sustained birth volumes of 643,905 babies and strong parental preference for pharmacy-dispensed glass bottles are estimated to support a 5.2% CAGR.
Japan Baby Bottle Market Outlook (2026 to 2036)
Japanese baby bottle demand is slated to progress at a 4.9% CAGR across the 2026 to 2036 period, led by rapid premiumization toward amber-tinted polyphenylsulfone vessels and stage-calibrated peristaltic silicone nipples. Compared with Western markets where standard polypropylene still holds a large volume base, Japanese maternity hospitals and specialty chains such as Akachan Honpo specify heat-resistant PPSU and borosilicate glass as the default standard for newborn feeding. In November 2025, Pigeon Corporation expanded its specialized neonatal feeding portfolio by launching online direct access to colostrum feeding vessels and silicone long-nipple feeders engineered for low-birthweight and cleft-palate infants [21]. High domestic replacement frequency for stage-specific SofTouch silicone nipples and growing inbound tourist purchases of Japanese nursing bottles sustain steady value growth.
Key takeaway: In Japan, hospital standardization on PPSU nursing bottles and clinical neonatal teat engineering are forecast to maintain a 4.9% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Baby Bottle Market?
Koninklijke Philips NV, Pigeon Corporation, Handi-Craft Company Dr Browns, Mayborn Group Ltd Tommee Tippee, MAM Babyartikel GmbH, Evenflo Feeding Inc., Chicco Artsana SpA, Newell Brands Inc. NUK, Lansinoh Laboratories Inc., and Comotomo Inc. are the notable companies in the baby bottle market.
Competitive positioning in the baby bottle industry divides clinical anti-colic leaders, integrated nursery brands, and specialized silicone innovators. Koninklijke Philips NV and Pigeon Corporation lead global hospital and maternity-store shelves joined by Handi-Craft Company Dr Browns and Mayborn Group Ltd Tommee Tippee through proprietary vent valves and PPSU or glass lines. MAM Babyartikel GmbH and Evenflo Feeding Inc. compete with Chicco Artsana SpA and Newell Brands Inc. NUK via orthodontic teat geometry and temperature-sensing vessels, while Lansinoh Laboratories Inc. and Comotomo Inc. target combination-feeding and pure liquid-silicone niches.
- Clinical Anti-Colic and Peristaltic Leaders: Philips Avent and Pigeon Corporation, joined by Dr. Brown's and Tommee Tippee, engineer hospital-validated internal vent systems and response-valve silicone teats.
- Integrated Nursery and Orthodontic Specialists: MAM Babyartikel and Evenflo Feeding, joined by Chicco Artsana and Newell NUK, supply self-sterilizing vented bases and temperature-indicator bottles.
- Breastfeeding-Transition and Silicone Innovators: Lansinoh Laboratories Inc. and Comotomo Inc. specialize in slow-flow peristaltic nipples for breastfed infants and squeezable medical-grade liquid silicone vessels.
Competitive Benchmarking: Baby Bottle Market
Table 8: Competitive Benchmarking for the Baby Bottle Market (qualitative capability ratings), 2026
| Company | Anti-Colic Vent Engineering | PPSU & Glass Portfolio Depth | Hospital & Registry Reach | Geographic Reach |
|---|---|---|---|---|
| Koninklijke Philips NV | High | High | High | Global Philips Avent network; Natural Response and Glass series across 100+ countries |
| Pigeon Corporation | High | High | High | East Asia, ASEAN, North America, and Middle East; SofTouch PPSU leader |
| Handi-Craft Company Dr Browns | High | High | High | North America and global NICU/pediatrician-recommended internal vent systems |
| Mayborn Group Ltd Tommee Tippee | High | Medium | High | UK, North America, Australia, and Europe Closer to Nature and Advanced Anti-Colic lines |
| MAM Babyartikel GmbH | High | High | Medium | Europe and Americas; patented self-sterilizing vented base and SkinSoft silicone |
| Evenflo Feeding Inc. | Medium | Medium | Medium | North America mass-retail and lactation-consultant Balance+ wide-neck bottles |
| Chicco Artsana SpA | High | High | High | Italy, Western Europe, and Latin America pharmacy and specialty maternity stores |
| Newell Brands Inc. NUK | High | Medium | High | North America and Germany; Perfect Match temperature-control indicator bottles |
| Lansinoh Laboratories Inc. | Medium | Medium | High | Global breastfeeding-to-bottle NaturalWave peristaltic nipple specialist |
| Comotomo Inc. | Medium | High | Medium | North America, East Asia, and Europe medical-grade liquid silicone squeeze bottles |
Key Developments in the Baby Bottle Market
- In May 2026, Comotomo Inc. released the second generation of its silicone baby bottle, the Comotomo Baby Bottle Gen 2, featuring a refined wide-mount nipple with built-in dual air vents and an updated body geometry. The product was introduced at Target stores nationwide and on Target.com, targeting parents seeking skin-soft silicone bottle alternatives for breastfed infants [25].
- In May 2025, Koninklijke Philips N.V. announced a collaboration with March of Dimes to integrate evidence-based maternal and pregnancy health content into the Philips Avent Pregnancy+ app, one of the world’s most downloaded pregnancy applications. The partnership provides expectant and new mothers with guidance on topics including preterm birth, neonatal intensive care unit preparation, and newborn feeding [26].
- In February 2026, Pigeon Corporation launched its 9th Medium-Term Management Plan covering the fiscal years 2026 to 2028, with the Nursing Bottles and Nipples product category designated as the primary focus for concentrated investment. The plan targets consolidated net sales of JPY 125 billion and an operating profit margin of 16.0% by the close of the plan period [27].
Key Players in the Baby Bottle Market
Clinical Anti-Colic and Peristaltic Leaders
- Koninklijke Philips NV
- Pigeon Corporation
- Handi-Craft Company Dr Browns
- Mayborn Group Ltd Tommee Tippee
Integrated Nursery and Orthodontic Specialists
- MAM Babyartikel GmbH
- Evenflo Feeding Inc.
- Chicco Artsana SpA
- Newell Brands Inc. NUK
Breastfeeding-Transition and Silicone Innovators
- Lansinoh Laboratories Inc.
- Comotomo Inc.
Baby Bottle Market - Report Scope
Table 9: Report Scope for the Baby Bottle Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Bottle Material; Nipple Teat Type; Bottle Capacity; Sales Channel; Neck Configuration |
| Quantitative Units | USD Billion |
| Market Definition | Includes global manufacturer revenue from commercial infant feeding bottles (polypropylene, polyphenylsulfone PPSU, borosilicate glass, food-grade liquid silicone, and insulated stainless steel) and packaged replacement feeding nipples/teats. Category Scope Note: Excludes standalone electric breast pumps, electric steam sterilizers, bottle warmers, and toddler spill-proof sippy cups. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United Kingdom, Poland, Canada, Brazil, Italy, United States, France, Japan, and additional countries in the full report |
| Key Companies Covered | Koninklijke Philips NV, Pigeon Corporation, Handi-Craft Company Dr Browns, Mayborn Group Ltd Tommee Tippee, MAM Babyartikel GmbH, Evenflo Feeding Inc., Chicco Artsana SpA, Newell Brands Inc. NUK, Lansinoh Laboratories Inc., Comotomo Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Baby Bottle Market - Research Methodology
Table 10: Research Methodology for the Baby Bottle Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with neonatal lactation consultants, pediatric feeding therapists, polymer injection-molding directors, and specialty maternity store category buyers to validate multi-bottle starter kit sizes and 8-to-12-week silicone teat replacement cadences. |
| Secondary Research | Analysis of CDC National Center for Health Statistics (NCHS) birth registries, UK ONS and INSEE demographic bulletins, FDA food-contact polymer safety dockets, PubMed Central microplastic migration studies, and corporate annual reports. |
| Market Sizing and Forecasting | Top-down infant care expenditure baselines reconciled against bottom-up national live-birth cohorts, combination breast-and-bottle feeding rates, and average retail unit prices across PP, PPSU, glass, and liquid silicone vessels from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight national hospital delivery shares, maternal workforce participation rates, preterm neonatal care protocols, and specialty pharmacy versus e-commerce registry distribution across eight countries. |
| Operational Benchmark Traceability | Unit shipment, replacement nipple volume, and birth-cohort indicators in Tables 2, 3, and 4 trace to CDC NCHS Data Brief No. 571, UK ONS 2025 Birth Summary Tables, and Pigeon Corporation sustainability and IR disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate infant feeding bottles and replacement teats while strictly excluding standalone breast expression pumps, counterfactual electrical nursery appliances, and powdered infant formula. |
Baby Bottle Market by Segments
Baby Bottle Market segmented by Bottle Material:
- Polypropylene and Polyphenylsulfone PPSU Plastic
- Borosilicate Tempered Glass
- Food-Grade Liquid Silicone
- Stainless Steel Insulated
Baby Bottle Market segmented by Nipple Teat Type:
- Silicone Orthodontic Anti-Colic Nipples
- Natural Rubber Latex Nipples
- Variable Flow Controlled Teats
- Specialty Cleft and Preterm Teats
Baby Bottle Market segmented by Bottle Capacity:
- Small Infant Bottles Below 150ml
- Standard Bottles 150ml to 250ml
- Toddler Large Bottles Above 250ml
- Ultra-Compact Colostrum Collectors
- Twin and Multi-Feed Modular Kits
Baby Bottle Market segmented by Sales Channel:
- Specialty Maternity and Baby Stores
- Pharmacies and Drugstores
- Supermarkets and Hypermarkets
- Online E-Commerce Portals
Baby Bottle Market segmented by Neck Configuration:
- Wide-Neck Ergonomic Bottles
- Standard Narrow-Neck Bottles
- Angled Anti-Reflux Neck Bottles
- Disposable Liner Holder Shells
Baby Bottle Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Hamilton, B. E., & Osterman, M. J. K. (2026, October 21). Births in the United States, 2025 (NCHS Data Brief No. 571). U.S. Department of Health and Human Services, Centers for Disease Control and Prevention, National Center for Health Statistics.
- [2] Pigeon Corporation. (2026, February 13). 9th Medium-Term Management Plan: FY Dec. 2026 (70th) to FY Dec. 2028. Pigeon Corporation Investor Relations.
- [3] National Library of Medicine. (2025, December 15). Microplastics and child health: A scoping review of prenatal and early-life exposure (PMCID: PMC12554039). PubMed Central Open Access.
- [4] Mishra, S. K., Sanyal, T., Kundu, P., & Das, A. (2025, October 8). Microplastics as emerging carcinogens: from environmental pollutants to oncogenic drivers. Molecular Cancer, 24, 248 (PubMed Central PMCID: PMC12505851).
- [5] U.S. Food and Drug Administration. (2025, April 20). Bisphenol A (BPA): Use in Food Contact Application. U.S. Department of Health and Human Services, Food and Drug Administration.
- [6] Comisi, F. F., Comisi, A. M., Esposito, E., & Fanos, V. (2026, May 18). Exposure to Microplastics in Biological Matrices and Neurodevelopmental Outcomes in Children: A Systematic Review. Nanomaterials, 16(10), 618 (MDPI Open Access).
- [7] Handi-Craft Company. (2026, March 18). Dr. Brown's Natural Flow Anti-Colic Options+ Wide-Neck Baby Bottle and Silicone Nipple Specifications. Dr. Brown's Baby Product Technical Documentation.
- [8] Centers for Disease Control and Prevention. (2025, March 19). NICU Admission Rates by Gestational Age and Birthweight: United States (NCHS Data Brief No. 525). U.S. Department of Health and Human Services, CDC National Center for Health Statistics.
- [9] Artsana Group. (2026, October 14). Sustainability Report 2025 | Artsana. Artsana S.p.A. Corporate Sustainability Publications.
- [10] Koninklijke Philips N.V. (2025, May 28). Philips and March of Dimes bring maternal and pregnancy health content to Philips Avent Pregnancy+ app. Koninklijke Philips N.V. Press Archive.
- [11] World Health Organization. (2025, May 27). World Health Assembly re-commits to global nutrition targets and marketing regulations. World Health Organization Official News Releases.
- [12] Medela LLC. (2025, July 1). Our Commitment to Breastfeeding. Medela AG Lactation Professional Bulletins.
- [13] Pigeon Corporation. (2026, May 20). Recycling Activities | Environment | Pigeon Global: Baby Nursing Bottle Recycling. Pigeon Global Environmental Sustainability Division.
- [14] Office for National Statistics. (2026, September 8). Births in England and Wales: 2025 (final rates). UK Office for National Statistics.
- [15] USDA Foreign Agricultural Service. (2025, December 30). Report Name: FAIRS Country Report Annual (Warsaw, Poland, PL2025-0028). U.S. Department of Agriculture Global Agricultural Information Network.
- [16] Statistics Canada. (2026, September 23). The Daily: Births, 2025. Government of Canada, Statistics Canada.
- [17] Instituto Brasileiro de Geografia e Estatística. (2026, May 20). For the first time, under-registration of live births was below 1%. IBGE News Agency Official Statistics.
- [18] Istituto Nazionale di Statistica. (2025, October 30). Births and fertility of the resident population: Year 2024. Istat Population and Households Official Statistics.
- [19] Centers for Disease Control and Prevention. (2025, July 24). NCHS Data Brief No. 535: Births in the United States, July 2025. U.S. Department of Health and Human Services, CDC National Center for Health Statistics.
- [20] Institut National de la Statistique et des Études Économiques. (2026, July 6). Births in 2025: Insee Focus No. 383. INSEE Official Demographic Statistics.
- [21] Pigeon Corporation. (2025, November 18). New products and services for babies needing support: Expanding the range of products for low-birthweight babies and babies with cleft lip and/or palate. Pigeon Global Social Sustainability Division.
- [22] Newell Brands Inc. (2026, September 23). How Innovation and Execution Helped Newell Brands' Baby Business Gain Share. Newell Brands Corporate Stories.
- [23] Newell Brands Inc. (2026, May 4). NUK Reborn: The Brand's Modern Approach to Supporting Parents. Newell Brands Corporate Stories.
- [24] Newell Brands Inc. (2025, August 18). Newell Brands' Baby Business Earns Industry Accolades in 2025. Newell Brands Corporate Newsroom.
- [25] Comotomo Inc. (2026). Baby Bottle Gen 2. https://comotomo.com/products/baby-bottle-2
- [26] Koninklijke Philips N.V. (2025, May 28). Philips and March of Dimes Bring Maternal and Pregnancy Health Content to Philips Avent Pregnancy+ App. Business Wire. https://www.businesswire.com/news/home/20250528250376/en
- [27] Pigeon Corporation. (2026). Q1 FY2026 Financial Results — 9th Medium-Term Management Plan Overview. https://quartr.com/events/pigeon-corporation-7956-q1-2026_F6ZHtk20
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the baby bottle market in 2026 and what is forecast for 2036?
- Which combination-feeding and high-heat sterilization factors support demand for baby bottles?
- Why does Polypropylene and Polyphenylsulfone PPSU Plastic lead the bottle material category?
- Why do Silicone Orthodontic Anti-Colic Nipples lead the nipple teat type category?
- How do growth rates differ across the United Kingdom, Poland, and Canada?
- Which leading companies supply hospital-validated anti-colic bottles versus specialty silicone vessels?
- What microplastic migration hurdles restrain low-grade polypropylene baby bottles?
- What should maternity retailers evaluate when curating PPSU and borosilicate glass starter kits?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Bottle Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Bottle Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Bottle Material, 2026 to 2036
- Polypropylene and Polyphenylsulfone PPSU Plastic
- Borosilicate Tempered Glass
- Food-Grade Liquid Silicone
- Stainless Steel Insulated
- Y-o-Y Growth Trend Analysis By Bottle Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Bottle Material, 2026 to 2036
- Global Market Analysis and Forecast, By Nipple Teat Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nipple Teat Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nipple Teat Type, 2026 to 2036
- Silicone Orthodontic Anti-Colic Nipples
- Natural Rubber Latex Nipples
- Variable Flow Controlled Teats
- Specialty Cleft and Preterm Teats
- Y-o-Y Growth Trend Analysis By Nipple Teat Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Nipple Teat Type, 2026 to 2036
- Global Market Analysis and Forecast, By Bottle Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Bottle Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Bottle Capacity, 2026 to 2036
- Small Infant Bottles Below 150ml
- Standard Bottles 150ml to 250ml
- Toddler Large Bottles Above 250ml
- Ultra-Compact Colostrum Collectors
- Twin and Multi-Feed Modular Kits
- Y-o-Y Growth Trend Analysis By Bottle Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Bottle Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Specialty Maternity and Baby Stores
- Pharmacies and Drugstores
- Supermarkets and Hypermarkets
- Online E-Commerce Portals
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Neck Configuration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Neck Configuration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Neck Configuration, 2026 to 2036
- Wide-Neck Ergonomic Bottles
- Standard Narrow-Neck Bottles
- Angled Anti-Reflux Neck Bottles
- Disposable Liner Holder Shells
- Y-o-Y Growth Trend Analysis By Neck Configuration, 2021 to 2025
- Absolute $ Opportunity Analysis By Neck Configuration, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Bottle Material
- By Nipple Teat Type
- By Bottle Capacity
- By Sales Channel
- By Neck Configuration
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Koninklijke Philips NV
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pigeon Corporation
- Handi-Craft Company Dr Browns
- Mayborn Group Ltd Tommee Tippee
- MAM Babyartikel GmbH
- Evenflo Feeding Inc.
- Chicco Artsana SpA
- Newell Brands Inc. NUK
- Lansinoh Laboratories Inc.
- Comotomo Inc.
- Koninklijke Philips NV
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Bottle Material, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Nipple Teat Type, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Bottle Capacity, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Neck Configuration, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Bottle Material
- Figure 6: Global Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Nipple Teat Type
- Figure 9: Global Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Bottle Capacity
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Neck Configuration
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Bottle Material
- Figure 32: North America Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Nipple Teat Type
- Figure 35: North America Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Bottle Capacity
- Figure 38: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sales Channel
- Figure 41: North America Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Neck Configuration
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Bottle Material
- Figure 48: Latin America Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Nipple Teat Type
- Figure 51: Latin America Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Bottle Capacity
- Figure 54: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Neck Configuration
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Bottle Material
- Figure 64: Western Europe Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Nipple Teat Type
- Figure 67: Western Europe Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Bottle Capacity
- Figure 70: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Neck Configuration
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Bottle Material
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Nipple Teat Type
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Bottle Capacity
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Neck Configuration
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Bottle Material
- Figure 96: East Asia Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Nipple Teat Type
- Figure 99: East Asia Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Bottle Capacity
- Figure 102: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Neck Configuration
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Bottle Material
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Nipple Teat Type
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Bottle Capacity
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Neck Configuration
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Bottle Material, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Bottle Material, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Bottle Material
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Nipple Teat Type, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Nipple Teat Type, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Nipple Teat Type
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Bottle Capacity, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Bottle Capacity, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Bottle Capacity
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Neck Configuration, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Neck Configuration, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Neck Configuration
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Baby Bottle Market in 2026, and what is forecast for 2036?
FMI calculates 2025 global baby bottle demand at USD 3.6 billion, climbing to USD 3.8 billion in 2026 and reaching a targeted USD 6.5 billion by 2036.
What is the CAGR for the Baby Bottle Market from 2026 to 2036?
The baby bottle sector is projected to expand at a 5.5% CAGR over the 2026 to 2036 window, generating USD 2.7 billion in incremental revenue across maternity channels.
Which bottle material segment leads the Baby Bottle Market?
Polypropylene and Polyphenylsulfone PPSU Plastic holds an estimated 58.0% of bottle material demand in 2026 since impact-resistant medical polymers tolerate daily boiling and autoclaving.
Which nipple teat type segment leads the baby bottle market?
Silicone Orthodontic Anti-Colic Nipples represent an estimated 68.0% of the nipple teat type category in 2026 owing to latex-free durability and internal pressure-equalizing vents.
Which country has a notable growth outlook during the assessment period?
The United Kingdom leads national expansion projections at a 5.9% CAGR through 2036, supported by high-value prenatal starter bundle purchases and combination-feeding adoption.
Who are the key players in the market?
Koninklijke Philips NV and Pigeon Corporation lead global baby bottle supply with Handi-Craft Dr. Brown's and Mayborn Tommee Tippee. MAM and Evenflo also compete globally with Chicco, Newell NUK, Lansinoh and Comotomo.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
