

- Market Size (2026)
- USD 6.8 Bn
- Forecast (2036)
- USD 9.7 Bn
- CAGR (2026 to 2036)
- 3.7%
How big is Baby Personal Care Market in 2026?
A 3.67% CAGR defines baby personal care growth between 2026 and 2036. USD 6.53 billion in 2025 becomes USD 6.77 billion in 2026 on the estimate and USD 9.71 billion in 2036 on the projection.
The 2026 baby personal care market is estimated at USD 6.77 billion, up from USD 6.53 billion in 2025. Sales will rise to USD 9.71 billion by 2036, a 3.67% CAGR across the next decade.
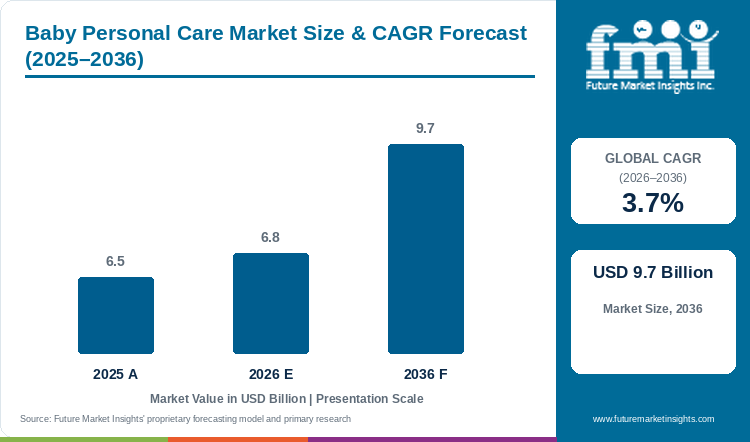
Births set the unit base for baby washes and creams, and births are falling in Germany and the UK. For instance, England and Wales recorded 585,396 live births in 2025, 1.6% fewer than in 2024, the Office for National Statistics reported in May 2026.[1] The mean age of mothers rose to 31.1 years.[1] Fewer and older first-time parents bring a shift in the industry's growth trajectory toward price and mix. Skin care, at an estimated 41.8% of 2026 product sales, will gain as parents trade up to fragrance-free washes and eczema creams.
Baby washes and creams are a small branch of the beauty and personal care product market, on an 8.2% CAGR from 2026 to 2036 in FMI data. Falling births hold baby lines to 3.67%, so beauty groups will favour adult ranges. Nappies share pharmacy baskets with baby washes, and the baby diaper market records a 6.2% CAGR, so washes and creams will lose ground to nappies in new-parent budgets.
FirstCry home brands will press harder on basic wipes, powders and shampoos as unit growth slows. Kenvue and other brand owners will then choose between defending hero products on price and adding cheaper lines.
Key Market Trends & Insights
- Product type: skin care holds about 41.8% (estimated), ahead of toiletries at an estimated 27.4%.
- Nature: synthetic formulations take an estimated 61.3%, and organic and natural lines about 38.7% (estimated).
- Age group: products for babies aged 0-6 months account for an estimated 31.4%.
- Sales channel: supermarkets and hypermarkets lead at about 29.6% (estimated). Kenvue said Baby Care helped drive organic growth in Essential Health in Q2 2026.[2]
Regional Highlights
- India posts the strongest profiled rate, a 7.1% CAGR over the decade to 2036.
- China comes second on 6.7%. The USA reaches 5.6% and Germany 5.3%, with the UK last on 4.9%.
- Germany recorded 654,241 births in 2025, the lowest post-war level, Destatis reported.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Baby Personal Care Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 6.53 billion |
| Estimated Market Size in 2026 | USD 6.77 billion |
| Projected Market Size by 2036 | USD 9.71 billion |
| CAGR, 2026 to 2036 | 3.67% |
| Added Revenue, 2026 to 2036 | USD 2.94 billion |
| Market Expansion Multiple | 1.4x |
Baby toiletries move more slowly than the wider beauty aisle. The beauty and personal care product market, parent to baby washes and creams, posts an 8.2% CAGR over the 2026 to 2036 decade, so adult skin and hair lines will claim more pharmacy shelf space. Nappies take a far bigger budget than washes and creams. Nappy sales in the baby diaper market post a 6.2% CAGR to 2036, and each nappy pack competes with creams for the same new-parent basket. Baby personal care, at a 3.67% CAGR in FMI figures, grows well below the 8.2% and 6.2% CAGRs. Parents will keep shifting budget toward higher-priced creams and washes inside a slow-growth unit base.
Birth Counts versus Spend per Baby
Birth data from three national offices show shrinking cohorts. Germany recorded 654,241 births in 2025, and the total fertility rate fell to 1.32 children per woman, the lowest level since 1997, Destatis said on 1 July 2026.[3] Births in England and Wales fell 1.6% in 2025, and the mean age of mothers rose to 31.1 years.[1] The CDC FastStats page, reviewed in September 2026, lists 3,628,934 US births and a fertility rate of 53.8 per 1,000 women aged 15 to 44 for 2024.[4] Fewer births will hold baby care unit volume flat in Germany, the UK and the USA.
Spend per baby is rising at Kenvue, the owner of Johnson's and Aveeno. Kenvue reported Essential Health organic sales growth of 1.1% in Q2 2026, with volume up 1.9%, and named Baby Care among the growth drivers.[2] Value realization added 2.7% to organic growth in Skin Health and Beauty.[2] Kimberly-Clark expects to complete the acquisition of Kenvue in the fourth quarter of 2026.[2] The FMI outlook puts market growth at a 3.67% CAGR, driven by price, premium skin care and older parents with higher incomes.
Table 2: Birth and Spend-per-Baby Indicators for the Baby Personal Care Market (counts, rates and percentage), mixed reporting years from 2024 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Live births, England and Wales, 2025 | 585,396, down 1.6% | A smaller cohort limits unit volume in the UK. | [1] |
| Total fertility rate, England and Wales, 2025 | 1.39 (provisional) | Fertility below replacement keeps cohorts shrinking. | [1] |
| Mean age of mothers, England and Wales, 2025 | 31.1 years | Older parents will lean toward premium purchases. | [1] |
| Births, Germany, 2025 | 654,241, lowest post-war level | Unit volume pressure in Germany. | [3] |
| Total fertility rate, Germany, 2025 | 1.32, down 2.7% | Lowest level since 1997. | [3] |
| Births, USA, 2024 | 3,628,934 | Base cohort for US unit volume. | [4] |
| Births, China, 2025 | 7.92 million; 5.63 per thousand | Small cohorts in the second-fastest profiled country. | [5] |
| Childcare subsidy, China, reported July 2025 | 3,600 yuan a year per child under three | Cash support for young families. | [6] |
| Registered births, India, 2024 | 2,54,73,389 | Large newborn base in the fastest profiled country. | [7] |
| Kenvue Essential Health organic growth, Q2 2026 | 1.1%, volume up 1.9% | Baby Care named among growth drivers. | [2] |
| Kenvue Skin Health and Beauty value realization, Q2 2026 | 2.7% | Price and mix lift value per unit. | [2] |
Analyst Perspective
“Falling birth numbers in Europe and the USA make spend per baby the main growth lever, and I see the clearest opportunity in dermatologist-backed skin care for newborns. Brands that earn paediatrician and pharmacy trust in India and China will add both volume and value through 2036.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the baby personal care market segmented?
Four product and shopper axes frame the baby personal care market, together with region. Skin care is the largest product type in 2026 at an estimated 41.8%.
By product type: toiletries, skin care, hair care, and others.
By nature: organic/natural and synthetic.
By age group: 0-6 months, 6-12 months, 12-24 months, and 25 months & above.
By channel of sale: wholesalers/distributors, specialty stores, supermarkets/hypermarkets, pharmacies/drug stores, online stores, and others.
By region: baby care buyers are covered in Latin America, Asia Pacific, Middle East & Africa, Europe, and North America.
Why does skin care lead baby personal care product sales?
Skin care tops the product split on an estimated 41.8% for 2026. Toiletries, hair care and other items come after.
Table 3: Product Type Share for the Baby Personal Care Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Skin Care | 41.8% |
| Toiletries | 27.4% |
| Hair Care | 19.6% |
| Others | 11.2% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Baby Personal Care Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.67% |
| Leading Segment | Skin Care |
Lotions, creams and barrier balms will be used daily at bath and nappy time, and daily use keeps skin care first. FMI expects skin care to keep the lead on awareness of infant skin sensitivity. Skin care holds an estimated 41.8%. Toiletries follow near 27.4% (estimated), hair care about 19.6% and others 11.2% (estimated). Kenvue reported 3.7% organic growth in Skin Health and Beauty for Q2 2026.[2] Eczema and dry-skin products will raise the value of each skin care purchase.
- Hair care will grow with tear-free and low-foam shampoos, and the organic baby shampoo market will draw parents who want natural tear-free shampoo.
- Kenvue tied Skin Health and Beauty growth largely to Hair Care and Face Care.[2]
Why do synthetic formulations lead baby personal care by nature?
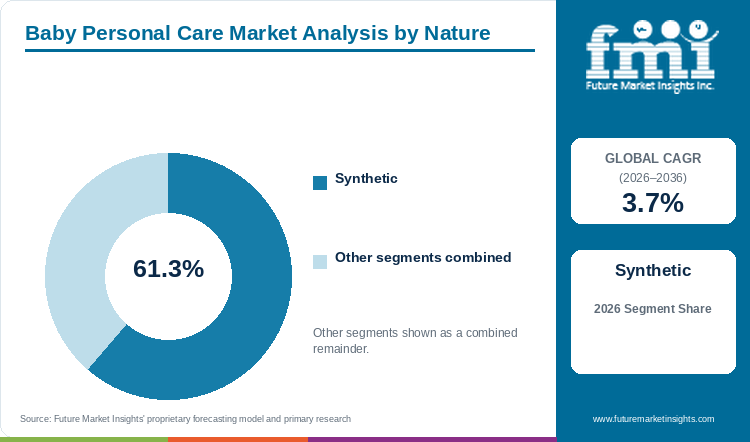
Synthetic formulations hold the larger nature slice, about 61.3% (estimated) in 2026. Organic and natural lines hold about 38.7% (estimated).
Table 5: Nature Share for the Baby Personal Care Market (percentage share), 2026
| Nature | Estimated Share (2026) |
|---|---|
| Synthetic | 61.3% |
| Organic/Natural | 38.7% |
| Total | 100.0% |
Price and shelf life will keep synthetic surfactants and preservatives in mass-market washes and lotions. Synthetic formulations hold about 61.3% (estimated). Organic and natural lines account for an estimated 38.7%. Natural ranges will gain share from the 38.7% base among older, higher-income parents. Ingredient costs will keep organic lines at a premium price point.
- Reformulated legacy lines will drop questionable ingredients from synthetic washes and lotions.
- Certified organic labels will carry the highest price per millilitre.
Why do products for babies aged 0-6 months lead age group sales?
The 0-6 months group leads age-based sales on about 31.4% (estimated) in 2026. Products for 6-12 months and 12-24 months follow.
Table 6: Age Group Share for the Baby Personal Care Market (percentage share), 2026
| Age Group | Estimated Share (2026) |
|---|---|
| 0-6 Months | 31.4% |
| 6-12 Months | 26.8% |
| 12-24 Months | 24.5% |
| 25 Months & Above | 17.3% |
| Total | 100.0% |
Newborn kits, hospital bags and gift sets will concentrate purchases in the first months. The 0-6 months group holds an estimated 31.4%. Products for 6-12 months take about 26.8% (estimated), 12-24 months about 24.5% and 25 months and above near 17.3% (estimated). Germany recorded the lowest post-war number of births in 2025.[3] Newborn spend will track each birth cohort closely, and older age groups will gain from longer use of baby-branded products.
- Toddler ranges will gain as parents keep baby brands for children past two years.
- England and Wales recorded 585,396 live births in 2025.[1]
Why do supermarkets and hypermarkets lead baby personal care sales channels?
Supermarkets and hypermarkets lead the 2026 channel split near 29.6% (estimated). Pharmacies and drug stores hold about 21.8%, and online stores about 19.7%, both estimated.
Table 7: Sales Channel Share for the Baby Personal Care Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Supermarkets/Hypermarkets | 29.6% |
| Pharmacies/Drug Stores | 21.8% |
| Online Stores | 19.7% |
| Specialty Stores | 12.4% |
| Wholesalers/Distributors | 9.8% |
| Others | 6.7% |
| Total | 100.0% |
Parents will keep buying baby washes and wipes with the weekly grocery shop, and grocery trips keep supermarkets and hypermarkets first. The supermarket and hypermarket channel holds an estimated 29.6%. Pharmacies and drug stores hold about 21.8% (estimated), online stores 19.7% and specialty stores 12.4% (estimated). Wholesalers and distributors account for an estimated 9.8%, and others 6.7%. Pharmacy and online channels will gain as parents seek dermatologist-backed ranges and subscription refills.
- Pharmacies will gain on eczema and sensitive-skin products.
- Online stores will gain on repeat orders of wipes and washes.
What are the drivers, restraints, and opportunities in the baby personal care market?
Demand for baby personal care rises with ingredient transparency, dermatologist-validated formulas and awareness of infant skin sensitivity. Growth of the baby personal care market faces falling births in Europe and the USA, and premium skin care in India and China offers the clearest opening.
- Driver: Parents pay for proven, gentle and transparent formulas.
- Restraint: Smaller birth cohorts and high costs of natural ingredients.
- Opportunity: Dermatologist-backed skin care in fast-growing Asian markets.
Ingredient Transparency Raises Spend per Baby
FMI points to ingredient transparency, dermatologist-validated formulations and awareness of infant skin sensitivity as main forces in demand. Kenvue reported 0.9% favorable value realization in Q2 2026 organic growth.[2] Parents will pay for short ingredient lists and clinical claims. The baby powder market grows at a 5% CAGR from USD 1.2 billion in 2026, as reformulated powders return to the shelf.
Shrinking Cohorts Cap Unit Volume
Destatis put the 2025 German total fertility rate at 1.32 children per woman, 2.7% below the year before.[3] Key challenges faced by manufacturers include falling births in mature markets and the cost of natural ingredients. FMI cites high regulatory costs and expensive natural ingredients as past brakes on growth. Baby care brands in Germany will cut slow-moving SKUs and focus shelf space on top sellers.
Premium Skin Care in India and China
India and China post CAGRs of 7.1% and 6.7% to 2036, the two fastest profiled rates. Sales potential is expected to emerge from dermatologist-backed skin care sold through pharmacies and online stores in large Asian cities. Kenvue said organic sales grew across every region in Skin Health and Beauty in Q2 2026.[2] The next stage of supply-chain expansion will take pharmacy-grade baby lines from global brands into tier-two cities, and the baby oral care market will follow the same premium route from a USD 1.4 billion base in 2025.
Which country CAGRs are profiled in the baby personal care market?
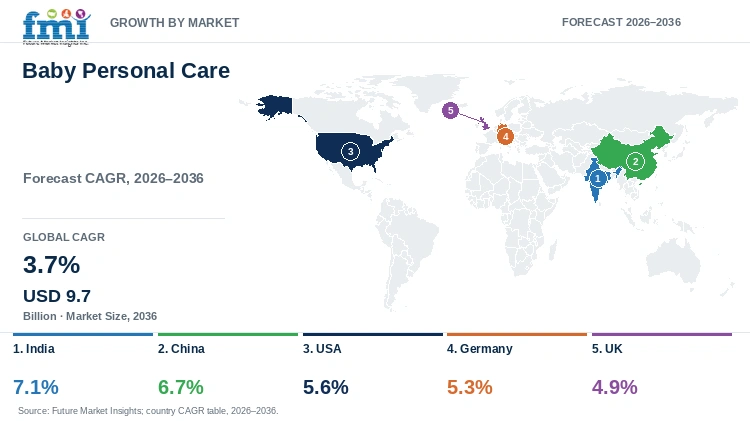
Table 8: Country CAGR Comparison for the Baby Personal Care Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| India | 7.1% |
| China | 6.7% |
| USA | 5.6% |
| Germany | 5.3% |
| UK | 4.9% |
How do country-level CAGRs compare in the baby personal care market?
Every profiled country runs ahead of the 3.67% global CAGR. FMI's country CAGRs place India first at 7.1% from 2026 to 2036 and China second at 6.7%. Rates for the USA and Germany come to 5.6% and 5.3%. The UK closes the group at 4.9%. Slower markets outside the five profiled countries will hold the global CAGR at 3.67%.
- India will add parents through organised retail growth.
- China will trade parents up to imported and premium domestic brands.
- The USA will see pharmacy and online channels gain.
- Germany faces the lowest post-war birth count, with growth from premium ranges.
- The UK grows slowest among the five as births fall again.
Full report country CAGRs cover: thirty-plus countries in Europe, Middle East & Africa, Asia Pacific, North America, and Latin America.
Country-wise Analysis
India Baby Personal Care Market Outlook (2026 to 2036)
Indian sales lead the five profiled countries on a 7.1% CAGR. India registered 2,54,73,389 births in 2024, above the 2,52,07,070 recorded in 2023, Outlook reported from the Civil Registration System report.[7] Institutional births formed 79.4% of registered births, excluding Sikkim.[7] Hospital deliveries give brands an early contact point with new parents. Brainbees Solutions, the FirstCry owner, posted India multi-channel GMV of INR 23,809 million in Q1 FY27.[8] Home brands made up over 58% of India multi-channel GMV in FY26.[8] FirstCry home brands like BabyHug will press branded toiletries on price. Domestic brands and global groups will compete for first-time parents in tier-two and tier-three cities. Ayurvedic and herbal claims will carry strong appeal in oils and massage products. Pharmacy chains and quick-commerce apps will widen reach beyond metro areas.
Key takeaway: India will add both volume and premium value, and herbal claims will shape product choice.
China Baby Personal Care Market Outlook (2026 to 2036)
China recorded 7.92 million births in 2025, a crude birth rate of 5.63 per thousand, according to the 2025 statistical communiqué of the statistics bureau.[5] The population aged 0 to 14 stood at 212.76 million.[5] A national childcare subsidy pays 3,600 yuan a year for each child under the age of three, the National Health Commission reported in July 2025.[6] The 3,600-yuan payments will free family budgets for washes, lotions and creams. Parents in China will spend more per child as family sizes stay small. Chinese sales expand at a 6.7% CAGR to 2036. Cross-border e-commerce and livestream selling will carry imported premium brands. Domestic labels will compete on price and local ingredient stories.
Key takeaway: Chinese growth will come from premium spend per child, sold heavily through online platforms.
USA Baby Personal Care Market Outlook (2026 to 2036)
CDC FastStats lists 3,628,934 US births for 2024.[4] The American CAGR is 5.6%. Kimberly-Clark expects to close the Kenvue acquisition in the fourth quarter of 2026.[2] Pharmacy chains and online retailers will push dermatologist-backed and fragrance-free lines.
Key takeaway: A combined owner for Johnson's and Aveeno will reshape US shelf competition.
Germany Baby Personal Care Market Outlook (2026 to 2036)
Births in Germany dropped to the lowest post-war level in 2025.[3] Drugstore chains will remain the main route to German parents. Organic certification and sensitive-skin ranges will carry a 5.3% German CAGR. Drugstore private labels will compete with brands on basic wipes and washes.
Key takeaway: Premium and certified organic ranges sold through drugstores will carry German growth.
UK Baby Personal Care Market Outlook (2026 to 2036)
UK sales rise at a 4.9% CAGR, the lowest of the profiled rates. Births with at least one parent born outside the UK rose to 40.2% in 2025, the ONS said.[1] Diverse family backgrounds will widen demand for hair and skin products for different hair types and skin tones. UK supermarkets will keep the lead in everyday baby toiletries.
Key takeaway: UK brands will grow by serving a more diverse parent base with targeted hair and skin ranges.
Who are the notable companies in the baby personal care market?
Johnson & Johnson, Procter & Gamble, Unilever, Kimberly-Clark, Beiersdorf, Hindustan Unilever Group, Colgate-Palmolive, The Clorox Company, Me n Moms Pvt. Ltd., Weleda AG, Marks & Spencer PLC, Nivea, Himalaya Wellness, Chicco, Mustela, Burt's Bees Baby, Aveeno Baby and Cetaphil Baby are the main companies and brands in baby personal care.
FMI assigns Johnson & Johnson a 20% to 25% share and Procter & Gamble 15% to 20%. Unilever holds 10% to 15%, Kimberly-Clark 8% to 12% and Beiersdorf 5% to 10%. Other companies combine for 25% to 35%. Johnson and Johnson continued a reformulation programme in 2025, removing questionable ingredients from legacy lines.
New entrants are challenging the established order in a changing market for premium baby skin care. Ceuticoz launched Ceuticoz Baby, a seven-SKU paediatric skincare range, in January 2026. R for Rabbit introduced oatmeal and lavender-infused baby lotions and washes the same month. Kenvue, owner of Johnson's and Aveeno, grew Q2 2026 net sales 3% to $3,955 million.[2]
- Share-ranged leaders: Johnson & Johnson, Procter & Gamble, Unilever, Kimberly-Clark, and Beiersdorf.
- Other key industry players: Hindustan Unilever Group, Colgate-Palmolive, The Clorox Company, Me n Moms Pvt. Ltd., Weleda AG, Marks & Spencer PLC, and Nivea.
- Baby-branded lines: Burt's Bees Baby, Aveeno Baby, and Cetaphil Baby.
- Other brands: Himalaya Wellness, Chicco, and Mustela.
Competitive Benchmarking: Baby Personal Care Market
Table 9: Competitive Benchmarking for the Baby Personal Care Market (qualitative documentation ratings), 2026
| Company | Skin Care Focus | Pharmacy Presence | Ownership Change | Disclosure |
|---|---|---|---|---|
| Kenvue (Johnson's, Aveeno) | High | High | High | High |
| Kimberly-Clark | Low | Medium | High | Medium |
| Ceuticoz | High | Low | Low | Low |
| R for Rabbit | Medium | Low | Low | Low |
Marks of High, Medium or Low show the dated company detail behind each column.
Key Developments in the Baby Personal Care Market
- In August 2026, Kenvue reported Baby Care among the growth drivers of Essential Health for Q2.[2]
- In August 2026, Brainbees Solutions put India multi-channel GMV for Q1 FY27 at INR 23,809 million.[8]
- In July 2026, Outlook reported 2,54,73,389 registered births in India for 2024.[7]
- In July 2026, Destatis reported a German total fertility rate of 1.32 for 2025.[3]
- In May 2026, the Office for National Statistics reported 585,396 live births in England and Wales for 2025.[1]
- In February 2026, the Chinese statistics bureau put 2025 births at 7.92 million.[5]
- In January 2026, Kenvue and Kimberly-Clark shareholders approved the merger proposals.[2]
- In July 2025, the National Health Commission reported a childcare subsidy of 3,600 yuan a year for each child under three.[6]
Key Players in the Baby Personal Care Market
Share-Ranged Leaders
- Johnson & Johnson
- Procter & Gamble
- Unilever
- Kimberly-Clark
- Beiersdorf
Other Key Industry Players
- Hindustan Unilever Group
- Colgate-Palmolive
- The Clorox Company
- Me n Moms Pvt. Ltd.
- Weleda AG
- Marks & Spencer PLC
- Nivea
Baby-Branded Lines
- Burt's Bees Baby
- Aveeno Baby
- Cetaphil Baby
Other Brands
- Himalaya Wellness
- Chicco
- Mustela
Baby Personal Care Market - Report Scope
Table 10: Report Scope for the Baby Personal Care Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; nature; age group; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Baby personal care market covering skin care, hair care, toiletries and other personal care products for infants and toddlers, in organic/natural and synthetic formulations. |
| Regions covered | North America; Latin America; Europe; Asia Pacific; Middle East & Africa |
| Countries covered | India; China; USA; Germany; UK |
| Key companies profiled | Johnson and Johnson, Procter and Gamble, Unilever, Beiersdorf, Himalaya Wellness, Chicco, Mustela, Burt's Bees Baby, Aveeno Baby, Cetaphil Baby |
| Forecast period | 2026 to 2036 |
Baby Personal Care Market - Research Methodology
Table 11: Research Methodology for the Baby Personal Care Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | National birth statistics and brand-owner results released from May 2025 onward ground the cited facts. |
| Desk Research | Desk work tracks births, fertility rates, mothers' age, organic growth, price and mix, and ownership changes. |
| Market Sizing and Forecasting | The model runs from USD 6.53 billion in 2025 at a 3.67% CAGR. |
| Data Validation | Birth figures were taken from national statistics offices and civil registration reports. |
Baby Personal Care Market by Segments
Baby Personal Care Market segmented by Product Type:
- Skin Care
- Hair Care
- Toiletries
- Others
Baby Personal Care Market segmented by Nature:
- Organic/Natural
- Synthetic
Baby Personal Care Market segmented by Age Group:
- 0-6 Months
- 6-12 Months
- 12-24 Months
- 25 Months & Above
Baby Personal Care Market segmented by Sales Channel:
- Wholesalers/Distributors
- Specialty Stores
- Supermarkets/Hypermarkets
- Pharmacies/Drug Stores
- Online Stores
- Others
Baby Personal Care Market by Region
- North America
- Latin America
- Europe
- Asia Pacific
- Middle East & Africa
Research Sources and Bibliography
- [1] Office for National Statistics. (2026, May 27). Births in England and Wales: 2025. https://www.ons.gov.uk/peoplepopulationandcommunity/birthsdeathsandmarriages/livebirths/bulletins/birthsummarytablesenglandandwales/2025
- [2] Kenvue Inc. (2026, August 6). Second quarter 2026 earnings press release (Form 8-K exhibit). https://www.sec.gov/Archives/edgar/data/1944048/000194404826000141/q226earningspressrelease.htm
- [3] Federal Statistical Office of Germany (Destatis). (2026, July 1). Total fertility rate drops to 1.32 children per woman in 2025 (Press release No. 230). https://www.destatis.de/EN/Press/2026/07/PE26_230_12.html
- [4] Centers for Disease Control and Prevention, National Center for Health Statistics. (2026, September 29). FastStats, Births and Natality. https://www.cdc.gov/nchs/fastats/births.htm
- [5] National Bureau of Statistics of China. (2026, February 28). Statistical Communiqué of the People's Republic of China on the 2025 National Economic and Social Development. https://www.stats.gov.cn/english/PressRelease/202602/t20260228_1962661.html
- [6] National Health Commission (Xinhua). (2025, July 31). Childcare subsidy to benefit tens of millions of Chinese families, official. https://en.nhc.gov.cn/2025-07/31/c_86502.htm
- [7] Outlook India. (2026, July 14). India Registered Over 2.5 Crore Births In 2024, What The Civil Registration System Report Reveals. https://www.outlookindia.com/national/india-registered-over-25-crore-births-in-2024-what-the-civil-registration-system-report-reveals
- [8] Brainbees Solutions Limited (NSE filing). (2026, August 13). Investor presentation for the quarter ended June 30, 2026. https://nsearchives.nseindia.com/corporate/BRAINBEES_13082026172158_InvestorPresentationJune302026.pdf
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will baby personal care sales total in 2026 and 2036?
- What CAGR will the baby personal care market post from 2026 to 2036?
- Which product type will lead sales?
- How will falling births affect volume and value?
- Which profiled country will grow fastest?
- Which companies will shape competition through 2036?
Frequently Asked Questions
What is the size of the baby personal care market in 2026?
Sales will stand near USD 6.77 billion in 2026, with FMI forecasting USD 9.71 billion for 2036. At what rate will the baby personal care market grow? Value per baby will rise faster than unit volume, carrying a 3.67% CAGR from 2026 to 2036.
Which product type will lead in 2026?
Skin care will lead product type sales, with about 41.8% (estimated). Will falling births shrink the market? Births will keep falling in Germany and the UK. Higher spend per baby will keep sales rising.
Which country will grow fastest?
India will lead growth at a 7.1% CAGR per FMI country data, with China next at 6.7%.
Which companies will matter most in baby personal care?
Johnson & Johnson will keep the top band of 20% to 25%, ahead of Procter & Gamble, Unilever, Kimberly-Clark and Beiersdorf.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Skin Care
- Hair Care
- Toiletries
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Organic/Natural
- Synthetic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Age Group, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Age Group, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Age Group, 2026 to 2036
- 0-6 Months
- 6-12 Months
- 12-24 Months
- 25 Months & Above
- Y-o-Y Growth Trend Analysis By Age Group, 2021 to 2025
- Absolute $ Opportunity Analysis By Age Group, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Wholesalers/Distributors
- Specialty Stores
- Supermarkets/Hypermarkets
- Pharmacies/Drug Stores
- Online Stores
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Asia Pacific
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- India
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By Age Group
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Kenvue (Johnson's, Aveeno)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kimberly-Clark
- Ceuticoz
- R for Rabbit
- Johnson & Johnson
- Procter & Gamble
- Unilever
- Beiersdorf
- Hindustan Unilever Group
- Colgate-Palmolive
- The Clorox Company
- Me n Moms Pvt. Ltd.
- Weleda AG
- Marks & Spencer PLC
- Nivea
- Burt's Bees Baby
- Aveeno Baby
- Cetaphil Baby
- Himalaya Wellness
- Chicco
- Mustela
- Kenvue (Johnson's, Aveeno)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


