
- Market Size (2026)
- USD 9.6 Bn
- Forecast (2036)
- USD 46.1 Bn
- CAGR (2026 to 2036)
- 17.0%
How big is Electric Vehicle Sensor Market in 2026?
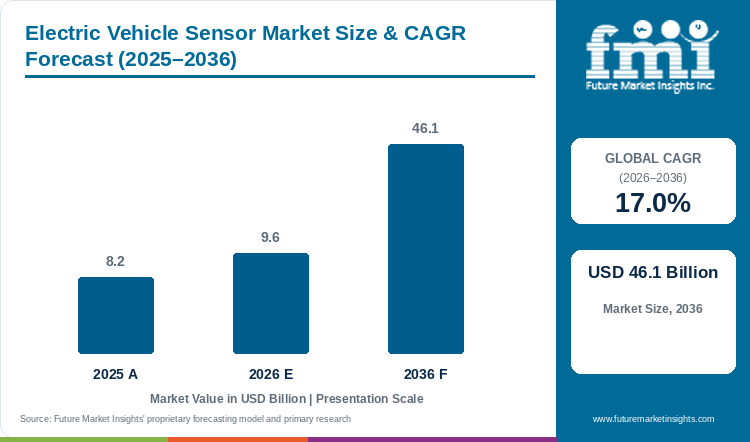
Registering a value of USD 8.2 billion in 2025, the electric vehicle sensor market expanded to USD 9.6 billion in 2026 and is anticipated to achieve USD 46.1 billion by 2036, driven by a 17.0% CAGR.
The global electric vehicle sensor market was valued at USD 8.2 billion in 2025 and is estimated to reach USD 9.6 billion in 2026. The market is projected to reach USD 46.1 billion by 2036, expanding at a compound annual growth rate (CAGR) of 17.0% between 2026 and 2036. Hall-effect and precision shunt current sensors are anticipated to capture a 38.0% share of modality demand in 2026, driven by carmaker adoption of silicon carbide traction inverters and redundant pack-level coulomb counting. Buyer adoption tracking at FMI shows that sensor volume is expanding faster than vehicle production alone, since high-voltage 400V and 800V battery packs multiply current and thermal monitoring points per chassis. This per-vehicle content expansion separates electrified powertrain sensing from the broader automotive sensors market at 8.9% CAGR, given that internal combustion models lack multi-module battery management arrays and three-phase traction motor resolvers. The International Energy Agency reported in May 2026 that global electric car sales rose by 20% in 2025 to exceed 20 million units, which directly expands OEM sensor call-offs. Manufacturers are also investing in digital noise-immune current sensing to handle fast wide-bandgap switching, as seen in June 2026 when Melexis unveiled its MLX91229 Hall current sensor with a sigma-delta digital bitstream covering 200 A to 2,000 A for traction inverters. Suppliers that combine galvanic isolation with sub-microsecond overcurrent detection are positioned to lock in multi-year platform design wins through 2036.
Key Market Trends & Insights
- By sensor modality: Current Sensors Hall-Effect and Shunt for Battery Inverter hold an estimated 38.0% share in 2026 given that every traction phase leg, on-board charger, and battery junction box requires high-accuracy amperage measurement.
- By electrified vehicle subsystem: Battery Management System BMS Monitoring represents 54.0% in 2026 since lithium-ion packs deploy dozens of cell-module temperature thermistors, busbar shunts, and thermal-runaway pressure detectors.
- By vehicle segment: Battery Electric Vehicles BEV account for 78.0% in 2026 driven by large 60 kWh to 120 kWh traction packs that carry three times the sensor count of mild or plug-in hybrid packs.
- By voltage architecture: 400V Standard High-Voltage Platforms secure 64.0% in 2026 owing to high-volume mass-market electric crossovers and sedans standardized on 400V silicon and silicon carbide electronics.
- By sales channel: OEM Factory Fitment commands 91.0% in 2026 through direct integration of sensors inside sealed battery packs, e-axles, and power electronics modules on assembly lines.
Regional Highlights
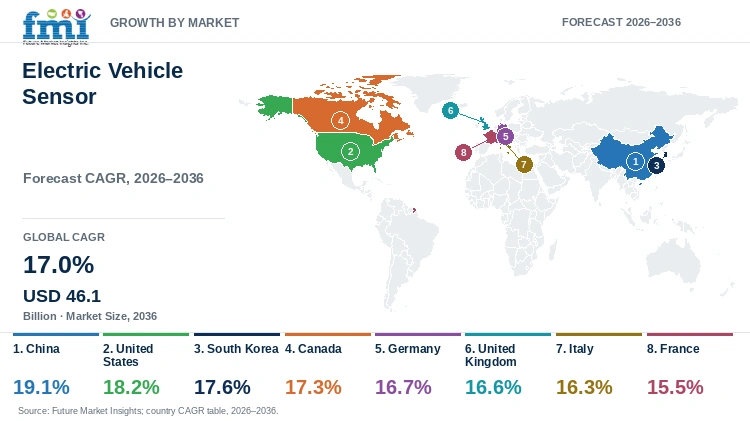
- Top national expansion: China leads national growth projections at a 19.1% CAGR through 2036 supported by high-volume NEV manufacturing and domestic sensor IC localization.
- Broader country progression: The United States tracks at an 18.2% CAGR ahead of South Korea at 17.6% and Canada at 17.3%, while Germany advances at 16.7% and the United Kingdom records a 16.6% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Electric Vehicle Sensor Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 8.2 billion |
| Estimated Market Size in 2026 | USD 9.6 billion |
| Projected Market Size by 2036 | USD 46.1 billion |
| CAGR, 2026 to 2036 | 17.0% |
| Added Revenue, 2026 to 2036 | USD 36.5 billion |
Electrified powertrain engineers designing 400V and 800V propulsion architectures confront severe electromagnetic interference generated by fast-switching silicon carbide MOSFETs inside compact e-axles. When analog voltage signals travel across long wiring harnesses from the inverter to the microcontroller, inductive switching noise corrupts current readings and degrades torque ripple control. In June 2026, automotive drive specialist FINEST selected Melexis IMC-Hall current sensor ICs for its next-generation traction inverters to minimize energy losses and extend real-world driving range for global automotive OEMs. Consequently, tier-one inverter builders are upgrading from unshielded analog sensors to integrated digital Hall-effect current sensors and coreless magnetic IC packages.
Electrified Fleet Production and Per-Vehicle Sensor Content Sizing
Table 2: Electrified Vehicle Production and Sensor Content Sizing for the Electric Vehicle Sensor Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 8.2 | 9.6 | 46.1 |
| Global electric car sales baseline (million units) | 20.2 | 23.0 to 24.5 | 58.0 to 64.0 |
| Average powertrain & BMS sensor nodes per BEV (units) | 38 to 46 | 42 to 52 | 68 to 82 |
| Average EV sensor bill-of-materials per vehicle (USD) | 395 to 415 | 405 to 430 | 720 to 760 |
Operational note: Per-vehicle sensor content ranges apply verified 200 A to 2,000 A traction inverter current sensing specifications from Melexis in June 2026 and internal PT1000 RTD lithium-ion cell temperature deltas of 15 degrees Celsius.
High-voltage battery packs and e-axles require continuous closed-loop monitoring of phase current and rotor angle as well as coolant pressure and cell core temperature to prevent thermal runaway. Automotive tier-one suppliers embed pre-calibrated sensor ASICs directly onto copper busbars and flexible printed circuits.
High-Voltage Subsystem and Thermal Runaway Detection Sizing
Table 3: Subsystem Sensing Nodes and Bill-of-Materials Indicators for the Electric Vehicle Sensor Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Traction inverter current sensing range (Amperes) | 200 to 1,500 | 200 to 2,000 | 300 to 2,500 |
| Cell internal-to-surface fast-charge temp delta (deg C) | 12.0 to 15.0 | 12.0 to 15.0 | 5.0 to 8.0 |
| 800V high-voltage platform share of new EV builds (%) | 14.0% to 17.0% | 18.0% to 22.0% | 52.0% to 58.0% |
| Digital & coreless isolated current sensor share (%) | 34.0% to 38.0% | 39.0% to 44.0% | 71.0% to 76.0% |
Table 4: Electrified Powertrain and Battery Sensor Benchmarks for the Electric Vehicle Sensor Market (values and institutional basis), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 9.6 billion | 2026 global electric vehicle sensor revenue baseline |
| Global electric car sales, 2025 | >20 million units | IEA Global EV Outlook May 2026 (+20% YoY growth) |
| Canadian EV fleet growth, 2025 | +29.6% YoY (6.5% LDV share) | Statistics Canada Sept 2026 vehicle registration release |
| German new car export EV share | 28.1% of exports | Destatis Sept 2026 press release (Jan-Jul 2026 exports) |
Figures published by the International Energy Agency in its 2026 Global Energy Review confirm that electric car sales exceeded 20 million units in 2025 as domestic model competition intensified. In March 2026, Infineon Technologies introduced its ultra-low-noise XENSIV TLE4978 coreless current sensor family to improve power conversion efficiency in electric vehicle on-board chargers and high-voltage DC-DC converters. This rapid scaling of high-voltage power electronics compels tier-one module builders to qualify automotive Grade 0 temperature sensors and reinforced-isolation current sensors across every new vehicle platform.
Analyst Perspective
"Automotive OEMs no longer treat electric vehicle sensors as standalone commodity thermistors or discrete magnetic switches; they procure integrated functional-safety sensing subsystems that deliver 5% to 8% extra driving range from the same battery capacity. Sensor suppliers that combine 800V galvanic isolation with dual Hall-and-shunt redundancy and early thermal-runaway gas detection will capture the longest multi-year platform contracts through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the electric vehicle sensor market segmented?
The electric vehicle sensor market is segmented by sensor modality, electrified vehicle subsystem, vehicle segment, voltage architecture, and sales channel. In 2026, Current Sensors Hall-Effect and Shunt for Battery Inverter are projected at 38.0%, Battery Management System BMS Monitoring at 54.0%, Battery Electric Vehicles BEV at 78.0%, 400V Standard High-Voltage Platforms at 64.0%, and OEM Factory Fitment at 91.0%.
By sensor modality: Current Sensors Hall-Effect and Shunt for Battery Inverter and Temperature Sensors NTC Thermistors for Battery Modules, followed by Position and Angle Sensors Resolvers for Traction Motors and Voltage and Pressure Sensors.
By electrified vehicle subsystem: Battery Management System BMS Monitoring and Traction Inverter and Motor Control Unit, followed by On-Board Charger and DC-DC Converter and Thermal Management and Heat Pump Chiller Subsystem.
By vehicle segment: Battery Electric Vehicles BEV and Plug-In Hybrid Electric Vehicles PHEV, followed by Commercial Electric Buses and Heavy Trucks and Light Electric Commercial Vans.
By voltage architecture: 400V Standard High-Voltage Platforms and 800V Ultra-Fast Charging Platforms, followed by 48V Mild-Hybrid Auxiliary Bus Systems and Multi-Voltage Reconfigurable Packs.
By sales channel: OEM Factory Fitment and Tier-1 Powertrain Module Integration, followed by Authorized Dealership Service Replacement and Independent EV Aftermarket.
Why do Current Sensors Hall-Effect and Shunt for Battery Inverter lead the sensor modality category?
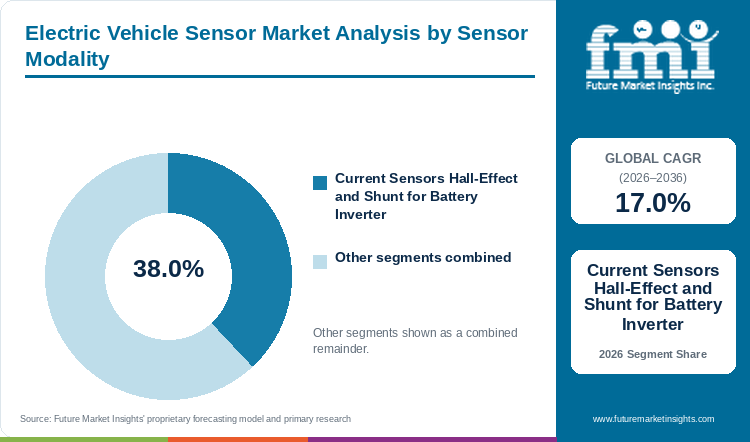
Current Sensors Hall-Effect and Shunt for Battery Inverter hold an estimated 38.0% of sensor modality demand in 2026, anchored by multi-node amperage feedback across inverters, chargers, and battery packs.
Table 5: Sensor Modality Share for the Electric Vehicle Sensor Market (percentage share), 2026
| Sensor Modality | Share (2026) |
|---|---|
| Current Sensors Hall-Effect and Shunt for Battery Inverter | 38.0% |
| Other Segments Combined | 62.0%* |
| Total | 100.0% |
*Note: Remaining sensor modality categories account for the balance of 2026 global electric vehicle sensor demand.
Table 6: Sensor Modality Leadership and Market Growth for the Electric Vehicle Sensor Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 17.0% |
| Leading Segment | Current Sensors Hall-Effect and Shunt for Battery Inverter |
Hall-effect and precision manganin-shunt current sensors lead modality revenue because every electrified vehicle requires multiple high-accuracy current measurement nodes across the battery disconnect unit and three-phase traction inverter as well as the on-board charger. Powertrain architects pair low-drift shunt resistors with open-loop or coreless Hall-effect ICs in smart sensor modules to achieve ASIL-D redundant state-of-charge estimation, even though magnetic cross-talk from adjacent busbars requires careful shielding or differential coreless designs. In September 2025, Melexis enhanced its smart IVT Hall and shunt current sensor platform by integrating an external NTC temperature input so battery engineers can compensate thermal drift on high-voltage busbars with a single IC.
- Within the sensor modality segment, Current Sensors Hall-Effect and Shunt for Battery Inverter are projected to account for a leading 38.0% share in 2026, driven by multi-node amperage monitoring across inverters and battery packs.
- Demand for coreless and digital sigma-delta current sensors is anticipated to accelerate through 2036 as 800V silicon carbide inverters replace legacy silicon IGBT power stages.
What sustains Battery Management System BMS Monitoring leadership in electrified vehicle subsystems?
Battery Management System BMS Monitoring represents 54.0% of the electrified vehicle subsystem category in 2026, supported by cell-module temperature arrays, current shunts, and thermal-runaway detectors.
Battery Management System BMS Monitoring captures the majority of subsystem expenditure given that a single high-voltage lithium-ion pack integrates dozens of NTC temperature thermistors and redundant pack-level current sensors along with venting pressure detectors. Pack engineers are moving from external surface thermistors toward flexible printed circuit microsensors and wireless battery monitoring systems to detect internal cell short circuits seconds earlier, whereas harness weight and connector pin counts remain a constant packaging hurdle in cell-to-pack designs.
- In 2026, Battery Management System BMS Monitoring is anticipated to capture 54.0% of electrified vehicle subsystem demand, reflecting strict UN GTR No. 20 thermal runaway early-warning mandates.
- Supplier product roadmaps reflect this safety focus, with LEM Holding supplying dedicated automotive BMS current sensors that combine shunt and open-loop Hall technologies for exact coulomb counting and overcurrent cut-off.
How do Battery Electric Vehicles BEV lead the vehicle segment?
Battery Electric Vehicles BEV account for 78.0% of vehicle segment demand in 2026, driven by large multi-module traction packs and dual-motor e-axle configurations.
Pure battery electric passenger cars represent the primary volume and value driver for EV sensors owing to the complete absence of a combustion engine, which forces the traction battery and heat-pump thermal loop to handle all propulsion and cabin climate loads. A dedicated BEV platform carries two to three times the high-voltage sensor bill of materials of a plug-in hybrid and pulls forward demand for EV traction inverters and dual-motor all-wheel-drive resolvers, although upfront battery pack costs still challenge entry-level compact car pricing. In July 2026, researchers on arXiv demonstrated that model-predictive thermal management using real-time battery temperature and state-of-charge sensor vectors significantly reduces auxiliary electrical energy consumption across WLTC driving cycles.
- By vehicle segment, demand from Battery Electric Vehicles BEV is estimated to reach 78.0% of total category share in 2026 as global automakers scale dedicated skateboard EV architectures.
- Dual-motor BEV crossovers and electric pickup trucks are forecast to lift average sensor counts per vehicle further between 2026 and 2036.
Why do 400V Standard High-Voltage Platforms lead the voltage architecture category?
400V Standard High-Voltage Platforms secure 64.0% of voltage architecture value in 2026, supported by high-volume passenger EV platforms and reconfigurable 400V/800V charging hardware.
Mass-market electric sedans and fleet delivery vans remain overwhelmingly standardized on 400V nominal battery architectures given that 400V contactors and sensor creepage distances use mature cost-optimized semiconductor packaging. While premium flagships are migrating toward 800V architectures for ultra-fast charging, component suppliers are bridging the gap with reconfigurable switching and sensing hardware for BEV on-board chargers, even as 800V systems require wider dielectric isolation barriers.
- Strong production volumes across mainstream C-segment and D-segment electric cars place 400V Standard High-Voltage Platforms on course to hold an estimated 64.0% share of the voltage architecture category in 2026.
- Component innovation is smoothing the transition between voltage classes, evidenced in July 2025 when Sensata Technologies launched its High Efficiency Contactor to allow 800V battery packs to reconfigure and charge safely at 400V stations while cutting component counts by over 50%.
What gives OEM Factory Fitment the leading position in sales channel?
OEM Factory Fitment commands 91.0% of sales channel share in 2026, anchored by direct line integration inside sealed battery enclosures and oil-cooled traction motors.
Direct OEM and tier-one factory installation accounts for nearly all electric vehicle sensor revenue considering that current shunts, resolver stators, and cell-monitoring thermistors are permanently welded or potted inside sealed battery enclosures and oil-cooled e-axles during assembly. Independent repair garages rarely replace individual internal battery sensors due to high-voltage arc-flash hazards and warranty seals, whereas OEMs lock in single-source sensor specifications for five-to-seven-year vehicle platform lifecycles. In September 2026, TE Connectivity highlighted that its automotive eddy-current resolvers and passive/active Hall current sensors are engineered for automated robotic assembly directly inside OEM e-motors and battery disconnect units.
- OEM Factory Fitment is predicted to secure 91.0% of sales channel demand in 2026, supported by multi-year OEM platform awards and hermetically sealed battery pack manufacturing.
- Authorized dealership replacement of external coolant-loop pressure sensors and wheel-speed sensors will generate a modest aftermarket stream as the global EV car parc ages past eight years.
What are the drivers, restraints, and opportunities in the electric vehicle sensor market?
In the electric vehicle sensor market, 800V SiC inverter adoption and battery thermal-runaway mandates are projected to drive growth whereas high-frequency EMI noise and internal cell thermal lag restrain legacy sensors and integrated heat-pump and wireless BMS sensors unlock new opportunities.
- Driver: Stricter battery thermal-runaway safety rules and rapid adoption of silicon carbide traction inverters compel automakers to install multi-parameter gas and pressure detectors as well as digital current sensors.
- Restraint: Severe electromagnetic interference in 800V fast-switching powertrains and harsh thermal cycling inside oil-cooled motors create signal drift risks and extend AEC-Q100 qualification timelines.
- Opportunity: Combining pressure and temperature transducers for heat-pump chillers and deploying ultra-wideband wireless BMS sensing enable weight savings and assembly automation for next-generation EVs.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Mandatory battery safety regulations and lifecycle traceability laws are compelling automakers to expand sensor density across every high-voltage battery pack and e-drive module. Rather than relying solely on slow surface thermistors, engineering teams are adding cell-venting pressure sensors and hydrogen gas detectors plus high-frequency busbar current monitors to catch internal cell anomalies before thermal runaway initiates. Regulatory momentum is accelerating this hardware upgrade, as confirmed in November 2026 when Bosch showcased its electrified powertrain control units and Digital Battery Passport lifecycle tracking solutions ahead of mandatory European battery passport enforcement in February 2027. Concurrently, thermal optimization across EV thermal systems requires additional refrigerant pressure and coolant temperature loops.
Risk Assessment of the Electric Vehicle Sensor Market: Operational and Formulation Friction
Tight enclosure space constraints, wiring harness complexity, and thermal lag between internal lithium-ion jelly rolls and external cell casings represent the primary technical hurdles restraining conventional discrete sensors. When battery packs undergo 2C or 3C fast charging, external surface-mounted NTC thermistors can lag internal cell core temperatures by up to 15 degrees Celsius, risking lithium plating or delayed fault intervention. A technical assessment published by the U.S. DOE Office of Scientific and Technical Information in April 2025 highlighted that standard BMS voltage and surface temperature sensors face cyber-physical and thermal lag vulnerabilities during fast charging unless paired with coordinated thermal safety monitoring. Automakers consequently demand tighter sensor accuracy tolerances within plus or minus 0.5 degrees Celsius and cryptographic signal authentication.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Sensor manufacturers capture higher content value per vehicle by combining multiple physical sensing elements into a single automotive connector housing for heat pumps, battery packs, and EV coolants distribution manifolds. Consolidation of pressure and temperature dies into one screw-in or clip-on sensor halves wiring harness terminations and speeds up automated pack assembly. In April 2025, TDK showcased its integrated pressure-temperature sensors designed specifically to lower component counts in electric vehicle heat pumps and busbar temperature sensors for high-voltage e-motors. Similarly, Melexis demonstrated its Triphibian pressure sensors and hydrogen battery anomaly detection sensors at electronica in September 2026 to protect high-voltage packs and thermal loops.
Electric Vehicle Sensor Market by Country (2026 to 2036)
FMI country modeling indicates that China leads electric vehicle sensor expansion at a 19.1% CAGR through 2036, while France advances at a 15.5% CAGR. National sensor procurement across East Asian battery gigafactories, North American electric truck plants, and European e-axle assembly lines hinges on domestic semiconductor localization and zero-emission vehicle mandates.
Table 7: Country CAGR and Primary Growth Levers for the Electric Vehicle Sensor Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 19.1% | Domestic NEV volume scale, cell-to-pack BMS arrays, and local sensor IC wafer fabs |
| United States | 18.2% | Domestic battery belt gigafactories and high-amperage electric pickup/SUV packs |
| South Korea | 17.6% | 800V E-GMP architectures and flexible-circuit RTD cell sensor exports |
| Canada | 17.3% | Ontario EV/battery assembly plants and cold-climate heat-pump thermal sensing |
| Germany | 16.7% | 28.1% EV export share and domestic tier-one SiC inverter and e-axle production |
| United Kingdom | 16.6% | ZEV sales mandate, 25% BEV registration share, and high-density e-motor engineering |
| Italy | 16.3% | Compact urban EV retooling and Motor Valley high-RPM SiC inverter resolvers |
| France | 15.5% | ElectriCity northern EV manufacturing hub and 21.4% BEV share of car output |
Source: Future Market Insights analysis
China Electric Vehicle Sensor Market Outlook (2026 to 2036)
Demand for electric vehicle sensors in China is projected to expand at a world-leading 19.1% CAGR between 2026 and 2036 as domestic NEV automakers and battery cell giants scale cell-to-pack and 800V fast-charging platforms. What distinguishes China from Western automotive markets is the vertical integration of domestic battery makers and carmakers coupled with aggressive localization of automotive-grade mixed-signal sensor fabrication. Active semiconductor localization confirms this shift, as seen on September 15, 2026 when Melexis completed local Chinese production of its first integrated current sensor IC to serve domestic EV battery and inverter customers. High-volume domestic production of LFP and NMC battery packs keeps China as the largest global buyer of shunt, Hall-effect, and NTC thermistor arrays.
Key takeaway: In China, massive NEV production scale and full local wafer fabrication of current sensor ICs are projected to drive global-leading EV sensor growth.
United States Electric Vehicle Sensor Market Outlook (2026 to 2036)
In the United States, electric vehicle sensor sales are anticipated to advance at an 18.2% CAGR through 2036, anchored by domestic battery belt gigafactories and high-capacity electric pickup truck and SUV platforms. Compared with European and Asian fleets dominated by compact sedans, American EVs feature large 90 kWh to 200 kWh battery packs and dual-motor towing powertrains that require higher-amperage contactors and busbar current sensors. Data from the U.S. Department of Energy Alternative Fuels Data Center updated in February 2026 confirms that light-duty electric vehicle registrations across American states continued their multi-year structural expansion through 2025. Furthermore, Sensata Technologies won the Gold Merit Award in January 2026 for its High Efficiency Contactor and high-voltage battery protection technology engineered for North American and global EVs.
Key takeaway: In the United States, large-pack electric trucks and domestic battery gigafactories are anticipated to sustain rapid demand for high-amperage current and thermal sensors.
South Korea Electric Vehicle Sensor Market Outlook (2026 to 2036)
South Korean demand for electric vehicle sensors is forecast to grow at a 17.6% CAGR from 2026 to 2036, driven by 800V E-GMP and next-generation passenger EV platforms as well as global battery cell exports from domestic conglomerates. What sets South Korea apart is its leadership in high-nickel prismatic and pouch battery modules that integrate flexible printed circuit RTD microsensors and precision cell-monitoring harnesses. Research published in the journal Sensors in January 2025 demonstrated that integrating a PT1000 RTD microsensor directly onto a flexible printed circuit anode current collector detects internal battery short-circuit temperature spikes to 32 degrees Celsius within 20 seconds while retaining 89.8% capacity under 2C fast charging. Korean tier-one electronics suppliers export these integrated cell-sensing assemblies to assembly plants across major automotive regions.
Key takeaway: In South Korea, 800V vehicle platforms and advanced flexible-circuit battery cell sensors are forecast to propel high-value sensor adoption.
Canada Electric Vehicle Sensor Market Outlook (2026 to 2036)
Procurement in the Canadian electric vehicle sensor market is projected to rise at a 17.3% CAGR between 2026 and 2036, supported by Ontario battery and vehicle assembly investments and cold-climate battery thermal management requirements. Sub-zero winter operating conditions across Canada compel automakers to equip battery packs and heat-pump chillers with redundant coolant temperature and pressure sensors to prevent cold-weather range loss. Official figures released by Statistics Canada on September 22, 2026 show that total EV registrations in Canada rose 29.6% in 2025 to account for 6.5% of light-duty vehicles with 623,481 BEVs and 772,562 HEVs, while medium-duty BEV registrations more than quadrupled to 4,368 units. Canadian assembly plants and tier-one suppliers consequently procure ruggedized automotive MEMS sensors and cold-rated battery harnesses.
Key takeaway: In Canada, rising light-duty and medium-duty EV registrations and sub-zero battery heating requirements are projected to drive strong sensor procurement.
Germany Electric Vehicle Sensor Market Outlook (2026 to 2036)
Germany's electric vehicle sensor demand is estimated to progress at a 16.7% CAGR through 2036 across domestic premium EV assembly plants in Bavaria, Lower Saxony, and Saxony as well as tier-one e-axle factories. While domestic German car registrations fluctuate with subsidy adjustments, German factories remain Europe's primary export powerhouse for high-voltage electric passenger cars and Silicon Carbide traction inverters. Figures released by the Federal Statistical Office of Germany (Destatis) in September 2026 show that electric cars accounted for 28.1% of all new passenger cars exported from Germany during the first seven months of 2026. German tier-one suppliers including Bosch and Infineon work closely with domestic OEMs to qualify ASIL-D rotor resolvers and coreless current sensors.
Key takeaway: In Germany, high export shares of electric passenger cars and domestic tier-one e-axle production are estimated to anchor precision sensor demand.
United Kingdom Electric Vehicle Sensor Market Outlook (2026 to 2036)
Zero-emission vehicle sales mandates and regional charging infrastructure rollouts in the United Kingdom are reshaping domestic OEM and commercial fleet sensor demand. FMI country modeling indicates that market growth in the United Kingdom is slated to track at a 16.6% CAGR over the 2026 to 2036 forecast period, supported by domestic electric van and luxury EV manufacturing. Registration statistics cited by North Northamptonshire Council in January 2026 show that battery electric vehicles captured one in four (25%) new UK car registrations in June 2025, up from one in five a year earlier. British powertrain engineering centers and motorsport-derived EV integrators specify high-bandwidth current and resolver sensors for compact high-power-density drive units.
Key takeaway: In the United Kingdom, rising BEV registration shares and high-power-density e-motor engineering are slated to sustain strong sensor adoption.
Italy Electric Vehicle Sensor Market Outlook (2026 to 2036)
Sales of electric vehicle sensors in Italy are predicted to advance at a 16.3% CAGR between 2026 and 2036 as national assembly plants retool for compact urban electric cars, commercial delivery vans, and high-performance electric sports cars. What differentiates Italy within Western Europe is its combination of high-volume city-car electrification in Turin and Melfi plus ultra-high-revving traction motors and Silicon Carbide inverters in Emilia-Romagna's Motor Valley. In May 2025, DENSO highlighted its ELEXCORE electrification portfolio of compact traction inverters and integrated current and temperature sensors designed to maximize efficiency across passenger and commercial electric vehicles. Italian tier-one component makers integrate these compact resolvers and thermal sensors into transaxle housings.
Key takeaway: In Italy, urban electric car retooling and high-performance Motor Valley e-axle engineering are predicted to support steady sensor growth.
France Electric Vehicle Sensor Market Outlook (2026 to 2036)
France's electric vehicle sensor market is likely to increase at a 15.5% CAGR from 2026 to 2036, supported by Northern France's ElectriCity manufacturing cluster and social-leasing EV incentives. Compared with export-heavy luxury EV production in neighboring Germany, French factories concentrate on compact B-segment and C-segment battery electric hatchbacks where sensor cost integration and automated module assembly are decisive. Production statistics from France's National Institute of Statistics and Economic Studies (INSEE) in March 2026 confirm that electric vehicles rose from 13.6% of French passenger car output in 2021 to 21.4% in 2025, peaking at 65% for all electrified cars in Q4 2025. French OEMs and tier-one battery pack assemblers rely on integrated cell-sensing interconnects from suppliers such as Amphenol.
Key takeaway: In France, expanding domestic electric car production shares in northern industrial clusters are likely to sustain high-volume OEM sensor contracts.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the electric vehicle sensor market?
Sensata Technologies, Inc., LEM Holding SA, DENSO Corporation, Melexis NV, Robert Bosch GmbH, Amphenol Corporation, TE Connectivity Ltd., Infineon Technologies AG, TDK Corporation, and NXP Semiconductors N.V. are the notable companies in the electric vehicle sensor market.
Competitive positioning across the electric vehicle sensor sector separates mixed-signal magnetic and current sensor IC specialists, diversified automotive tier-one system suppliers, and high-voltage interconnect and thermistor leaders. Melexis NV and Infineon Technologies AG engineer Hall-effect and coreless current sensor ICs while LEM Holding SA supplies integrated battery current transducers. Sensata Technologies Inc. and Robert Bosch GmbH supply high-voltage contactors and powertrain control modules while DENSO Corporation manufactures e-axle inverters and thermal sensors. TE Connectivity Ltd. and Amphenol Corporation provide motor resolvers and cell-sensing harnesses while TDK Corporation supplies NTC thermistors.
- Magnetic, Hall-Effect and Current Sensor Specialists: Melexis NV and Infineon Technologies AG plus LEM Holding SA design automotive-qualified Hall-effect and shunt current sensors for traction inverters and battery management systems.
- Diversified Automotive Tier-1 Sensing and Protection Leaders: Sensata Technologies Inc. and Robert Bosch GmbH plus DENSO Corporation manufacture high-voltage contactors and battery pressure-temperature sensors along with e-drive control modules.
- High-Voltage Interconnect, Resolver and Thermistor Suppliers: TE Connectivity Ltd. and Amphenol Corporation plus TDK Corporation supply eddy-current motor resolvers, busbar NTC thermistors, and cell-to-cell BMS sensing harnesses.
Competitive Benchmarking: Electric Vehicle Sensor Market
Table 8: Competitive Benchmarking for the Electric Vehicle Sensor Market (qualitative capability ratings), 2026
| Company | High-Voltage Current & Isolation Accuracy | BMS Thermal & Runaway Detection | OEM E-Axle & Inverter Integration | Geographic Reach |
|---|---|---|---|---|
| Sensata Technologies, Inc. | High | High | High | Global automotive network; won Jan 2026 Gold Merit Award for 400V/800V HEC contactor |
| LEM Holding SA | High | Medium | High | Europe, Asia, and Americas automotive BMS and traction current sensor production |
| DENSO Corporation | High | High | High | Global OEM tier-one supplier of ELEXCORE inverters and integrated powertrain sensors |
| Melexis NV | High | High | High | Launched MLX91229 digital current sensor in June 2026; localized China IC fab in Sept 2026 |
| Robert Bosch GmbH | High | High | High | Global e-axle, BMS, and Digital Battery Passport sensor and control unit leader |
| Amphenol Corporation | Medium | High | High | Global high-voltage battery cell-sensing harnesses, NTC thermistors, and connectors |
| TE Connectivity Ltd. | High | High | High | Global e-mobility eddy-current resolvers, Hall current sensors, and BCON+ battery systems |
| Infineon Technologies AG | High | Medium | High | Global automotive semiconductor leader; launched XENSIV TLE4978 current sensor in March 2026 |
| TDK Corporation | Medium | High | High | Global supplier of screw-on busbar NTC thermistors and integrated heat-pump P/T sensors |
| NXP Semiconductors N.V. | Medium | High | High | Global automotive BMS analog front-end ICs and Trimension UWB wireless BMS chipsets |
Evaluation basis: High-Voltage Current & Isolation Accuracy rates documented capability in 400V/800V galvanic isolation, coreless magnetic sensing, or sigma-delta noise immunity. BMS Thermal & Runaway Detection measures cell-level NTC or gas anomaly sensing, while OEM E-Axle & Inverter Integration evaluates direct tier-one design-ins across global EV platforms.
Key Developments in the Electric Vehicle Sensor Market
- Robert Bosch GmbH showcased its electrified powertrain control units and Digital Battery Passport software and sensor solutions at EICMA on November 3, 2026 ahead of mandatory European battery passport regulations in February 2027.
- Melexis NV shipped its first China-fabricated current sensor IC from its local supply chain on September 15, 2026 and introduced the MLX91229 digital-output current sensor for high-power EV traction inverters on June 25, 2026.
- Infineon Technologies AG introduced the ultra-low-noise XENSIV TLE4978 coreless Hall current sensor family on March 16, 2026, providing AEC-Q100 Grade 0 qualification for electric vehicle on-board chargers and DC-DC converters.
Key Players in the Electric Vehicle Sensor Market
Magnetic, Hall-Effect and Current Sensor Specialists
- Melexis NV
- Infineon Technologies AG
- LEM Holding SA
- Diversified Automotive Tier-1 Sensing and Protection Leaders
Sensata Technologies, Inc.
- Robert Bosch GmbH
- DENSO Corporation
- High-Voltage Interconnect, Resolver and Thermistor Suppliers
- TE Connectivity Ltd.
Amphenol Corporation
- TDK Corporation
- NXP Semiconductors N.V.
Electric Vehicle Sensor Market - Report Scope
Table 9: Report Scope for the Electric Vehicle Sensor Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Sensor Modality; Electrified Vehicle Subsystem; Vehicle Segment; Voltage Architecture; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from sensors dedicated to electrified vehicle propulsion and energy management (Hall-effect, shunt, and fluxgate current sensors; battery and e-motor NTC/RTD temperature sensors; traction motor resolvers and inductive position sensors; high-voltage isolation voltage sensors; and battery venting/coolant pressure and gas sensors). Category Scope Note: Excludes exterior ADAS radar, lidar, ultrasonic parking, and legacy internal-combustion exhaust sensors. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | China, United States, South Korea, Canada, Germany, United Kingdom, Italy, France, and additional countries in the full report |
| Key Companies Covered | Sensata Technologies, Inc., LEM Holding SA, DENSO Corporation, Melexis NV, Robert Bosch GmbH, Amphenol Corporation, TE Connectivity Ltd., Infineon Technologies AG, TDK Corporation, NXP Semiconductors N.V. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Electric Vehicle Sensor Market - Research Methodology
Table 10: Research Methodology for the Electric Vehicle Sensor Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with automotive OEM battery management architects, tier-one SiC inverter hardware directors, and automotive semiconductor product line managers to validate per-vehicle sensor counts and ASIL-D pricing. |
| Secondary Research | Analysis of IEA Global EV Outlook 2026 datasets, Statistics Canada, Destatis, and INSEE national vehicle registration/production bulletins, DOE OSTI battery safety studies, and corporate product disclosures. |
| Market Sizing and Forecasting | Top-down global electrified vehicle production baselines reconciled against bottom-up sensor nodes per BEV/PHEV (42 to 52 nodes per BEV in 2026) and modality-specific ASP curves from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight domestic BEV/PHEV assembly output, gigafactory cell-to-pack capacity additions, 800V platform share, and thermal-runaway safety regulations across eight countries. |
| Operational Benchmark Traceability | Powertrain and BMS sensing indicators in Tables 2, 3, and 4 trace to IEA 20M+ EV sales records, Melexis 200-2,000 A digital current specs, Infineon TLE4978 Grade 0 specs, and MDPI PT1000 RTD thermal testing. |
| Data Triangulation and Validation | Revenue estimates isolate high-voltage battery, inverter, e-motor, charger, and EV thermal management sensors while strictly excluding non-propulsion cabin comfort, TPMS, and ADAS perception sensors. |
Electric Vehicle Sensor Market by Segments
Electric Vehicle Sensor Market segmented by Sensor Modality:
- Current Sensors Hall-Effect and Shunt for Battery Inverter
- Temperature Sensors NTC Thermistors for Battery Modules
- Position and Angle Sensors Resolvers for Traction Motors
- Voltage Sensors High-Voltage Monitoring
Electric Vehicle Sensor Market segmented by Electrified Vehicle Subsystem:
- Battery Management System BMS Monitoring
- Traction Inverter and Motor Control Unit
- On-Board Charger and DC-DC Converter
- Thermal Management and Heat Pump Chiller Subsystem
Electric Vehicle Sensor Market segmented by Vehicle Segment:
- Battery Electric Vehicles BEV
- Plug-In Hybrid Electric Vehicles PHEV
- Commercial Electric Buses and Heavy Trucks
- Light Electric Commercial Vans
- Two-Wheeler and Micro-Mobility EVs
Electric Vehicle Sensor Market segmented by Voltage Architecture:
- 400V Standard High-Voltage Platforms
- 800V Ultra-Fast Charging Platforms
- 48V Mild-Hybrid Auxiliary Bus Systems
- Multi-Voltage Reconfigurable Packs
Electric Vehicle Sensor Market segmented by Sales Channel:
- OEM Factory Fitment
- Tier-1 Powertrain Module Integration
- Authorized Dealership Service Replacement
- Independent EV Aftermarket
Electric Vehicle Sensor Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Energy Agency. (2026, May 20). Trends in electric cars: Global EV Outlook 2026. IEA Publications.
- [2] International Energy Agency. (2026, March 15). Technology: Electric vehicles in Global Energy Review 2026. IEA Publications.
- [3] Melexis NV. (2026, June 25). Melexis tackles signal integrity challenges in high-power EVs with MLX91229 digital current sensor. Melexis Corporate Newsroom.
- [4] Melexis NV. (2026, June 11). FINEST integrates Melexis IMC-Hall current sensors in high-performance inverters for next-gen EV platforms. Melexis Corporate Newsroom.
- [5] Melexis NV. (2026, September 3). Melexis presents high-voltage battery safety and Triphibian pressure sensing at electronica 2026. Melexis Corporate Newsroom.
- [6] Melexis NV. (2026, September 15). Melexis delivers on China localization initiative with locally manufactured current sensor IC. Melexis Corporate Newsroom.
- [7] Melexis NV. (2025, September 18). Melexis enhances smart IVT Hall and shunt sensors with external NTC temperature input. Melexis Corporate Newsroom.
- [8] Sensata Technologies, Inc. (2026, January 8). Sensata Technologies High Efficiency Contactor wins Gold 2025 Merit Award for Battery Charging Technology. Sensata Newsroom.
- [9] Sensata Technologies, Inc. (2025, July 17). Sensata Technologies launches High Efficiency Contactor to enable 400V and 800V EV charging compatibility. Sensata Newsroom.
- [10] Infineon Technologies AG. (2026, March 16). Infineon introduces ultra-low noise XENSIV TLE4978 coreless current sensor for EV chargers and DC-DC converters. Infineon Technology News.
- [11] Robert Bosch GmbH. (2026, November 3). EICMA 2026: Bosch showcases electrified powertrain control units and Digital Battery Passport solutions. Bosch Media Service.
- [12] TDK Corporation. (2025, April 28). TDK showcases integrated heat-pump pressure-temperature sensors and e-motor sensor solutions. TDK Press Center.
- [13] TE Connectivity Ltd. (2026, September 10). TE Connectivity E-mobility Eddy Current Resolvers and Hall Current Sensors for Automotive and Commercial Vehicles. TE Connectivity Automotive Resources.
- [14] LEM Holding SA. (2025, June 12). Battery Management System Current Sensing Solutions for Electric Vehicles. LEM Automotive Portal.
- [15] DENSO Corporation. (2025, May 15). Powertrain Systems for Battery Electric Vehicles: Inverters and Current-Temperature Sensing. DENSO Global Products.
- [16] Amphenol Corporation. (2025, August 14). High-Voltage Battery Connectors and Cell-Sensing Interconnects for Electrified Vehicles. Amphenol Product Documentation.
- [17] Statistics Canada. (2026, September 22). The Daily: Vehicle registrations in Canada, 2025 and Q2 2026 ZEV assembly trends. Government of Canada Statistics Canada.
- [18] Federal Statistical Office of Germany (Destatis). (2026, September 21). Press Release PE26_332_51: Electric cars account for 28.1% of German new passenger car exports in first seven months of 2026. Destatis Press Portal.
- [19] National Institute of Statistics and Economic Studies (INSEE). (2026, March 24). In the automotive industry, the ramping up of electric vehicle production in France. INSEE Conjoncture in France.
- [20] U.S. Department of Energy Alternative Fuels Data Center. (2026, February 15). Light-Duty Electric Vehicle Registrations and Powertrain Data across the United States. U.S. Department of Energy AFDC.
- [21] U.S. Department of Energy Office of Scientific and Technical Information. (2025, April 15). Coordinated Thermal Safety Monitoring and Defense on EV Battery Management Systems. DOE OSTI Technical Report 2569916.
- [22] North Northamptonshire Council & UK SMMT Data. (2026, January 19). UK Battery Electric Vehicle Registration Share and LEVI Charging Infrastructure Rollout. GOV.UK Local Transport News.
- [23] Chen, Y., et al. (2025, January 17). Internal Integrated PT1000 RTD Temperature Sensor for Lithium-Ion Traction Batteries. Sensors, 25(2), 511 (MDPI Open Access).
- [24] Amini, M., et al. (2026, July 20). Thermal Management Optimization of Battery Electric Vehicles via Multi-Point Sensor Feedback. arXiv Preprint arXiv:2607.17892.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the electric vehicle sensor market in 2026 and what is forecast for 2036?
- Which 800V silicon carbide inverter and battery thermal-runaway mandates drive EV sensor demand?
- Why do Current Sensors Hall-Effect and Shunt for Battery Inverter lead the sensor modality category?
- Why does Battery Management System BMS Monitoring lead electrified vehicle subsystem demand?
- How do growth rates differ between China and the United States or Germany and France?
- Which leading companies supply magnetic current sensor ICs versus integrated high-voltage contactors and resolvers?
- What electromagnetic interference and thermal lag challenges affect EV battery and inverter sensors?
- What should automotive OEMs evaluate before qualifying digital current and multi-parameter BMS sensors?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Sensor Modality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sensor Modality, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sensor Modality, 2026 to 2036
- Current Sensors Hall-Effect and Shunt for Battery Inverter
- Temperature Sensors NTC Thermistors for Battery Modules
- Position and Angle Sensors Resolvers for Traction Motors
- Voltage Sensors High-Voltage Monitoring
- Y-o-Y Growth Trend Analysis By Sensor Modality, 2021 to 2025
- Absolute $ Opportunity Analysis By Sensor Modality, 2026 to 2036
- Global Market Analysis and Forecast, By Electrified Vehicle Subsystem, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Electrified Vehicle Subsystem, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Electrified Vehicle Subsystem, 2026 to 2036
- Battery Management System BMS Monitoring
- Traction Inverter and Motor Control Unit
- On-Board Charger and DC-DC Converter
- Thermal Management and Heat Pump Chiller Subsystem
- Y-o-Y Growth Trend Analysis By Electrified Vehicle Subsystem, 2021 to 2025
- Absolute $ Opportunity Analysis By Electrified Vehicle Subsystem, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Segment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Segment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Segment, 2026 to 2036
- Battery Electric Vehicles BEV
- Plug-In Hybrid Electric Vehicles PHEV
- Commercial Electric Buses and Heavy Trucks
- Light Electric Commercial Vans
- Two-Wheeler and Micro-Mobility EVs
- Y-o-Y Growth Trend Analysis By Vehicle Segment, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Segment, 2026 to 2036
- Global Market Analysis and Forecast, By Voltage Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Voltage Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Voltage Architecture, 2026 to 2036
- 400V Standard High-Voltage Platforms
- 800V Ultra-Fast Charging Platforms
- 48V Mild-Hybrid Auxiliary Bus Systems
- Multi-Voltage Reconfigurable Packs
- Y-o-Y Growth Trend Analysis By Voltage Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Voltage Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM Factory Fitment
- Tier-1 Powertrain Module Integration
- Authorized Dealership Service Replacement
- Independent EV Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Sensor Modality
- By Electrified Vehicle Subsystem
- By Vehicle Segment
- By Voltage Architecture
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Sensata Technologies, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- LEM Holding SA
- DENSO Corporation
- Melexis NV
- Robert Bosch GmbH
- Amphenol Corporation
- TE Connectivity Ltd.
- Infineon Technologies AG
- TDK Corporation
- NXP Semiconductors N.V.
- Diversified Automotive Tier-1 Sensing and Protection Leaders
- High-Voltage Interconnect, Resolver and Thermistor Suppliers
- Sensata Technologies, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Sensor Modality, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Electrified Vehicle Subsystem, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Segment, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Voltage Architecture, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Sensor Modality
- Figure 6: Global Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 9: Global Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Vehicle Segment
- Figure 12: Global Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Voltage Architecture
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Sensor Modality
- Figure 32: North America Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 35: North America Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Vehicle Segment
- Figure 38: North America Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Voltage Architecture
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Sensor Modality
- Figure 48: Latin America Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 51: Latin America Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Vehicle Segment
- Figure 54: Latin America Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Voltage Architecture
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Sensor Modality
- Figure 64: Western Europe Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 67: Western Europe Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Vehicle Segment
- Figure 70: Western Europe Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Voltage Architecture
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Sensor Modality
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Vehicle Segment
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Voltage Architecture
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Sensor Modality
- Figure 96: East Asia Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 99: East Asia Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Vehicle Segment
- Figure 102: East Asia Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Voltage Architecture
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Sensor Modality
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Vehicle Segment
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Voltage Architecture
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Sensor Modality, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Sensor Modality, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Sensor Modality
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Electrified Vehicle Subsystem, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Electrified Vehicle Subsystem, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Electrified Vehicle Subsystem
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Segment, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Segment, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Vehicle Segment
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Voltage Architecture, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Voltage Architecture, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Voltage Architecture
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the electric vehicle sensor market in 2026, and what is forecast for 2036?
FMI estimates that global EV sensor demand stood at USD 8.2 billion in 2025 and reached USD 9.6 billion in 2026. Overall industry valuation is on track to hit USD 46.1 billion by 2036 as automakers scale 400V and 800V electric powertrains.
What is the CAGR for the electric vehicle sensor market from 2026 to 2036?
The electric vehicle sensor sector is forecast to grow at a 17.0% CAGR over the 2026 to 2036 window, adding USD 36.5 billion in revenue across battery and inverter subsystems.
Which sensor modality segment leads the electric vehicle sensor market?
Current Sensors Hall-Effect and Shunt for Battery Inverter hold an estimated 38.0% share of modality demand in 2026 given that traction inverters, chargers, and battery junction boxes require closed-loop current feedback.
Which subsystem segment leads the electric vehicle sensor market?
Battery Management System BMS Monitoring represents 54.0% of the subsystem category in 2026 as high-voltage packs integrate dozens of cell temperature thermistors, current shunts, and thermal-runaway pressure detectors.
Which country has a notable growth outlook during the assessment period?
China leads national expansion projections at a 19.1% CAGR through 2036, followed closely by the United States at 18.2% and South Korea at 17.6%.
Who are the key players in the market?
Sensata Technologies and LEM Holding lead high-voltage battery sensing while Melexis and Infineon Technologies supply magnetic current sensor ICs. Robert Bosch and DENSO deliver integrated e-drive modules while TE Connectivity, Amphenol, and TDK supply resolvers and NTC thermistors.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
