

- Market Size (2026)
- USD 37.5 Bn
- Forecast (2036)
- USD 174.4 Bn
- CAGR (2026 to 2036)
- 16.6%
How big is the fiber to the home market in 2026?
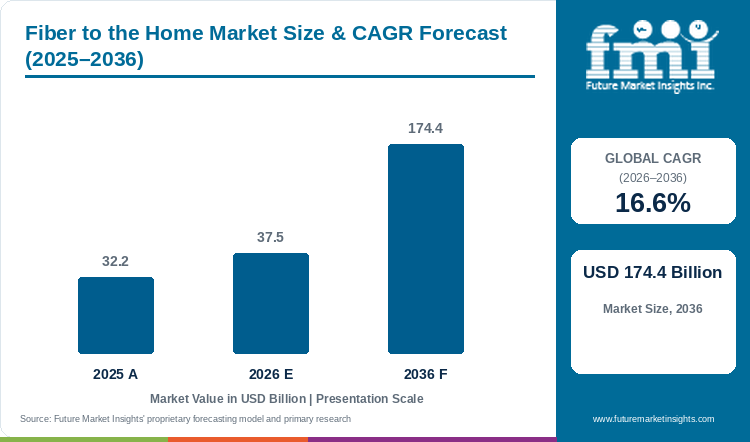
Demand is projected to expand at 16.6% CAGR from 2026 to 2036. Market value rises from USD 32.2 billion in 2025 to USD 37.55 billion in 2026 and USD 174.4 billion by 2036. [1]
FMI estimates the global fiber to the home (FTTH) market at USD 37.55 Billion in 2026, up from a 2025 baseline of USD 32.2 Billion, and projects revenue to reach USD 174.4 Billion by 2036, expanding at a robust 16.6% CAGR. Market growth depends heavily on operators successfully bridging the gap between completed network coverage and actual household activation. A home that merely has access to a fiber network still requires a finalized subscription, a scheduled installation appointment, and dependable in-home Wi-Fi performance across multiple connected devices to generate recurring revenue.
In 2026, the 100 Mbps to 1 Gbps speed tier is expected to account for 35.0% of forecast demand, while internet TV applications will represent 25.0% of the application mix. These metrics place familiar, high-bandwidth household uses squarely within the leading commercial categories, driving the need for reliable, high-capacity last-mile connections.
Key Market Trends and Insights
- The 100 Mbps to 1 Gbps tier carries a 35.0% forecast share in 2026 [1].
- Internet TV carries 25.0% in the forecast mix; A household connection can support several applications [1].
- Coverage expansion and customer activation remain different commercial steps [2].
Regional Highlights
- Fastest-growing profiled market: India at 21.3% CAGR from 2026 to 2036 [1].
- UK rural take-up was 56% of covered premises compared with 40% in urban areas in July 2025; different conversion rates affect build economics [2].
Market Size and Forecast
Table 1: Market size and forecast for the fiber to the home market in USD billion and percentage
| Metric | Value |
|---|---|
| 2025 market size | USD 32.2 billion |
| Estimated market size in 2026 | USD 37.55 billion |
| Projected market size by 2036 | USD 174.4 billion |
| CAGR 2026 to 2036 | 16.6% |
| Added revenue 2026 to 2036 | USD 136.85 billion |
| Market expansion multiple | 4.6x |
Civil works establish coverage before subscription revenue arrives; operators coordinate construction, customer activation and installation as part of telecommunications services. Submarine optical fiber cables support a different part of the connectivity chain through long-distance transmission.
Network Availability and Take-up Evidence
Ofcom’s availability and take-up figures cover residential and commercial premises in the UK, showing access and active connections as distinct measures [2].
Table 2: Evidence and adoption indicators for the fiber to the home market
| Indicator | Data point or finding | Commercial relevance | Source |
|---|---|---|---|
| UK active connections | 10.6 million premises in July 2025 | Measures activated service | [2] |
| UK take-up | 42% of premises with full-fibre access | Shows the activation gap | [2] |
| Rural take-up | 56% of covered premises | Demonstrates geographic variation | [2] |
| Urban take-up | 40% of covered premises | Requires a separate conversion plan | [2] |
| EU deployment rules | Gigabit Infrastructure Act effect from 12 November 2025 | Infrastructure coordination differs from service activation | [3] |
Analyst Perspective
"The useful commercial step after a network build is an active household connection that the customer can install and use dependably. Operators can support that conversion through available appointments, suitable home equipment and clear service information, while local take-up evidence helps identify where existing coverage offers further opportunity. A higher speed tier also needs a practical reason for the household to choose it, linking the network specification with the experience delivered across home devices."
- Sudip Saha, Principal Consultant, FMI
How is the fiber to the home market segmented?
The market covers 3 commercial axes and region: download speed; application; end user.
By download speed: Under 100 Mbps; 100 Mbps to 1 Gbps; Above 1 Gbps. By application: Internet TV; Remote education; Online gaming; Other uses. By end user: Single-family homes; Multi-family homes; Other residential premises.
Why does the 100 Mbps to 1 Gbps tier lead demand within the download speed category?
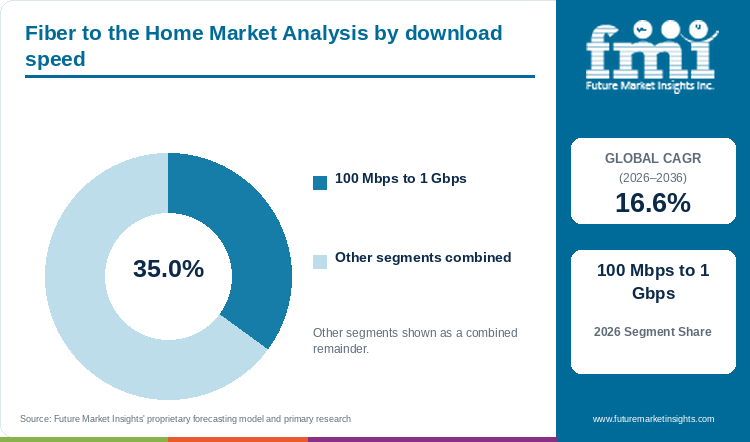
The 100 mbps to 1 gbps segment accounts for 35.0% of download speed demand in 2026. [1]
The 100 Mbps to 1 Gbps tier leads the download-speed mix because it supports several common household applications within a range customers can compare when choosing a residential service. The connection's practical value depends on more than the advertised tier, with installation quality and router performance influencing the experience across devices in the home. Operators can make the choice clearer by explaining the service and providing a usable activation route. Reliable support then helps the household use the connection for its intended mix of viewing, study, gaming and other online activities.
- The 100 Mbps to 1 Gbps tier accounts for 35.0% of forecast demand in 2026, with common household applications giving customers a practical context for comparing the speed and service offered by operators. [1]
- Suitable home equipment and a dependable installation influence the experience delivered within the advertised tier, while clear pricing and support help customers understand the subscription and use the connection across their household devices.
Table 3: Leading download speed share for the fiber to the home market
| Download speed | Share in 2026 |
|---|---|
| 100 Mbps to 1 Gbps | 35.0% |
| Other segments combined | 65.0% |
| Total | 100.0% |
Why does internet TV lead demand within the application category?
The internet tv segment accounts for 25.0% of application demand in 2026. [1]
Internet TV leads the application mix because viewing requires a stable household connection that can deliver content dependably across the devices customers use. Content delivery networks support distribution beyond the home, while the residential link and local equipment influence the experience at the point of viewing. A clear installation route helps customers activate the service and connect suitable devices, allowing the operator to turn available network coverage into a usable subscription. Households can use the same connection for several applications, making overall reliability useful alongside the viewing requirement.
- Internet TV accounts for 25.0% of the forecast application mix in 2026, placing stable throughput and a dependable household connection among the practical requirements operators need to meet for customers using connected viewing services. [1]
- Installation support and suitable local equipment help customers use viewing services across their devices, while reliable residential links work alongside content distribution infrastructure to deliver the experience expected from an active home connection.
What are the drivers restraints and opportunities in the fiber to the home market?
- Driver: Active household connections turn available network coverage into subscription receipts, giving operators a direct growth opportunity when homes already passed can complete installation and begin using a service suited to their needs. [2]
- Restraint: Civil works and network equipment require spending before enough subscribers activate service, so low take-up can leave installed capacity underused while final connections, appointment availability and household installation need further operational coordination.
- Opportunity: Existing coverage can support further customer activation when operators examine local conversion conditions, with Ofcom's differing rural and urban take-up rates providing evidence for acquisition and installation plans tailored to the available footprint. [2]
Active connections convert construction into receipts
Ofcom's take-up measure describes active connections within available coverage, giving operators context for the households that can access service but have not yet activated it. [2] Practical installation appointments, clear pricing and suitable home equipment can support that conversion, connecting a completed footprint with the continuing subscription receipts associated with a usable household service.
Construction precedes customer activation
Civil works and equipment spending take place before a network has enough active subscribers to support its commercial plan, making take-up relevant alongside the area covered. Final connections and customer installations also need coordination, so operators have to organize available appointments and support if completed capacity is to become a dependable service used by paying households.
Existing coverage can support further take-up
Ofcom reports differing rural and urban take-up rates, showing that customer activation conditions vary across locations within available network coverage. [2] Operators can examine those local conditions when planning acquisition and installation, allowing the existing footprint to inform the next commercial step as they connect interested households with service that can be booked and used.
Which country CAGRs are profiled in the fiber to the home market?
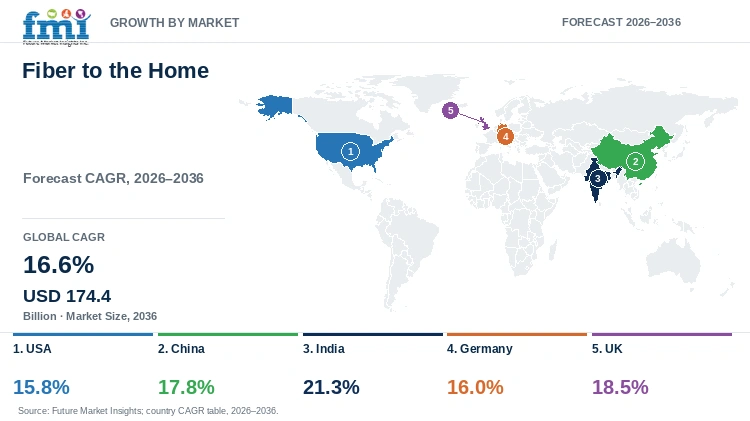
Table 5: Country CAGR comparison for the fiber to the home market
| Country | CAGR 2026 to 2036 |
|---|---|
| USA | 15.8% |
| China | 17.8% |
| India | 21.3% |
| Germany | 16.0% |
| UK | 18.5% |
Country-wise Analysis
United States
Operators need to distinguish network availability from household adoption; installation scheduling and clear service pricing heavily affect how quickly a new build generates paying customers. On the regulatory front, the Federal Communications Commission (FCC) continues to refine its national broadband mapping to ensure accurate deployment tracking, while the massive federal BEAD (Broadband Equity, Access, and Deployment) program heavily subsidizes rural fiber expansion to close the digital divide. Additionally, the Federal Trade Commission (FTC) and FCC have increasingly scrutinized hidden "junk fees" and equipment rental costs, forcing providers to ensure transparent pricing and straightforward contracts to drive subscriber conversion. The USA fiber to the home market is projected to expand at a 15.8% CAGR from 2026 to 2036.
China
Speed-tier migration can raise receipts within an existing network; however, operators still need to provide suitable home Wi-Fi equipment and a clear, value-driven reason for the customer to upgrade to a higher tier. This migration is heavily guided by the Ministry of Industry and Information Technology (MIIT), which actively promotes the national "Dual Gigabit" network development plan and mandates the continuous optimization of optical access networks to support smart home applications, cloud gaming, and industrial IoT. The China fiber to the home market is projected to expand at a 17.8% CAGR from 2026 to 2036.
India
The final home connection and customer-support route matter just as much as backbone construction; an installation that remains pending due to local municipal disputes does not produce the same revenue as an active subscriber. To accelerate deployment, the Department of Telecommunications (DoT) has aggressively streamlined national Right-of-Way (RoW) rules and pushed the BharatNet project to connect rural gram panchayats with optical fiber. Simultaneously, the Telecom Regulatory Authority of India (TRAI) strictly monitors Quality of Service (QoS) standards and transparent billing practices to protect consumer interests and ensure fair competition among regional and national ISPs. The India fiber to the home market is projected to expand at a 21.3% CAGR from 2026 to 2036.
Germany
Shared ducts and building access can significantly affect construction effort and capital expenditure in Germany. To alleviate this bottleneck, the Gigabit Infrastructure Act entered into effect in November 2025, introducing strict measures addressing infrastructure sharing, open-access networks, and civil works coordination. The Federal Network Agency (Bundesnetzagentur) actively oversees these mandates, ensuring that dominant telecom players provide fair, regulated access to their physical infrastructure (such as ducts and poles) to prevent monopolistic bottlenecks and accelerate nationwide fiber rollout. FMI projects Germany's fiber to the home market to expand at a 16.0% CAGR from 2026 to 2036, with operators managing these complex build procedures alongside the separate installation and customer-activation work needed to create paid household connections.
United Kingdom
Ofcom's reported 42% take-up rate clearly distinguishes connected premises from those that merely have coverage available, while differing rural and urban conversion rates give United Kingdom operators a highly local basis for examining activation within existing footprints. To support market competition, Ofcom strictly enforces Physical Infrastructure Access (PIA) regulations, requiring Openreach to allow rival alt-nets to use its ducts and poles. Furthermore, the government’s Building Digital UK (BDUK) and Project Gigabit initiatives provide vital state subsidies to ensure commercial viability in the hardest-to-reach rural areas where private investment alone falls short. FMI forecasts the United Kingdom fiber to the home market to grow at an 18.5% CAGR from 2026 to 2036, placing practical installation access and customer acquisition alongside the continued development of available network coverage.
Who are the notable companies in the fiber to the home market?
Notable players in the market include AT&T; Verizon; China Telecom; Deutsche Telekom; BT Group
Competitive Benchmarking
Table 6: Competitive positioning for the fiber to the home market
| Company or institution | Positioning | Evidence or purchasing distinction |
|---|---|---|
| AT&T | Fiber broadband operator | Residential fiber broadband services. [1] |
| Verizon | Residential fiber services | Residential fiber services. [1] |
| China Telecom | Fixed-network operator | Residential fiber access services. [1] |
| Deutsche Telekom | Fiber network and broadband operator | Operates an FTTH network serving residential broadband customers. [4] |
| BT Group | Full-fibre broadband provision | Offers full-fibre broadband and develops network coverage through Openreach. [5] |
Key Developments in the Fiber to the Home Market
- Ofcom's 2025 report measures full-fibre take-up at 42% of premises with access in July 2025, documenting the gap between available coverage and active connections and providing context for operators assessing activation opportunities within completed networks. [2]
- Ofcom reports rural take-up of 56% and urban take-up of 40% among covered premises in July 2025, showing different local conversion conditions that operators can consider when planning acquisition, appointments and installation capacity. [2]
- The Gigabit Infrastructure Act entered into effect in November 2025 with measures addressing infrastructure sharing and deployment coordination, providing a framework relevant to build procedures while operators continue the commercial work of activating household subscribers. [3]
Key Players in the Fiber to the Home Market
AT&T; Verizon; China Telecom; China Mobile; China Unicom; Deutsche Telekom; BT Group; Reliance Jio; Bharti Airtel.
Fiber to the Home Market Report Scope
Table 7: Report coverage for the fiber to the home market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Download speed; Application; End user; region |
| Quantitative units | USD billion |
| Market definition | Fiber access reaching residential premises within the FTTH boundary. Copper-only and mobile access are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries profiled | USA; China; India; Germany; UK |
| Key companies profiled | AT&T; Verizon; China Telecom; China Mobile; China Unicom; Deutsche Telekom; BT Group; Reliance Jio; Bharti Airtel |
| Forecast period | 2026 to 2036 |
Fiber to the Home Market Research Methodology
Table 8: Research methods for the fiber to the home market
| Method | Approach |
|---|---|
| Published market outlook | FMI's published outlook supplies the market values, forecast period, country CAGRs and segment shares presented in the report. [1] |
| Market definition review | The product, customer and sales-channel categories are reviewed against the report's scope and monetary units. |
| Public evidence review | Ofcom availability and take-up records and European Commission deployment guidance provide context on active connections, local conversion and infrastructure procedures. [2][3] |
| Country conditions review | Country discussion considers the local purchasing, service or product requirements documented in the cited public sources. |
| Company disclosure review | Public company pages support the descriptions of documented offerings and operating roles in the competitive tables. [4][5] |
| Commercial interpretation | The evidence is interpreted through the purchasing conditions, delivery requirements and repeat-use decisions described in the article. |
| Evidence reconciliation | Market research, public statistics, policy material and company disclosures are examined for their relevance to the defined product scope and commercial conditions. |
Fiber to the Home Market by Segments
By download speed
- Under 100 Mbps
- 100 Mbps to 1 Gbps
- Above 1 Gbps
By application
- Internet TV
- Remote education
- Online gaming
- Other uses
By end user
- Single-family homes
- Multi-family homes
- Other residential premises
Fiber to the Home Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Future Market Insights. Published outlook accessed 12 October 2026. Fiber to the Home Market.
- [2] Ofcom. 19 November 2025; July 2025 observations. Connected Nations UK Report 2025.
- [3] European Commission. 12 November 2025. Rules to ease the rollout of better connectivity networks enter into effect.
- [4] Deutsche Telekom. Accessed October 2026. Deutsche Telekom company and product information.
- [5] BT Group. Accessed October 2026. BT Group company and product information.
This Report Answers
- How big is the fiber to the home market in 2026?
- What market value is projected by 2036?
- Which download speed segment leads demand?
- Which other commercial categories shape the market?
- Which countries have the fastest profiled growth?
- Which companies and institutions participate in the market?
Frequently Asked Questions
How large is the fiber to the home market in 2026?
FMI estimates market value at USD 37.55 billion in 2026; the estimated 2025 value is USD 32.2 billion [1].
What value and CAGR are projected through 2036?
Market value is projected to reach USD 174.4 billion by 2036 at a 16.6% CAGR from 2026 to 2036 [1].
Which download speed segment leads in 2026?
100 Mbps to 1 Gbps account for 35.0% of this category [1].
What is the report segmentation?
Download speed; Application; End user, and region.
Which profiled market records the highest CAGR?
India has the highest profiled rate at 21.3% from 2026 to 2036 [1].
Who are the key participants?
AT&T; Verizon; China Telecom; China Mobile; China Unicom; Deutsche Telekom; BT Group; Reliance Jio; Bharti Airtel.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By download speed, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By download speed, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By download speed, 2026 to 2036
- Under 100 Mbps
- 100 Mbps to 1 Gbps
- Above 1 Gbps
- Y-o-Y Growth Trend Analysis By download speed, 2021 to 2025
- Absolute $ Opportunity Analysis By download speed, 2026 to 2036
- Global Market Analysis and Forecast, By application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By application, 2026 to 2036
- Internet TV
- Remote education
- Online gaming
- Other uses
- Y-o-Y Growth Trend Analysis By application, 2021 to 2025
- Absolute $ Opportunity Analysis By application, 2026 to 2036
- Global Market Analysis and Forecast, By end user, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By end user, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By end user, 2026 to 2036
- Single-family homes
- Multi-family homes
- Other residential premises
- Y-o-Y Growth Trend Analysis By end user, 2021 to 2025
- Absolute $ Opportunity Analysis By end user, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC countries
- South Africa
- Türkiye
- Israel
- By download speed
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By download speed
- By application
- By end user
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By download speed
- By application
- By end user
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By download speed
- By application
- By end user
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- AT&T
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Verizon
- China Telecom
- Deutsche Telekom
- BT Group
- AT&T
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


