

- Market Size (2026)
- USD 135.4 Bn
- Forecast (2036)
- USD 260.0 Bn
- CAGR (2026 to 2036)
- 6.7%
How big is Functional Flour Market in 2026?
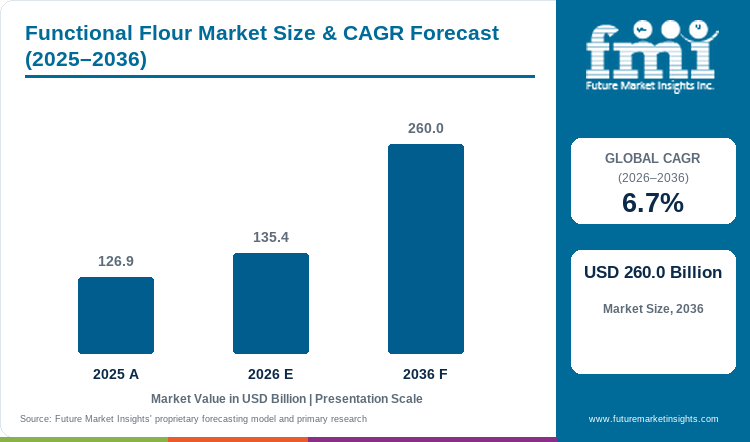
USD 135.4 billion in 2026 and USD 260.0 billion by 2036, expanding at 6.7% CAGR.
Demand for functional flour is projected to expand at 6.7% CAGR between 2026 and 2036, growing from USD 126.9 billion in 2025 to USD 135.4 billion in 2026, and escalating to USD 260.0 billion by 2036. Nutrition specifications are turning staple flour into a controlled ingredient with stable nutrient and processing requirements. The Food Fortification Initiative reported in August 2026 that 21 countries made new or strengthened fortification commitments at the 2025 Nutrition for Growth Summit. Participating mills are translating wheat-flour pledges into controlled premix dosing and routine composition checks.
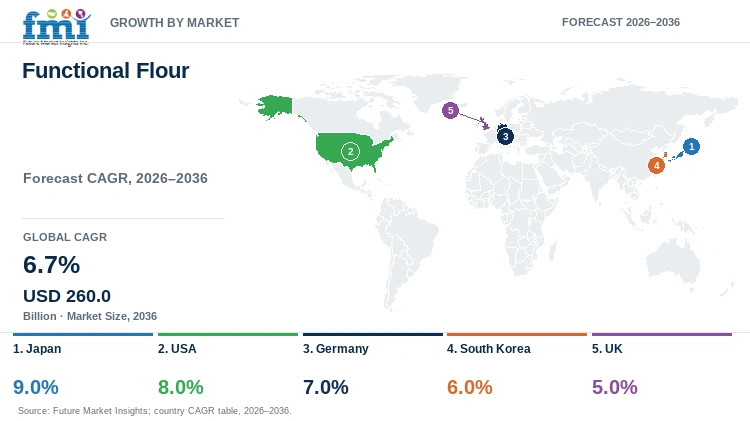
Japan is projected to grow at 9.0% CAGR through 2036 and the USA is forecast to grow at 8.0%. Japanese processors are managing greater exposure to changes in imported food-wheat supply. US flour buyers are qualifying specifications inside a large domestic milling system. USDA National Agricultural Statistics Service reported 222 million bushels of wheat ground during first-quarter 2026. National flour production reached 103 million hundredweight in the same quarter. US milling scale is rewarding specifications that perform consistently at several customer plants. Japanese buyers are placing greater value on formulation flexibility as wheat origin or crop quality changes.
Key Takeaways of Functional Flour Market
- Food producers are specifying functional flou r for nutrient delivery and process performance within familiar ingredient systems.
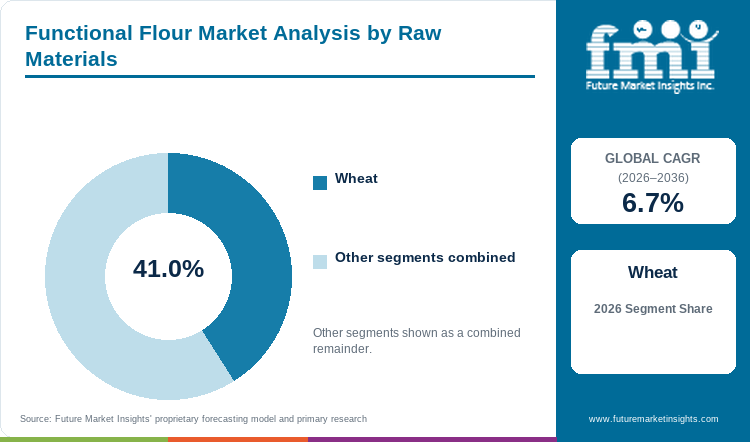
- By raw materials wheat is estimated to hold 41.0% in 2026. Broad baking use and established mill specifications support its position.
- Fortified flours are set to lead the type category with 41.0% share in 2026, attributable to micronutrient addition during routine milling operations.
- Application teams are testing absorption and dough handling because nutrient content alone cannot guarantee stable finished-product texture during routine production.
- Crop and flour variability can delay supplier approval because process adjustments can erase a lower ingredient price advantage.
- Some of the key players in this market include ADM, Cargill, Bunge Global SA, Ardent Mills, General Mills, King Arthur Baking Company, Ingredion, Bühler Group, Puratos, and Corbion.
Analyst Perspective
"Functional flour earns repeat business by maintaining its claimed nutritional or processing benefit under the buyer’s normal production conditions. Suppliers need mill control and application evidence because qualification risk can outweigh modest price differences."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Functional Flour Market segmented?
The functional flour market is segmented by Raw Materials, Type and Region.
The raw materials axis includes wheat, maize, rice and others for grain-base specification analysis. The type axis includes fortified flours, specialty flours and pre-cooked flours for commercial function analysis. The region taxonomy covers the standard global hierarchy used for country and regional analysis.
How does wheat support functional specifications within the raw materials category?
Industrial mills are controlling protein strength and particle characteristics for established bakery processes. Malaysia expanded mandatory wheat flour fortification in 2025 to flour sold in bags of 25 kilograms or less under revised health rules. The rule adds nutrient composition to existing quality checks for dough performance and finished-product consistency. Suppliers are pairing whole-wheat flour with documented fortification and preserving familiar milling behavior. Controlled specifications keep nutrition claims compatible with repeatable line performance during routine production.
- Based on raw materials wheat is projected to account for 41.0% in 2026. Its position is influenced by established mill specifications and broad baking use.
- Millers are retaining repeat orders by keeping nutrient dosing and dough behavior within approved limits despite normal crop variation.
How are fortified flours converting nutrition requirements into repeat purchasing?
Fortified flours are addressing a different purchasing problem because the functional claim depends on micronutrient content rather than grain identity alone. The Philippines is updating compulsory wheat flour fortification standards to add folic acid and restrict allowable iron forms under a program documented in October 2025. Mills are controlling dose and nutrient form to satisfy the national specification. Food manufacturers are using familiar flour bases without adding a separate nutrient-delivery step downstream. Food fortifying agents are part of the same dosing and quality-assurance process for regulated micronutrient levels.
- In 2026 fortified flours are expected to lead the type category with 41.0% share. Regulated nutrient delivery and mill-level dose control are driving that position.
- Documented micronutrient levels and stable processing performance are supporting repeat purchases through consistent batch control.
What are the drivers, restraints and opportunities in the Functional Flour Market?
Nutrition specifications are increasing functional flour use, crop variability is raising qualification costs, and replacement-focused formulations are widening routes for value-added flour products.
- Driver: Fortification requirements are increasing purchases because mills must document nutrient composition and production consistency.
- Restraint: Crop and flour variability is raising qualification costs by changing process behavior between lots and suppliers.
- Opportunity: Grain-based functional ingredients can replace costlier formulation components once application trials establish equivalent performance.
How are fortification requirements converting nutrition policy into flour purchases?
Mandatory wheat-flour standards are increasing functional flour purchasing because mills must supply defined micronutrient composition instead of commodity-grade flour alone. The Food Fortification Initiative documented in May 2025 that Mauritius finalized a national fortified-wheat-flour standard and mandatory regulations. Commercial mills are translating the rule into controlled premix dosing and documented compliance. Food fortification is making nutrient composition part of the purchase specification for covered flour. Application teams are testing fortified flour against normal production behavior during approval.
How is flour variability slowing supplier approval and routine switching?
Flour variability is raising qualification costs because protein content and enzyme activity can alter water absorption or finished-product behavior between crop lots. Puratos opened a Flour Competence Center in June 2026 to analyze those variations and translate laboratory measurements into bakery guidance. Buyers are comparing flour lots through hydration and fermentation tests instead of treating them as interchangeable. Flour improvers can compensate for some variation but they introduce another formulation step that buyers must validate.
How can functional flour replace more complex formulation ingredients?
Functional flour is gaining value by replacing part of a costlier formulation component without disrupting finished-product performance. Ardent Mills introduced a wheat-based Cocoa Replace in May 2025 for use in cakes, brownies, cookies, and muffins, with a stated replacement level of up to 25% of cocoa powder. The commercial route is narrower than a general clean-label claim because the flour-based ingredient must reproduce color and flavor support alongside processing behavior in each application. Clean-label ingredients are giving suppliers a reformulation route that balances familiar declarations with cost-in-use. Recipe-specific trials are confirming performance for manufacturers considering repeat production volume.
Which country CAGRs are profiled in the Functional Flour Market?
| Country | CAGR |
|---|---|
| Japan | 9.0% |
| USA | 8.0% |
| Germany | 7.0% |
| South Korea | 6.0% |
| UK | 5.0% |
How do country-level CAGRs compare in the Functional Flour Market?
The country forecasts range from 9.0% in Japan to 5.0% in the UK. The four-point spread reflects grain-supply exposure and milling conditions instead of current market size. Japan and the USA form the upper growth band. Germany occupies the middle position. South Korea and the UK follow under different processing and regulatory conditions.
- Japan’s reliance on imported food wheat is increasing the value of formulation flexibility for noodle and bakery processors managing changes in grain origin and crop quality.
- US milling throughput and multi-site food production are rewarding suppliers that maintain narrow flour specifications during qualification at several customer plants.
- Germany’s measured variation in wheat baking quality is keeping mill testing and formulation control important despite sufficient domestic grain availability.
- South Korea’s export-oriented food processing base is increasing the value of repeatable flour behavior in ramen and other high-throughput production formats.
- UK nutrient requirements are making fortification control and compliant flour documentation routine parts of supplier evaluation alongside stable dough performance.
Comparable CAGRs can produce different entry conditions because local mills and food manufacturers are qualifying functionality against different operating constraints. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Japanese noodle and bakery manufacturers are managing imported food-wheat exposure as domestic harvest conditions tighten. Functional flour demand in Japan is projected to expand at 9.0% CAGR through 2036, influenced by changing wheat origin and crop quality. USDA Foreign Agricultural Service anticipated higher food-wheat and food-barley imports in MY2024/25 following smaller domestic harvests. Specialty bread flour gives processors a formulation option with defined absorption and dough performance despite changes in wheat origin.
- US flour manufacturers are operating at national scale, so a specification error can affect multiple customer plants and production lines. The functional flour market in the USA is forecast to grow at 8.0% CAGR from 2026 to 2036, supported by a large milling base that rewards consistent specifications. USDA National Agricultural Statistics Service reported that US mills ground 907 million bushels of wheat and produced 419 million hundredweight of flour during 2025. Corn flour and wheat-based specialty products are competing inside a large processing base that values repeatable protein ranges and predictable application performance.
- German flour buyers are sourcing substantial domestic wheat, yet baking quality varies enough to require mill and application control. Germany's functional flour outlook is anticipated to advance at 7.0% CAGR over the assessment period, attributable to variable baking quality that requires mill testing and formulation control. The Max Rubner-Institut reported in September 2025 that about one-fifth of the German wheat harvest missed the trade threshold for baking quality in a nationally representative assessment. Flour mixes give millers a way to manage performance gaps that raw grain quality alone cannot remove. German suppliers need analytical testing and formulation support to convert variable crop quality into stable specifications for repeat production.
- South Korean food processors are serving export categories that require consistent flour behavior at high production rates. Functional flour demand in South Korea is predicted to advance at 6.0% CAGR through 2036, reinforced by export-oriented food processing and high-throughput production. USDA Foreign Agricultural Service reported in April 2025 that record 2024 ramen exports increased wheat use for food processing and encouraged ramen capacity expansion. Bakery ingredients are supporting the same emphasis on repeatability in bread and other formulated foods. Flour suppliers are converting trial volume into repeat demand by demonstrating texture stability under actual mixing and thermal conditions.
- UK flour buyers are operating under a defined national nutrient specification for non-wholemeal common wheat flour. Functional flour sales in the UK are forecast to expand at 5.0% CAGR by 2036, shaped by national nutrient specifications and processing-performance requirements. Government guidance published in April 2025 requires calcium carbonate plus iron and niacin with thiamin for covered flour. Folic acid is scheduled to become mandatory from December 13, 2026. Mineral fortification is becoming part of routine composition control instead of a discretionary claim for affected flour.
Who are the notable companies in the Functional Flour Market?
ADM, Cargill, Bunge Global SA, Ardent Mills, General Mills, King Arthur Baking Company, Ingredion, Bühler Group, Puratos, and Corbion are the notable companies serving direct flour, formulation, milling, or bakery qualification roles in this market.
Competition includes direct flour millers and grain-ingredient specialists alongside firms that support qualification. Buyers are requiring documented composition and repeatable processing performance for approved flour specifications. Milling transactions are changing supplier footprints without altering the technical conditions used to qualify functional flour.
- ADM and Ardent Mills are supplying direct flour alongside General Mills and King Arthur Baking Company. Bunge Global SA retains a grain and milling position tied to defined specifications.
- Ingredion and Cargill are addressing formulation requirements for grain-derived systems that must maintain texture and processing performance alongside nutritional targets.
- Bühler Group and Puratos are supporting milling or bakery qualification alongside Corbion. Their technical support is influencing functional-flour selection even though they do not sell the same direct-flour product set.
Competitive Benchmarking: Functional Flour Market
| Company | Flour-Scope Fit | Qualification Support | Processing Control | Geographic Reach |
|---|---|---|---|---|
| ADM | High | High | High | North America and international ingredient operations |
| Cargill | Medium | High | Medium | Global food ingredient network |
| Bunge Global SA | Medium | Low | Medium | Global grain network with milling concentrated outside North America |
| Ardent Mills | High | High | High | United States, Canada, and Puerto Rico |
| General Mills | High | High | Medium | United States foodservice and flour channels |
| King Arthur Baking Company | High | Medium | Low | United States retail and foodservice reach |
| Ingredion | Medium | High | Medium | Global ingredient and application network |
| Bühler Group | Low | High | Medium | Global grain-processing technology network |
| Puratos | Low | High | Medium | More than 100 countries |
| Corbion | Low | High | Low | Europe, North America, and Asia-focused bakery network |
Scoring basis: High flour-scope fit requires direct functional or specialty flour evidence. Medium covers a narrower grain-derived formulation role. Low identifies qualification support without direct flour supply. High qualification support requires dedicated flour testing facilities. Medium requires documented technical support. Low indicates limited public flour-specific support. High processing control requires direct milling assets. Medium covers formulation control and Low indicates little direct control of flour processing assets.
Key Developments in the Functional Flour Market
- In October 2025 ADM added two electric heavy goods vehicles for direct flour deliveries from its Corby processing facility to UK customers. The vehicles now support flour logistics for an active milling operation without changing the specification supplied to commercial buyers.
- In June 2025 Bühler Group opened a 1,800-square-meter Milling Academy in Uzwil for food and feed millers. The facility now combines training with research and milling technology used to control flour-processing conditions.
- In March 2025 Cargill presented functional blends for Indian B2B food applications including bakery at AAHAR 2025. The presentation paired ingredient systems with application demonstrations and research sessions for manufacturers evaluating formulation performance.
Key Players in the Functional Flour Market
Direct Flour and Milling Suppliers
- ADM
- Bunge Global SA
- Ardent Mills
- General Mills
- King Arthur Baking Company
Functional Grain and Formulation Specialists
- Ingredion
- Cargill
Milling and Bakery Qualification Enablers
- Bühler Group
- Puratos
- Corbion
Functional Flour Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By Raw Materials, Type and Region. |
| Quantitative Units | Revenue in USD billion and CAGR in %. |
| Market Definition | Revenue from commercially sold functional flour is included when nutrition or processing functionality forms part of the flour specification. Conventional commodity flour without functional positioning, isolated starches or proteins sold separately, downstream finished foods, and standalone bakery improvers are excluded. Custom blends are included when they are sold as functional flour. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Japan, USA, Germany, South Korea, UK, and 20+ countries included in the full report. |
| Key Companies Profiled | ADM, Cargill, Bunge Global SA, Ardent Mills, General Mills, King Arthur Baking Company, Ingredion, Bühler Group, Puratos, and Corbion. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Functional Flour Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Functional Flour Market by Segments
Functional Flour Market segmented by Raw Materials:
- Wheat
- Maize
- Rice
- Others
Functional Flour Market segmented by Type:
- Fortified Flours
- Specialty Flours
- Pre-Cooked Flours
Functional Flour Market by Region:
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Food Fortification Initiative. (2026, August 10). Advancing Global Accountability on Food Fortification Commitments.
- U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, May 1). Flour Milling Products.
- Food Fortification Initiative. (2025, May 6). Malaysia: Committing to Wheat Flour Fortification.
- Food Fortification Initiative. (2025, October 3). The Philippines: “Bridging the Fortification Gap Project”.
- Food Fortification Initiative. (2025, May 6). Mauritius Mandates Wheat Flour Fortification to Combat Micronutrient Deficiencies.
- Puratos. (2026, June 15). Puratos Opens Flour Competence Center to Address Flour Variability.
- Ardent Mills. (2025, May 14). Ardent Mills Introduces Cocoa Replace to Address Cost and Supply Instability.
- U.S. Department of Agriculture, Foreign Agricultural Service. (2025, March 19). Japan: Grain and Feed Annual.
- U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, May 1). Flour Milling Products 2025 Summary.
- Max Rubner-Institut. (2025, September 18). 60 Jahre Besondere Ernte- und Qualitätsermittlung.
- U.S. Department of Agriculture, Foreign Agricultural Service. (2025, April 4). South Korea: Grain and Feed Annual.
- Department for Environment, Food & Rural Affairs and Food Standards Agency. (2025, April 23). Bread and flour: labelling and composition.
- ADM. (2025, October 9). ADM Continues to Support Customer Needs and Supply Chain Resilience with Expansion of Electric Truck Fleet for UK Flour Deliveries.
- Bühler Group. (2025, June 11). Bühler sets new global standard with state-of-the-art Milling Academy.
- Cargill. (2025, March 4). Cargill Showcases Full Range of Innovative Food Solutions at AAHAR 2025.
- Ingredion Incorporated. (2026, May 28). Ingredion announces strategic partnership with Sanstar Limited expanding access to pharma and food ingredient markets in India.
- ADM. (2026, May 20). ADM Advances Protein Innovation with New Ingredient Solutions.
- Corbion. (2026, June 15). Corbion launches LUMI™ Set to help bakers reformulate away from titanium dioxide without sacrificing visual appeal.
- Ardent Mills. (2026, February 20). Ardent Mills® Dark Cocoa Replace Expands Growing Line of Cocoa Replacers.
- Bunge Global SA. (2025, July 1). Bunge Completes Sale of its North America Corn Milling Business.
- ADM. (2025, October 14). ADM Advances Quality Capabilities with opening of New Central Lab-Milling.
- Cargill. (2026, September 7). Cargill helps food manufacturers accelerate product development processes with tailored functional systems.
- Bunge Global SA. (2025, April 15). Bunge Announces Sale of its North America Corn Milling Business.
- Ardent Mills. (2025, July 31). Ardent Mills Enters Agreement to Acquire Stone Mill in North Dakota, Expanding Emerging Nutrition Portfolio.
- General Mills Foodservice. (2025, February 25). General Mills Foodservice Brings Winning Pizza Crust Solutions to Pizza Expo.
- King Arthur Baking Company. (2025, March 5). King Arthur Baking Company Expands Flour Line with the Launch of Buttermilk Biscuit Flour Blend.
- Univar Solutions. (2025, June 18). Univar Solutions and Ingredion Expand Functional Food and Beverage Ingredients Partnership to Benelux Region.
- Bühler Group. (2026, May 7). Bühler launches innovations and releases major upgrades to its Grains & Food portfolio.
- Puratos. (2025, June 6). Puratos signs the Sustainable Wheat Initiative manifesto.
- Corbion. (2025, April 21). Corbion Unveils Verdad® Essence WH100: Redefining Natural Mold Inhibition for Bakers.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the functional flour market in 2026 and 2036?
- Which specifications convert nutrition requirements into repeat functional flour purchases?
- Why does wheat hold 41.0% of raw materials demand in 2026?
- Why do fortified flours hold 41.0% of type demand in 2026?
- How does crop variability change functional flour supplier qualification decisions?
- Which reformulation routes create additional demand for grain-based functional ingredients?
- Which national conditions explain functional flour demand in Japan and USA?
- Which companies supply flour or support functional flour qualification activities?
- Which recent company developments change milling logistics or application-support capabilities?
Frequently Asked Questions
How big is the Functional Flour Market in 2026?
The functional flour market is estimated at USD 135.4 billion in 2026 and is projected to reach USD 260.0 billion by 2036. Food manufacturers are specifying flour for nutrient control and repeatable processing performance beyond conventional commodity-grade requirements.
What is the CAGR of the Functional Flour Market from 2026 to 2036?
The functional flour market is expected to grow at 6.7% CAGR between 2026 and 2036. Nutrition control and repeatable processing performance are supporting the projected increase within the defined functional-flour scope.
Which raw materials segment leads the Functional Flour Market?
By raw materials wheat is forecast to represent 41.0% in 2026. Industrial milling systems are supporting the segment through defined baking specifications and established fortification routes.
Which type segment leads the Functional Flour Market?
Fortified flours are likely to capture 41.0% of the type category in 2026. Milling operations are reinforcing this position by adding micronutrients without changing the flour base or routine dough handling.
Which companies are active in the Functional Flour Market?
Key companies in the functional flour market include ADM, Cargill, Bunge Global SA, Ardent Mills, General Mills, King Arthur Baking Company, Ingredion, Bühler Group, Puratos, and Corbion. The group includes direct millers and grain-derived formulators. Bakery specialists and milling-technology providers are supporting application qualification.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Raw Materials, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Raw Materials, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Raw Materials, 2026 to 2036
- Wheat
- Maize
- Rice
- Others
- Y-o-Y Growth Trend Analysis By Raw Materials, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Materials, 2026 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Fortified Flours
- Specialty Flours
- Pre-Cooked Flours
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Raw Materials
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Materials
- By Type
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Materials
- By Type
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Raw Materials
- By Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ADM
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill
- Bunge Global SA
- Ardent Mills
- General Mills
- King Arthur Baking Company
- Ingredion
- Bühler Group
- Puratos
- Corbion
- ADM
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


