

- Market Size (2026)
- USD 515.0 Mn
- Forecast (2036)
- USD 1387.6 Mn
- CAGR (2026 to 2036)
- 10.4%
How big is Fungal Protein Market in 2026?
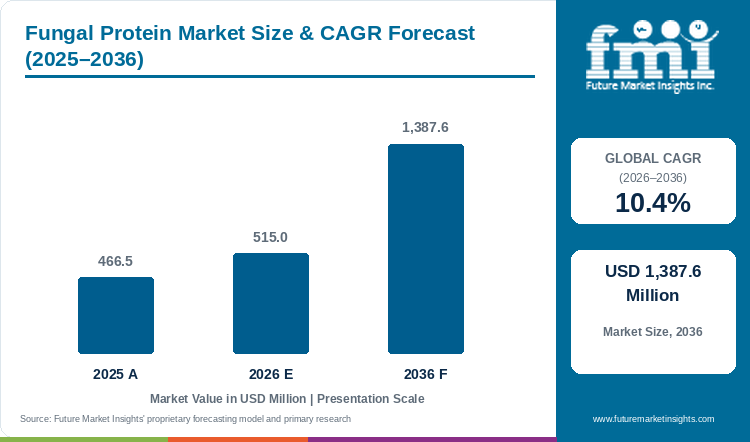
Demand for fungal protein is projected to expand at 10.4% CAGR between 2026 and 2036. Industry value grows from USD 466.5 million in 2025 to USD 515.0 million in 2026 and is projected to reach USD 1,387.6 million by 2036.
Fungal protein demand has moved from limited development batches towards ingredients that can be used in familiar foods. As per FMI, the market increases from USD 466.5 million in 2025 to USD 515.0 million in 2026 and is projected to reach USD 1,387.6 million by 2036 at 10.4% CAGR. In June 2026, The Protein Brewery received European authorization for Fermotein, which contains about 50% protein and 30% dietary fibre.[1] This authorization gives food manufacturers one defined mycelium ingredient for powders, bars, dairy alternatives, foods and drinks. Mature yeast proteins will continue to support volume applications, while authorized mycelium is expected to widen premium sports nutrition product development. However, taste, texture, processing stability and delivered cost will continue to decide whether a tested ingredient is used in regular production.
Country demand is expected to develop differently because regulatory approval systems and food development conditions vary across national markets. The USA is forecast to expand at 12.7% CAGR through 2036, while Japan is projected at 12.3%. In August 2026, the FDA proposed stronger GRAS oversight under docket FDA-2025-N-3262.[2] This is expected to increase attention on safety evidence for every organism and intended use. Japan had about 1,900 participants in its Food Tech Council during June 2026, including companies, research bodies and government agencies. The U.S. has strong formulation capacity, while Japan is building commercialization through public and private participation. In both countries, proper safety records and product performance will remain necessary before regular buying starts.
Key Takeaways
- Food and nutrition manufacturers are testing fungal protein where fermentation can provide stable output and production throughout the year.
- Based on source, yeast is projected to account for 37.8% in 2026, owing to established fermentation knowledge and familiar production methods.
- By end use application, food and beverage is forecast to represent 37.4% in 2026, supported by use in several finished-food formats.
- Processed food is expected to hold a notable position in 2026, as the ingredient can provide protein enrichment along with texture.
- The USA is forecast at 12.7% CAGR through 2036, while Japan is projected at 12.3% owing to separate commercialization systems.
- Notable companies in fungal protein market include Cargill, Angel Yeast, Tate & Lyle, Corbion, Glanbia, Bunge, ADM and Kemin Industries.
Analyst Perspective
“I expect familiar food products to bring fungal protein into regular household use. However, authorization and stable product performance will decide which suppliers can expand.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the fungal protein market segmented?
Fungal protein market is segmented by two primary commercial axes and region: source, end use application, and region. Yeast is projected at 37.8%, while food and beverage is forecast at 37.4% in 2026.
By source: yeast, baker’s yeast, Fusarium venenatum, brewer’s yeast, and mushroom.
By end use application: food and beverage, processed food, animal nutrition, dairy, pet food, bakery, pharmaceuticals, and aquaculture.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
What supports yeast as a preferred fungal protein source?
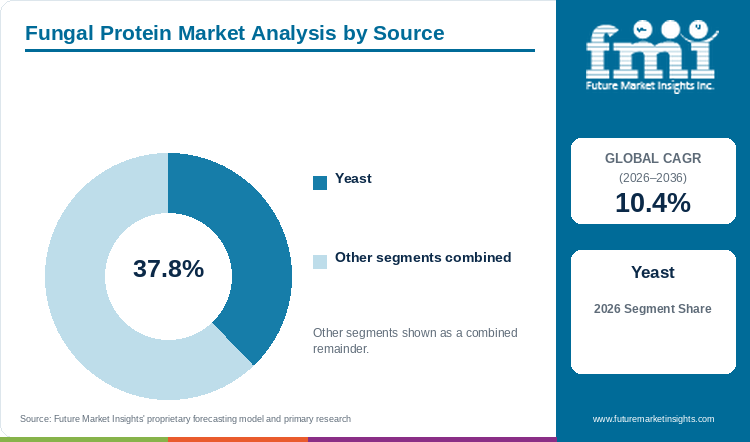
Based on source, yeast is projected to account for 37.8% in 2026, supported by established industrial fermentation knowledge.
Yeast protein is produced through fermentation systems which are already familiar to several ingredient manufacturers. This production route can run throughout the year and can provide protein-rich fractions with repeatable composition. Feedstock quality and downstream recovery will still influence the final protein level and cost of each batch.
- Yeast is projected to hold 37.8% of source demand in 2026 owing to mature fermentation practices and wider buyer familiarity.
- In November 2025, Angel Yeast started an 11,000-ton annual high-purity yeast protein line at Baiyang Biotechnology Park.[3]
Why does food and beverage hold notable end use demand?
By end use application, food and beverage is forecast to represent 37.4% in 2026, owing to broad formulation use.
Food and beverage provides wider use for fungal protein because one ingredient can be tested in different product forms. It can be applied for protein enrichment as well as texture development in foods and drinks. However, flavour, dispersibility and performance during heating will decide whether laboratory formulations can move into commercial production.
- Food and beverage is forecast at 37.4% in 2026 as one approved ingredient can be tested in several prepared-food formats.
- In April 2026, Quorn launched Lemon & Pepper Schnitzels for air-fryer preparation in under 15 minutes.[4]
What are the drivers, restraints, and opportunities in the fungal protein market?
In the fungal protein market, the key driver is formulation demand, the key restraint is ingredient authorization, and the key opportunity is application-ready supply.
- Driver: Food and nutrition teams are qualifying fermentation-derived proteins for texture, nutrition, and supply diversification.
- Restraint: Strain-specific safety reviews and scale economics delay broader commercial use when evidence or capacity remains incomplete.
- Opportunity: Approved ingredients with stable specifications can enter more food, beverage, feed, and nutrition trials through 2036.
Formulation Demand Broadens Protein Trials
Food developers require proteins that can work with the processing conditions already used in factories. In June 2026, UK regulators listed biomass fermentation among the food technologies expected to reach markets between 2025 and 2035.[5] The note also connected market access with authorization, production infrastructure and early regulatory support. This is expected to increase trials, but every fungal strain will still require its own evidence and suitable product use.
Authorization Extends Commercial Timelines
Fungal protein produced from a new organism cannot be treated as same as an already approved ingredient. Evidence is required for organism identity, manufacturing process, composition and intended use. The European Food Safety Authority published its assessment of Rhizomucor pusillus biomass in December 2025, before the ingredient received authorization in 2026.[6] This approval route increases development time when safety records are prepared after production scale-up has already started.
Approved Platforms Expand Application Routes
Approved ingredients create more application opportunities when customers can receive enough material for normal product trials. In March 2026, Enifer released its first commercial PEKILO mycoprotein batch for pet-food development.[7] The batch allowed customers to move beyond small samples and test nutrition, processing behaviour and repeat production. FMI data suggests that commercial supply will increase the number of trials where protein performance and manufacturing cost can be checked together.
Which country CAGRs are profiled in the fungal protein market?
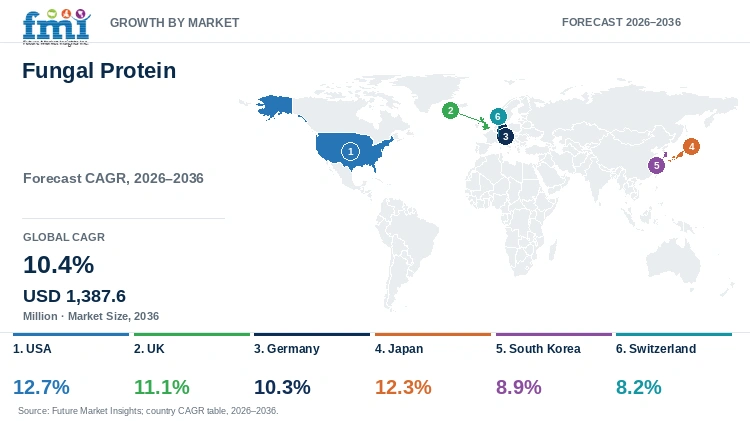
| Country | CAGR |
|---|---|
| USA | 12.7% |
| UK | 11.1% |
| Germany | 10.3% |
| Japan | 12.3% |
| South Korea | 8.9% |
| Switzerland | 8.2% |
How do country-level CAGRs compare in the fungal protein market?
Countries with clear ingredient routes are expected to start formulation work earlier, while newer systems can require more local evidence before launch. Product names, food formats and sensory expectations will also influence how quickly fungal protein enters each country.
- USA demand uses established food-ingredient pathways, while the proposed 2026 GRAS rule increases transparency and oversight.
- UK commercialization benefits from a 2026 guidance hub covering novel foods and emerging production technologies.
- Germany follows the EU novel-food route, which now includes an authorized Rhizomucor pusillus mycelium ingredient.
- Japan combines ministry-backed food-tech programs with company and research participation in commercialization projects.
- South Korea uses a statutory food-tech plan to connect technology development with domestic food-industry adoption.
- Switzerland requires a technical safety dossier when a fungi-derived food meets the national novel-food definition.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- Fungal protein demand in the USA is forecast to rise at 12.7% CAGR over the forecast period, supported by established food ingredient pathways and a large formulation industry. In July 2024, the FDA concluded its evaluation under GRAS Notice GRN 1117 for mycelial fungal protein containing 40% to 50% protein on a dry weight basis.[8] The evaluation gives manufacturers clearer documentation benchmarks for mycelial biomass added to human food. Fungal protein suppliers can utilize existing review routes, but evidence has to match the exact organism, process and intended application. This condition is likely to increase early documentation work before customers begin larger trials. The U.S. outlook therefore remains positive, although suppliers with incomplete safety records can face longer product development periods.
- UK fungal protein demand is anticipated to advance at 11.1% CAGR through 2036, influenced by familiarity with mycoprotein and policy support for emerging foods. In June 2026, the Food Standards Agency published a guidance hub for novel foods, precision fermentation and related technologies.[9] The guidance hub connects technology development with clear evidence requirements for new production routes. UK consumers already know some mycoprotein products, which reduces the need to introduce the category from the beginning. However, new organisms and production routes still require separate review. Growth will depend on suppliers bringing approved ingredients into products that fit existing retail formats and food manufacturing processes.
- The German fungal protein sector is projected to record 10.3% CAGR during the assessment period, underpinned by national food-tech innovation funding and European novel-food regulations. In October 2024, Germany's Federal Ministry of Food and Agriculture granted EUR 2.6 million to develop mycelium protein production through whey fermentation.[10] This initiative connects regional food-processing side streams with sustainable protein extraction. German manufacturers can now test mycelial ingredients in permitted applications while domestic production infrastructure expands. However, broader commercial use still requires compliance with EU novel-food requirements. Each subsequent ingredient will require evidence matching its own composition and use. This creates a direct research incentive for domestic fermentation, while maintaining a documentation barrier for new suppliers entering Germany.
- Adoption of fungal protein in Japan is estimated to expand at 12.3% CAGR through 2036, aided by government-backed food-tech programs and local product development. Japan’s Ministry of Agriculture reported about 1,900 participants in its Food Tech Council as of June 2026.[11] The council includes companies, start-ups, research organizations and government agencies. This network can connect fermentation research with food manufacturers that understand local taste, naming and retail formats. Japanese buyers are likely to test fungal protein in products that already have familiar preparation and eating patterns. Due to this, local formulation work will remain as important as production technology when a supplier introduces a new fungal ingredient into the country.
- South Korea is estimated to post 8.9% CAGR over the forecast period, supported by a national policy structure for food technology. In July 2026, the Ministry of Agriculture, Food and Rural Affairs announced the country’s first statutory master plan for the food-tech industry.[12] The plan connects advanced technology development with wider adoption in the domestic food sector. Fungal protein can enter this system through fermentation research, ingredient development and finished-product testing. However, policy support does not remove approval requirements or the need for acceptable price and taste. Early demand is expected from technically prepared food companies, while wider adoption can follow after local products establish safety, sensory fit and stable supply.
- The fungal protein market in Switzerland is anticipated to grow at 8.2% CAGR between 2026 and 2036, linked to a structured route for novel foods. In August 2026, the Federal Food Safety and Veterinary Office updated its authorization guidance and identified foods produced from fungi as possible novel foods.[13] An application can require evidence for identity, production, toxicology, nutrition and allergenicity. This evidence requirement can slow entry when regulatory work begins after process development. At the same time, the defined route gives suppliers a clear list of records needed before customer trials. Suppliers entering Switzerland are therefore expected to establish legal status early and use accepted European evidence where national rules allow its use.
Who are the notable companies in the fungal protein market?
Notable companies include Cargill, Angel Yeast, Tate & Lyle, Corbion, Glanbia, Bunge, Archer Daniels Midland Company, and Kemin Industries.
Fungal protein market includes direct protein producers, fermentation companies and ingredient groups supporting finished-food development. Angel Yeast supplies dedicated yeast protein, while Cargill connects ABUNDA mycoprotein with feedstock and application work. Tate & Lyle, Corbion and Glanbia provide texture, stability and nutrition systems needed after fungal protein enters a recipe. Bunge, ADM and Kemin bring feedstock, animal nutrition or wider customer channels. FMI research indicates that buyers check organism identity, safety status, batch consistency, taste, available volume and technical support before selecting a supplier. Due to these separate roles, the market remains moderately fragmented instead of being controlled through one production model.
- Protein commercialization: Cargill and Angel Yeast connect fermentation output with customer access.
- Formulation systems: Tate & Lyle, Corbion, and Glanbia support finished-product texture, stability, and nutrition.
- Food, feed, and nutrition channels: Bunge, ADM, and Kemin connect ingredients with broader customer routes.
Competitive Benchmarking: Fungal Protein Market
| Company | Protein Access | Fermentation | Formulation | Reach |
|---|---|---|---|---|
| Tate & Lyle PLC | Low | Medium | High | High |
| Cargill, Incorporated | High | High | High | High |
| Angel Yeast Co., Ltd. | High | High | High | High |
| Corbion N.V. | Low | High | High | High |
| Glanbia plc | Low | Medium | High | High |
| Bunge Limited | Low | Medium | High | High |
| Archer Daniels Midland Company | Medium | High | High | High |
| Kemin Industries, Inc. | Medium | Medium | High | Medium |
High represents broad public evidence for the stated capability, Medium represents narrower documented activity, and Low represents limited direct breadth. These ratings describe company capability and do not indicate product quality, market share or company ranking.
Key Developments in the Fungal Protein Market
- In June 2026, The Protein Brewery announced European authorization for Fermotein under the EU Novel Food regulation.
- In March 2026, Enifer released its first commercial PEKILO mycoprotein batch for pet-food formulation trials.
- In November 2025, Angel Yeast started an 11,000-ton annual high-purity yeast protein production line.
Key Players in the Fungal Protein Market
Protein Commercialization and Fermentation
- Cargill, Incorporated
- Angel Yeast Co., Ltd.
- Archer Daniels Midland Company
Food Formulation and Nutrition Systems
- Tate & Lyle PLC
- Corbion N.V.
- Glanbia plc
Food, Feed, and Nutrition Channels
- Bunge Limited
- Kemin Industries, Inc.
Fungal Protein Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Source; End Use Application; Region. |
| Quantitative units | USD million. |
| Market definition | Revenue from fungal protein ingredients sold within the listed source and application categories. Finished foods and adjacent proteins are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa. |
| Countries covered | USA, UK, Germany, Japan, South Korea, Switzerland, and additional countries in the full report. |
| Forecast period | 2026 to 2036. |
| Approach | The Future Market Insights report covers ingredient supply, application qualification, segment structure, and country adoption conditions. |
Fungal Protein Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered inputs from manufacturers, technology developers, distributors, end users, procurement teams and industry experts. The discussions covered purchasing decisions, product trials, approval barriers, pricing and technical support required before regular orders begin. |
| Desk Research | Desk research includes government publications, regulator documents, trade data, industry associations, technical literature, company filings, product information and official announcements. Sources are considered according to their date, geography and direct relevance to the defined fungal protein market. |
| Market Sizing and Forecasting | Market sizing combines the values with historical performance, segment structure, pricing and volume indicators, company participation and country demand. Forecast assumptions consider regulatory changes, production availability, application trials and barriers affecting wider commercial use. |
| Data Validation | Market estimates are checked against public data, company activity, trade patterns, industry developments and primary inputs. Finished foods, adjacent protein categories, overlapping revenue and unsupported claims are excluded from the defined market boundary. |
Fungal Protein Market by Segments
Fungal Protein Market segmented by Source:
- Yeast
- Baker’s yeast
- Fusarium venenatum
- Brewer’s yeast
- Mushroom
Fungal Protein Market segmented by End Use Application:
- Food and beverage
- Processed food
- Animal nutrition
- Dairy
- Pet food
- Bakery
- Pharmaceuticals
- Aquaculture
Fungal Protein Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] The Protein Brewery. (2026, June 17). Fermotein authorized to sell in EU.
- [2] U.S. Food and Drug Administration. (2026, August 10). Generally Recognized as Safe (GRAS).
- [3] Angel Yeast Co., Ltd. (2025, November 4). Angel Yeast starts operating new 11,000-ton yeast protein production line.
- [4] Quorn Foods. (2026, April 29). Quorn launches Lemon & Pepper Schnitzels.
- [5] Food Standards Agency. (2026, June 25). Top emerging UK food innovations: 2025-2035.
- [6] European Food Safety Authority. (2025, December 1). Safety of Rhizomucor pusillus biomass powder as a novel food.
- [7] Enifer. (2026, March). First commercial PEKILO mycoprotein batch for pet-food development.
- [8] U.S. Food and Drug Administration. (2024, July 11). Agency Response Letter GRAS Notice No. GRN 001117.
- [9] Food Standards Agency. (2026, June 25). Innovative Food Guidance Hub.
- [10] Federal Ministry of Food and Agriculture, Germany. (2024, October 17). BMEL grants funding for mycelium protein production from upcycled dairy sidestreams.
- [11] Ministry of Agriculture, Forestry and Fisheries, Japan. (2026). New business creation: Food tech.
- [12] Ministry of Agriculture, Food and Rural Affairs, Republic of Korea. (2026, July 20). S. Korea unveils master plan to integrate advanced technologies into the food sector.
- [13] Federal Food Safety and Veterinary Office, Switzerland. (2026, August 7). Authorisation of novel foods.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is fungal protein market worth during 2026?
- What value is fungal protein market projected by 2036?
- Which source holds notable fungal protein market share?
- Which application holds notable fungal protein market share?
- Which countries have notable fungal protein market growth?
- Which companies are notable in fungal protein market today?
Frequently Asked Questions
How large is the fungal protein market in 2026?
Future Market Insights estimates that the fungal protein market will be valued at USD 515.0 million in 2026. The market is projected to reach USD 1,387.6 million by 2036.
What CAGR is projected for fungal protein through 2036?
As per FMI, the fungal protein market is projected to grow at a 10.4% CAGR from 2026 to 2036. Growth is supported by commercial fermentation and broader food formulation trials.
Which source leads the fungal protein market during 2026?
Future Market Insights projects yeast to hold 37.8% of source demand in 2026. The segment benefits from established fermentation knowledge and dedicated protein capacity.
Which application holds a notable share during 2026?
FMI finds that food and beverage will hold 37.4% of end use application demand in 2026. Demand is supported by use in prepared foods, drinks, bakery, and nutrition products.
Which country has a notable fungal protein growth outlook?
Future Market Insights predicts the USA to register 12.7% CAGR from 2026 to 2036. Growth is supported by established ingredient pathways and a large food formulation base.
Who are the key companies in the fungal protein market?
Notable companies in the fungal protein market include Cargill, Angel Yeast, Tate & Lyle, Corbion, Glanbia, Bunge, ADM, and Kemin Industries. These companies focus on protein supply, fermentation, formulation, nutrition, and customer channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Source, 2026 to 2036
- Yeast
- Baker’s yeast
- Fusarium venenatum
- Brewer’s yeast
- Mushroom
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use Application, 2026 to 2036
- Food and beverage
- Processed food
- Animal nutrition
- Dairy
- Pet food
- Bakery
- Pharmaceuticals
- Aquaculture
- Y-o-Y Growth Trend Analysis By End Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Source
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By End Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By End Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Source
- By End Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tate & Lyle PLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill, Incorporated
- Angel Yeast Co., Ltd.
- Corbion N.V.
- Glanbia plc
- Bunge Limited
- Archer Daniels Midland Company
- Kemin Industries, Inc.
- Tate & Lyle PLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


