

- Market Size (2026)
- USD 4.0 Bn
- Forecast (2036)
- USD 6.4 Bn
- CAGR (2026 to 2036)
- 5.0%
How big is Wheat Protein Market in 2026?
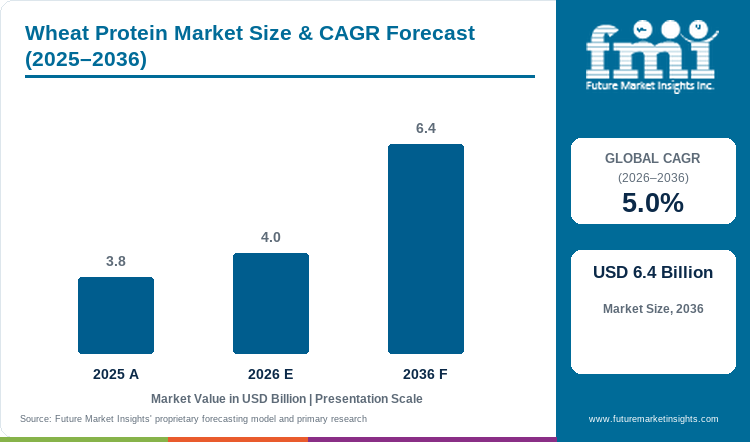
USD 4.0 Billion in 2026 and USD 6.4 Billion by 2036 at a 5.0% CAGR.
The wheat protein market is valued at USD 4.0 Billion in 2026 and is forecast to reach USD 6.4 Billion by 2036 at a 5.0% CAGR. Bakers use wheat protein to change dough strength and handling; makers of meat alternatives use it for structure. Nutrition products buy for protein content but must still meet serving and amino-acid targets. These are different briefs. A supplier earns a repeat order by showing how a grade performs at the required dose in the finished product.
The 2025 base is estimated at USD 3.8 Billion.
Grain quality and milling capacity shape input costs differently by country. Germany harvested 22.6 million tonnes of winter wheat in 2025, and official quality testing put average crude protein at 12.2%. Japan's March 2026 wheat outlook placed food-wheat demand at 5.60 million tonnes, with 4.61 million tonnes expected from foreign wheat. Canada also has a substantial milling base. These figures describe possible raw-material routes; they do not directly measure wheat-protein sales.
Key Takeaways
- Demand: Wheat protein supports both nutrition and processing. It can add protein while improving structure and hydration.
- Product Type: Wheat Gluten leads in 2026. Its viscoelastic network supports bakery and flour standardization as well as meat alternatives and selected feed uses.
- Form: Dry leads in 2026. Powder formats support bulk storage and standardized dosing while simplifying dry blending and long-distance distribution.
- Application: Nutrition Supplements leads in 2026. Isolates and hydrolysates give formulators concentrated protein with manageable dispersibility for powders and specialized nutrition.
- Friction: Wheat allergen labeling and gluten avoidance narrow the eligible consumer base. Protein quality and solubility can also slow switching when flavor or dose targets are difficult to meet.
- Companies: Archer Daniels Midland Company (ADM), Cargill, Roquette Freres; Tereos; MGP Ingredients; Agrana Beteiligungs-AG; Manildra Group; Kerry Group PLC; Sudzucker AG and Glico Nutrition Foods are the profiled market participants.
Analyst Perspective
The same wheat protein specification will behave differently in bread dough, a beverage and a meat alternative. Buyers should test the intended function and dose before judging offers on price per kilogram.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the wheat protein market segmented?
The wheat protein market is segmented by Product Type, Form, and Application.
Product Type comprises Wheat Gluten, Wheat Protein Isolate, Hydrolyzed Wheat Protein, and Textured Wheat Protein. Form comprises Dry and Liquid. Application comprises Nutrition Supplements, Bakery & Confectionery, Animal Feed, Dairy Products, Other Applications, and Cosmetics and Personal care.
What makes Wheat Gluten central to the Product Type category?
Wheat Gluten occupies the core functional position because hydrated glutenins and gliadins create a viscoelastic network that improves dough strength and water handling. Cargill documents use of vital wheat gluten in pasta and bakery products. It also lists flour milling plus cereals and plant-based meat alternatives. Its reach across process functionality and protein fortification gives buyers several reasons to specify the same ingredient family rather than treating it as a single-use protein.
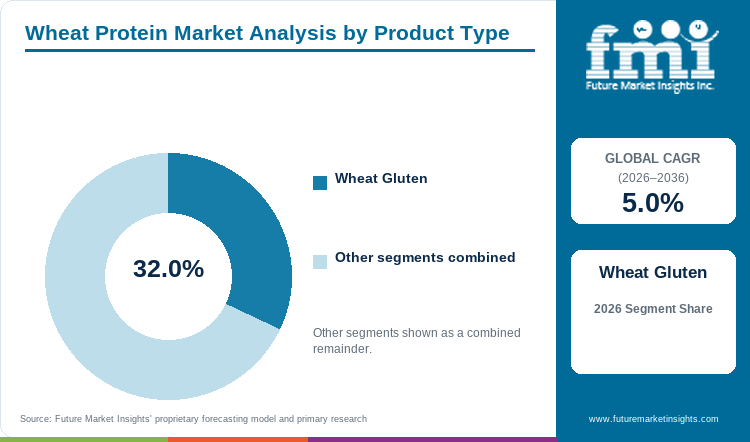
- Wheat Gluten holds a 32.0% share of Product Type revenue in 2026. Unlike a protein isolate selected chiefly for concentration, hydrated gluten builds a network that changes dough strength and water handling.
- Current wheat-protein portfolios from ADM, Cargill and Roquette offer different concentrations and functional properties. That breadth matters because a baker, beverage maker and meat-alternative producer will not qualify the same grade in the same way. Technical data and a dependable supply are more useful to a buyer than an old plant-capacity announcement.
Why does Dry remain the preferred Form?
Dry formats fit how industrial ingredient buyers store and transport proteins. They also simplify metering and blending. Powdered vital gluten can be added directly to flour systems, while dry hydrolysates and textured proteins can be rehydrated at the point of use. Cargill lists both vital wheat gluten and hydrolyzed wheat protein in powder form for health and sports nutrition. The format reduces dependence on liquid handling infrastructure and supports standardized concentration across shipments.
- Dry accounts for a 79.0% share of Form revenue in 2026. Bakery and supplement manufacturers can meter powder into existing dry blends; liquid formats require a separate handling and storage route.
- In July 2026, Glico Nutrition Foods Co., Ltd. announced a technical seminar covering spray-dried gluten and modified starch. The topic reflects continuing supplier attention to powder processing and the application knowledge required to use dry wheat proteins effectively.
What sustains Nutrition Supplements as the leading Application?
Nutrition Supplements benefit from concentrated wheat protein formats that can raise protein content without relying on animal-derived proteins. Hydrolysis can improve dispersibility and reduce viscosity, which matters in powders and beverage systems. The trade-off is formulation quality. Wheat protein has a different amino-acid profile from dairy proteins, so developers may use higher doses or blends when a specific nutritional performance target must be met.
- Nutrition Supplements hold a 35.0% share of Application revenue in 2026. Isolates and hydrolysates let a supplement formulator raise protein concentration, but dose and amino-acid targets still govern the final recipe.
- The relevant nutritional question is what the finished serving delivers. Wheat protein can add grams of protein, but its amino-acid profile, digestibility and dose need to be assessed for the intended consumer and claim. A formulation trial should also check flavor; solubility and texture. Those requirements are more useful for a 2026 purchasing decision than carrying forward an older clinical result from a different product and serving size.
What are the drivers, restraints and opportunities in the wheat protein market?
Functional versatility and protein enrichment support demand, while allergen constraints plus formulation thresholds restrict addressable use and differentiated wheat protein formats create higher-value opportunities.
- Driver: Multifunctional performance lets wheat protein serve both nutritional and process roles in bakery, supplements, and plant-based formulations.
- Restraint: Wheat allergen labeling, gluten avoidance, and application-specific protein quality can remove consumers or formulations from the addressable pool.
- Opportunity: Specialty formats can move suppliers beyond commodity gluten when they solve solubility or texture problems. Clean-label and processing benefits can also support a defensible cost-in-use.
The main driver is functional density: a buyer can purchase protein and processing performance in the same ingredient. Cargill describes vital wheat gluten as network-forming and water-holding. Manildra’s April 2025 GemPro Max work positioned wheat protein as a clean-label alternative to DATEM and SSL as well as mono- and diglycerides in bread. The commercial mechanism is strongest where the protein displaces another functional input or improves throughput while also supporting a protein claim. That raises the value of application support because purchasing teams evaluate total formulation economics rather than protein concentration alone.
Wheat is a major allergen under US labeling rules and gluten avoidance excludes many potential consumers. That makes the addressable product set narrower before a processor even tests texture or cost. For a nutrition product, grams of protein alone are insufficient: dose, amino-acid profile and claim support matter. A buyer should qualify the precise grade in the intended recipe and label rather than treating wheat protein as interchangeable with another source.
Roquette's June 2025 NUTRALYS T WHEAT 600L launch targets a specific job: a fibrous texture for plant-based foods, with more than 60% protein. Manildra lists organic hydrolyzed and isolate grades for other uses. These are different ingredients for different lines. A food maker will pay for a grade that solves a texture or nutrition problem at production scale; calling it wheat protein is only the start of the specification.
Which country CAGRs are profiled in the wheat protein market?
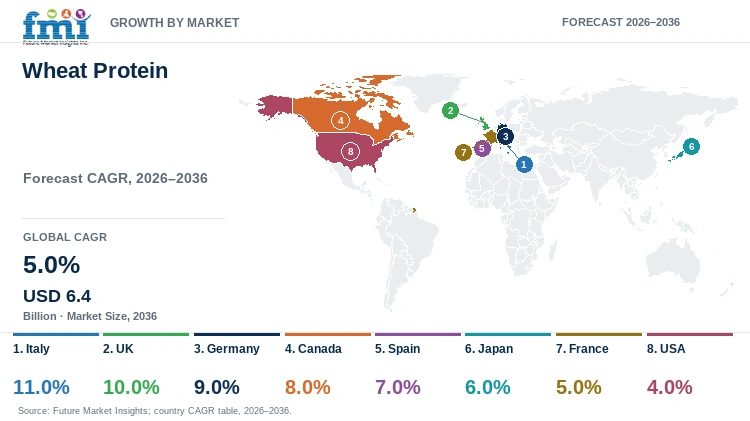
| Country | CAGR |
|---|---|
| Italy | 11.0% |
| UK | 10.0% |
| Germany | 9.0% |
| Canada | 8.0% |
| Spain | 7.0% |
| Japan | 6.0% |
| France | 5.0% |
| USA | 4.0% |
How do country-level CAGRs compare in the wheat protein market?
The profiled rates separate into three practical bands. Italy and the UK form the double-digit group. Germany and Canada occupy the upper single-digit band, while Spain and Japan join France and the USA in a more moderate band. The spread between the highest and lowest profiled rates is 7.0 percentage points.
- Italy: import dependence for wheat sits alongside a large food-processing base, making supply continuity and grade consistency central to specialty protein procurement.
- UK: recovering wheat output coexists with lower flour-milling use, so value-added ingredient adoption can advance even without broad grain-volume expansion.
- Germany: a strong 2025 winter-wheat harvest and improved average protein content support an established raw-material and processing base.
- Canada: Its 2025 wheat-milling base can support value-added fractions when processors can prove their function and cost.
- Spain: The 2025 food market remained price-sensitive, making cost-in-use and formulation performance central to a wheat-protein pitch.
- Japan: heavy reliance on imported food wheat makes specification control, sourcing continuity, and landed cost especially important.
- France: a large soft-wheat crop base supports domestic processing, although 2026 yield pressure shows the need to manage agricultural variability.
- USA: a mature wheat-food base and continued gluten-free preference pressure shift the growth case toward specialty functions and targeted nutrition uses.
Raw-material access, milling capacity, regulation and end-use mix shape suppliers’ route to revenue in each country.
Country-wise Analysis
- Italy has the fastest profiled expansion, at an 11.0% CAGR from 2026 to 2036. Its commercial case is shaped by a large wheat-using food industry and a structurally import-dependent grain balance. Istat reported in September 2026 that Italy imported about 97 million quintals of wheat in 2025 versus domestic production of roughly 59.5 million quintals. That gap increases exposure to international prices and quality variation. Wheat protein suppliers can therefore differentiate through consistent specifications and dependable delivery. Application support also matters in bakery and pasta-adjacent formulations as well as nutrition products and plant-based foods. The rate signals faster value creation, not the largest absolute market.
- The UK is profiled at 10.0% CAGR from 2026 to 2036. Defra reported a 2025 wheat harvest of just under 12 million tonnes. Flour milling, including bioethanol and starch uses, took 5.526 million tonnes with home-grown wheat making up 75% of the grist. These figures show a substantial cereal-processing base but they do not measure wheat-protein output. Suppliers seeking higher-value uses must show a functional gain in bakery or textured foods and meet allergen-labeling requirements.
- Germany carries a 9.0% CAGR from 2026 to 2036 and has a large wheat-processing base. The German Federal Statistical Office reported 22.6 million tonnes of winter wheat in 2025; a separate official quality update put average crude protein in common winter wheat at 12.2%. These are raw-material indicators, not wheat-protein ingredient output. Conversion economics still depend on wet-milling yield, energy use and the specifications a food customer requires.
- Canada carries an 8.0% CAGR in the 2026 to 2036 outlook. Statistics Canada reported that millers processed 3.4 million tonnes of wheat and produced 2.7 million tonnes of flour in 2025. That processing base can support specialty fractions, although the figures do not identify protein-ingredient tonnes. A customer will still choose on concentration, handling and repeatable performance. Wheat's priority-allergen status also sets a clear labeling boundary.
- Spain is profiled at 7.0% CAGR from 2026 to 2036. The agriculture ministry reported 2025 food and beverage consumption data in July 2026, showing that shoppers remained sensitive to price. Wheat protein can add value in bakery, bars or textured foods when it improves the recipe at a workable cost. Suppliers should show that benefit in a finished product with allergen information clear on the label.
- Japan is profiled at a 6.0% CAGR from 2026 to 2036, with sourcing structure acting as a major commercial condition. In March 2026, Japan’s Ministry of Agriculture placed food-wheat demand at 5.60 million tonnes for fiscal 2026. Domestic food-wheat circulation was forecast at 0.93 million tonnes while foreign wheat demand was 4.61 million tonnes and planned imports were 4.62 million tonnes. That dependence raises the value of predictable quality and procurement continuity. Glico Nutrition’s broad functional gluten range also shows the importance of application-specific texture in noodles and bakery. Suppliers must combine technical fit with disciplined landed-cost and allergen management.
- France has a 5.0% CAGR from 2026 to 2036. Agreste estimated in July 2026 that soft-wheat production would reach 32.0 million tonnes, down 4% from the 2025 campaign because lower yields offset larger planted area. The country therefore retains substantial raw-material scale while still facing crop variability. That base supports integrated starch and protein processing, including companies with European wheat assets. The growth path is likely to favor higher-value grades and plant-based texture systems rather than simple expansion of commodity gluten. Buyers will prioritize reliable technical performance and price stability because finished food manufacturers can switch among several protein sources when a wheat-specific functional advantage is not clear.
- The USA has the most moderate profiled rate, at 4.0% CAGR from 2026 to 2036. USDA ERS estimated 126.6 pounds of wheat flour use per person in 2025. This is a mature cereal market, so added value is likely to come from specific functions such as dough performance or texture in prepared foods. A supplier has to show that the ingredient fits the product's price and label; wheat allergy and gluten avoidance limit where it can be used.
Who are the notable companies in the wheat protein market?
Archer Daniels Midland Company (ADM), Cargill, Roquette Freres; Tereos; MGP Ingredients; Agrana Beteiligungs-AG; Manildra Group; Kerry Group PLC; Sudzucker AG and Glico Nutrition Foods are the notable companies profiled in this market.
Competition spans integrated grain processors; specialized plant-protein suppliers and application-led ingredient businesses. Cargill; Tereos; Agrana Beteiligungs-AG; Manildra Group and Sudzucker AG connect wheat protein to starch; grain or fermentation assets. MGP Ingredients, Inc. offers concentrates and isolates. Its portfolio also includes hydrolyzed and texturized wheat proteins. Roquette Freres has expanded its specialty plant-protein portfolio into textured wheat. ADM participates through wheat protein concentrates and broader nutrition capabilities. Kerry Group PLC supplies wheat-sourced textured plant protein through TexFlex while Glico Nutrition Foods Co., Ltd. offers a broad set of functional wheat gluten grades for Japanese and international food applications. Competitive advantage therefore rests on process integration and specialty functionality. Formulation support and geographic supply reach create additional differentiation.
- Integrated wheat-processing platforms: Archer Daniels Midland Company (ADM), Cargill, Incorporated; Tereos; Agrana Beteiligungs-AG; Manildra Group and Sudzucker AG connect wheat protein to larger grain; starch; milling or fermentation systems.
- Specialty protein and application systems: Roquette Freres, MGP Ingredients, Inc. and Kerry Group PLC compete through differentiated specialty formats. Their documented offers include hydrolyzed and textured proteins plus formulation-oriented solutions.
- Japan-focused functional gluten platform: Glico Nutrition Foods Co., Ltd. documents a diverse family of vital and functional wheat gluten grades. Its applications include noodles and bakery products as well as meat and fish-paste systems.
Competitive Benchmarking: Wheat Protein Market
| Company | Wheat Protein Portfolio Breadth | Specialty Functionality | Integrated Wheat Processing | Geographic Reach |
|---|---|---|---|---|
| Archer Daniels Midland Company (ADM) | Medium | Medium | High | North America, Europe, and Asia-Pacific |
| Cargill, Incorporated | High | High | High | North America, Europe, and global customer channels |
| Roquette Freres | Medium | High | Medium | Europe, North America, and Asia |
| Tereos | High | High | High | Europe with additional international processing reach |
| MGP Ingredients, Inc. | High | High | High | United States; broader reach supported through ingredient sales |
| Agrana Beteiligungs-AG | Medium | Medium | High | Central and Eastern Europe with selected U.S. exposure |
| Manildra Group | High | High | High | Australia, United States, and export markets |
| Kerry Group PLC | Medium | High | Low | Global group footprint; wheat-specific manufacturing reach is less disclosed |
| Sudzucker AG | Medium | Medium | High | Europe with BENEO and CropEnergies distribution |
| Glico Nutrition Foods Co., Ltd. | High | High | Low | Japan with international food-ingredient customers |
Scoring basis: Wheat Protein Portfolio Breadth is High when public evidence shows several relevant wheat protein formats; Medium denotes narrower coverage; Low requires a documented limitation. Specialty Functionality is High when a supplier documents differentiated specialty performance across several formats or applications; Medium denotes a narrower specialty set; Low requires a documented limitation. Integrated Wheat Processing is High when direct grain or starch processing is documented; Medium indicates narrower integration; Low requires a verified limitation.
Key Developments in the Wheat Protein Market
- In June 2025, Roquette Freres launched NUTRALYS T WHEAT 600L, its first textured wheat protein. The ingredient contains more than 60% protein and is designed to produce extended meat-like fibers. Roquette also positioned it for simpler processing than high-moisture extrusion; adding a differentiated route into plant-based and hybrid meat formulations.
- In July 2026, Manildra Group added GemPro Shine to its U.S. product archive. The wheat protein solution is water-dispersible and intended as a pre-bake coating that creates a glossy finish on breads and pastries. The launch extends wheat protein into a visible surface-function role rather than treating the ingredient only as structural or nutritional protein.
- In May 2026, Agrana Beteiligungs-AG published its 2025/26 annual report and disclosed increased bagging capacity for wheat starch and gluten at Pischelsdorf, Austria. The investment targets handling capacity around an integrated wheat-processing site; supporting supplier responsiveness and shipment flexibility for food and feed customers.
Key Players in the Wheat Protein Market
Integrated wheat-processing platforms
- Archer Daniels Midland Company (ADM)
- Cargill, Incorporated
- Tereos
- Agrana Beteiligungs-AG
- Manildra Group
- Sudzucker AG
Specialty protein and application-system suppliers
- Roquette Freres
- MGP Ingredients, Inc.
- Kerry Group PLC
Japan-focused functional gluten platform
- Glico Nutrition Foods Co., Ltd.
Wheat Protein Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Form; Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from Wheat Gluten, Wheat Protein Isolate, Hydrolyzed Wheat Protein, and Textured Wheat Protein sold as ingredients within the stated Form and Application universe is included. Downstream finished-product revenue, substitute proteins, starch-only revenue, and adjacent products are excluded; where bundled, only attributable wheat protein ingredient revenue is in scope. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; Germany; UK; France; Italy; Spain; Japan; Canada |
| Key Companies Profiled | Archer Daniels Midland Company (ADM); Cargill, Incorporated; Roquette Freres; Tereos; MGP Ingredients, Inc.; Agrana Beteiligungs-AG; Manildra Group; Kerry Group PLC; Sudzucker AG; Glico Nutrition Foods Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Recent crop and milling series separated from FMI wheat-protein forecasts. |
Wheat Protein Market - Research Methodology
| Method | Approach |
|---|---|
| Market Scope | The scope covers wheat protein used for functional or nutritional purposes, including dough and textured-food applications. Wheat grain and flour statistics are input context. |
| Public Evidence | The report uses 2025 crop and milling series, current supplier ranges and allergen rules. Older clinical findings were removed rather than transferred to present-day formulations. |
| Forecast Interpretation | The USD market values and 2026-2036 CAGRs are FMI forecasts. Wheat harvests do not reveal the output of isolated protein ingredients. |
| Source Checks | Raw-material data were distinguished from ingredient production. Product claims were checked for dose, function and wheat or gluten labeling boundaries. |
Wheat Protein Market by Segments
Wheat Protein Market segmented by Product Type
- Wheat Gluten
- Wheat Protein Isolate
- Hydrolyzed Wheat Protein
- Textured Wheat Protein
Wheat Protein Market segmented by Form
- Dry
- Liquid
Wheat Protein Market segmented by Application
- Nutrition Supplements
- Bakery & Confectionery
- Animal Feed
- Dairy Products
- Other Applications
- Cosmetics and Personal care
Wheat Protein Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- U.S. Department of Agriculture, Economic Research Service (2026, April 8). Wheat - Wheat Sector at a Glance.
- U.S. Food and Drug Administration (n.d.). What is a “major food allergen”?.
- Cargill, Incorporated (n.d.). Gluvital® vital wheat gluten.
- Cargill, Incorporated (n.d.). Plant protein for Health & Sports nutrition.
- Roquette Freres (2025, June 17). NUTRALYS® Portfolio: New Textured Wheat and Pea Proteins.
- Roquette Freres (n.d.). NUTRALYS® W.
- Istituto Nazionale di Statistica (Istat) (2026, September 4). Produzioni agricole e zootecniche - Anno 2025.
- Department for Environment, Food & Rural Affairs (2026, September 3). Chapter 7: Crops.
- German Federal Statistical Office (n.d.). 2025 grain and potato harvest: 45 million tons of grain and 14 million tons of potatoes.
- German Federal Statistical Office (n.d.). Bread grain harvest 2025: Protein content of common winter wheat increases compared to previous year.
- Statistics Canada (2026, May 13). Milled wheat and wheat flour produced, Canada and United States; 2025.
- Ministry of Agriculture, Fisheries and Food of Spain (2026, July 30). El consumo alimentario crece por primera vez en cinco años y roza los 30.800 millones de kilos.
- Ministry of Agriculture, Forestry and Fisheries of Japan (2026, March 23). Food; Agriculture and Rural Policy Council Food Subcommittee minutes.
- Agreste, French Ministry of Agriculture (2026, July 15). Grandes cultures. Recul attendu des récoltes de blé tendre et d’orges du fait de rendements en baisse.
- Manildra Group USA (2025, April 23). A new approach to emulsification in bakery.
- Manildra Group USA (2026, July 7). Products Archive - GemPro® Shine.
- Manildra Group USA (2025, May 22). Products Archive - Organic GemPro® Ultra and Organic GemPro® Prime-W.
- MGP Ingredients, Inc. (2025, January 31). MGP Names President; Ingredient Solutions.
- MGP Ingredients, Inc. (n.d.). Food FAQ.
- AGRANA Beteiligungs-AG (2026, May 12). Annual Report 2025|26 - ACS Starch segment.
- AGRANA Beteiligungs-AG (n.d.). Vital Wheat Gluten.
- Tereos (n.d.). Wheat.
- Kerry Group PLC (n.d.). Textured Plant Protein.
- CropEnergies AG (n.d.). Wheat gluten - protein in demand.
- Glico Nutrition Foods Co., Ltd. (n.d.). Wheat Protein.
- Glico Nutrition Foods Co., Ltd. (n.d.). Our History.
- Glico Nutrition Foods Co., Ltd. (2026, July 1). Glico Nutrition news: online seminar on spray-dried gluten and modified starch.
- UK Department for Environment, Food and Rural Affairs (2026, September 3). Agriculture in the United Kingdom 2025; Chapter 7: Crops.
- UK Defra, September 2026 report on 2025 crops
This Report Answers
- How large is the Wheat Protein Market in 2026 and what value is forecast for 2036?
- Which industry pressures and formulation needs support demand for wheat protein?
- Why does Wheat Gluten hold the leading position within Product Type?
- Why does Dry hold the leading position within Form?
- How do growth rates differ across Italy, UK, Germany; Canada; Spain; Japan; France and USA?
- Which profiled companies supply relevant wheat protein and application-system categories?
- What limits adoption or slows supplier switching in wheat protein formulations?
- What should buyers evaluate before purchasing a wheat protein ingredient?
Frequently Asked Questions
How big is the Wheat Protein Market in 2026, and what is forecast for 2036?
The market is valued at USD 4.0 Billion in 2026 and is forecast to reach USD 6.4 Billion by 2036. The increase reflects broader use of wheat protein across nutrition and functional food systems rather than a single end-use expansion.
What is the CAGR for the Wheat Protein Market from 2026 to 2036?
The market is forecast to expand at a 5.0% CAGR from 2026 to 2036. Revenue realization depends on meeting formulation and allergen requirements while maintaining quality and supply reliability at an acceptable cost-in-use.
Which Product Type segment leads the Wheat Protein Market?
Wheat Gluten leads Product Type in 2026. Its position reflects established use in viscoelastic structure and protein standardization. Binding and texture control add further value.
Which Form segment leads the Wheat Protein Market?
Dry leads Form in 2026. Powder handling supports bulk storage and standardized dosing. It also simplifies dry blending and broad distribution across industrial applications.
Which profiled countries have the highest growth rates in the Wheat Protein Market?
Italy has the highest profiled CAGR at 11.0%, followed by the UK at 10.0% and Germany at 9.0% from 2026 to 2036. These rates describe expected growth momentum and do not establish absolute country market size.
Which companies are active in the Wheat Protein Market?
Profiled market participants are Archer Daniels Midland Company (ADM), Cargill, Roquette Freres; Tereos; MGP Ingredients; Agrana Beteiligungs-AG; Manildra Group; Kerry Group PLC; Sudzucker AG and Glico Nutrition Foods Their roles differ across integrated processing and specialty protein formats. Texturization and application support create further distinctions.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Wheat Gluten
- Wheat Protein Isolate
- Hydrolyzed Wheat Protein
- Textured Wheat Protein
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Dry
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Nutrition Supplements
- Bakery & Confectionery
- Animal Feed
- Dairy Products
- Other Applications
- Cosmetics and Personal care
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Form
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Form
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Archer Daniels Midland Company (ADM)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill, Incorporated
- Roquette Freres
- Tereos
- MGP Ingredients, Inc.
- Agrana Beteiligungs-AG
- Manildra Group
- Kerry Group PLC
- Sudzucker AG
- Glico Nutrition Foods Co., Ltd.
- Archer Daniels Midland Company (ADM)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


