

- Market Size (2026)
- USD 2.0 Bn
- Forecast (2036)
- USD 3.2 Bn
- CAGR (2026 to 2036)
- 4.7%
How big is Industrial Water Cooling System Market in 2026?
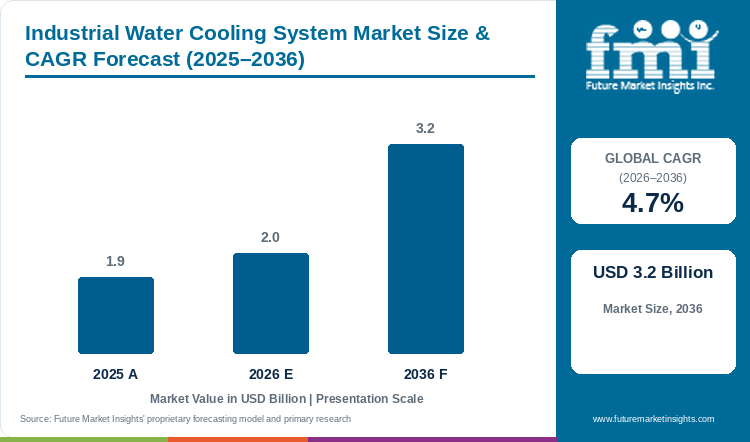
Demand is projected to expand at 4.7% CAGR from 2026 to 2036. Market value rises from USD 1.9 billion in 2025 to USD 2 billion in 2026 and USD 3.2 billion by 2036.
The global industrial water cooling system market covers cooling equipment and arrangements serving petrochemicals, pharmaceuticals, power generation, metalworking, and food and beverage processes. The market is valued at USD 1.9 billion in 2025 and USD 2 billion in 2026, with a forecast of USD 3.2 billion by 2036 and a CAGR of 4.7% from 2026 to 2036. Dry cooling represents an estimated 16.0% of the product-type breakdown in 2026, while petrochemicals accounts for 17.1% of application demand. System choice depends on the process heat load, ambient conditions and the site's balance of water and energy requirements.
New industrial capacity supports equipment orders alongside retrofits addressing specific limitations in operating plants. A February 2025 DOE project determination describes larger blowdown piping, a motor-operated valve and an additional control input at one cooling-water installation. [1] Continuing system management also connects treatment with monitoring and maintenance: CDC's January 2025 cooling-tower guidance includes automated dosing and blowdown measures. [2] EPA's industrial reuse resources address alternative water supplies and their treatment and permitting considerations. [3] These developments expand the relevant equipment scope beyond the heat-rejection unit to the water circuit and its controls.
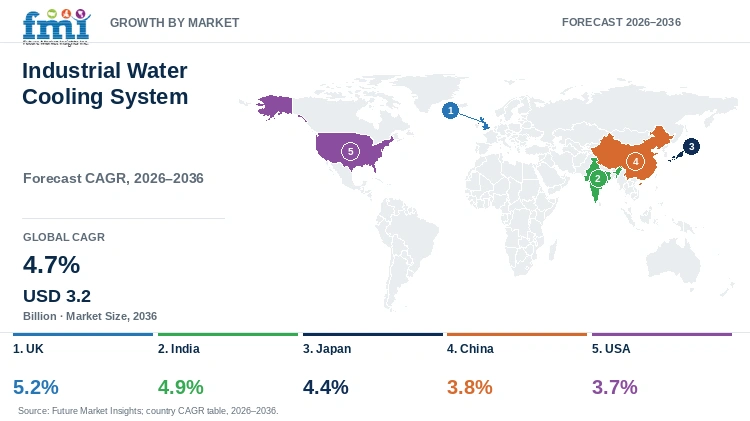
The UK has the highest profiled growth estimate at 5.2% CAGR for 2026 to 2036, followed by India at 4.9%, Japan at 4.4%, China at 3.8% and the USA at 3.7%. An operating equipment base supports continuing management and retrofit work. Slough's May 2025 register, for example, lists 16 premises with 241 notifiable cooling towers or evaporative condensers, providing a local view of this service setting. [4]
Representative suppliers include IWC (Pty) Ltd., Cold Shot Chillers, Thermal Care, Parker Hannifin Corporation and ThermoTek Inc. Their offers range across industrial cooling systems, chillers and thermal-management equipment or components. Competition depends on delivering the required thermal duty under actual site conditions, with water treatment, piping and control interfaces defined. For retrofits, maintainability and installation within the available shutdown window add practical points of differentiation.
Key Market Trends & Insights
- Retrofits can target blowdown and control limitations within an existing plant, illustrated by a February 2025 DOE project determination. [1]
- Cooling-tower management connects water treatment, monitoring and maintenance; CDC's January 2025 guidance describes this operating scope. [2]
- Alternative cooling-water sources require a suitable treatment and permitting assessment; EPA's October 2026 resource hub addresses industrial reuse. [3]
Regional Highlights
- The UK has the highest profiled FMI growth estimate, at 5.2% for 2026 to 2036, followed by India at 4.9%.
- Japan, China and USA profiles are 4.4%, 3.8% and 3.7% for the same period.
- Slough's May 2025 register lists 16 premises with 241 notifiable cooling towers or evaporative condensers; this is a local installed-base record. [4]
Market Size & Forecast
Table 1: Market Size and Forecast for Industrial Water Cooling System Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 1.9 billion |
| 2026 market value | USD 2 billion |
| 2036 market value | USD 3.2 billion |
| CAGR 2026 to 2036 | 4.7% |
| Revenue increase 2026 to 2036 | USD 1.2 billion |
| Market expansion 2026 to 2036 | 1.60 times |
Demand comes from new process capacity and the needs of operating installations, where pumps, exchangers, controls or water-management equipment may need attention at different times. A purchaser comparing replacement and retrofit options needs the relevant thermal duty and site constraints established first. The cost of water, treatment, energy and a production interruption can affect the preferred scope. Suppliers consequently need an offer that explains what will change at the site, which existing components remain in service and how the new arrangement will be commissioned and maintained.
The Industrial Cooling Systems Market provides broader related coverage of thermal equipment purchased for industrial processes and plant support.
Water management can determine the scope of an industrial cooling retrofit
Heat rejection and water management are connected in evaporative systems, but they are different purchasing questions. A plant may have enough nominal cooling capacity while its blowdown arrangement or treatment controls restrict reliable operation. The DOE project record provides a concrete example of work on that interface. [1] CDC guidance addresses the continuing management of cooling towers, while EPA's industrial reuse resources identify water-supply and permitting considerations. [2][3] Together these sources support an application-level assessment. They do not establish a universal saving from automation or a common replacement interval across all industrial sites.
Table 2: Industry evidence relevant to the industrial water cooling system market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Blowdown retrofit | DOE documented a larger blowdown pipe, motor-operated valve and control input in February 2025. | Existing cooling equipment can create a targeted piping and controls requirement. | [1] |
| Tower operating guidance | CDC's module dated 3 January 2025 recommends automated dosing, monitoring and blowdown among its management measures. | Treatment and controls belong within the operating and maintenance assessment. | [2] |
| Local installed base | Slough recorded 16 premises and 241 notifiable towers or evaporative condensers as of 19 May 2025. | An installed-base register identifies a specific service setting, not annual sales. | [4] |
Analyst Perspective
“An effective cooling proposal begins with the process duty and the site's operating constraints. The customer needs the thermal equipment, water-management controls and maintenance scope assessed together, because a weak interface can limit the usable performance of a plant whose individual components appear adequately rated.”
- Nikhil Kaitwade, Future Market Insights
The commercial case improves when the buyer can compare the complete operating arrangement and the work required during the available shutdown window.
How is the Industrial Water Cooling System Market segmented?
The market is segmented by Product Type, Application, and Region.
The product-type taxonomy includes dry, wet and hybrid cooling, towers, condensers, chillers and heat exchangers. These categories describe different equipment arrangements within the report's cooling-system coverage. Application identifies the industrial process using the equipment. The two charted shares retain the published 2026 reference year and belong to separate breakdowns. A site's technology choice follows its heat load, temperature conditions, water supply and operating constraints. Equipment suitable for one circuit can require a different installation and service scope when proposed as a replacement in another plant.
What supports dry cooling in the product-type comparison?
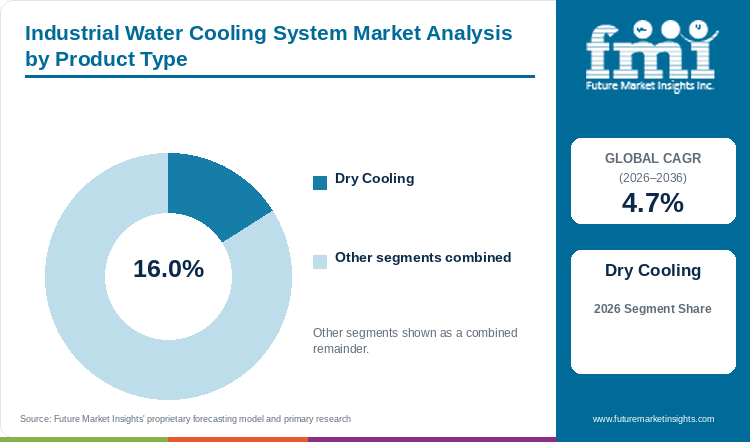
Table 3: Product Type Share for Industrial Water Cooling System Market (percentage share), 2026
| Product Type | Estimated share (2026) |
|---|---|
| Dry Cooling | 16.0% |
| Other product types | 84.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Industrial Water Cooling System Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.7% |
| Profiled product type segment | Dry Cooling |
Dry cooling represents an estimated 16.0% of the published product-type breakdown in 2026. Its purchasing relevance comes from the way a site balances heat rejection with water and energy constraints. The equipment still needs to deliver the process duty under the relevant ambient and operating conditions, so a water-use preference alone is not a complete specification. A buyer comparing dry and other cooling arrangements needs the same temperature requirement and operating profile across bids. Installation space, sound and the connected pump or fan duty can also affect the complete project. The market taxonomy places dry cooling within a broader system comparison; it does not imply that every water-cooled process can change technology without a fresh thermal and installation assessment.
The Dry Cooling segment is estimated to account for 16.0% of product type demand in 2026.
- Dry cooling represents an estimated 16.0% of product-type demand in 2026; other product types together represent 84.0%.
- The comparison needs a common process temperature duty and ambient operating conditions.
Why is petrochemicals the leading published application benchmark?
Table 5: Application Share for Industrial Water Cooling System Market (percentage share), 2026
| Application | Estimated share (2026) |
|---|---|
| Petrochemicals | 17.1% |
| Other applications | 82.9% |
| Total | 100.0% |
Petrochemicals represents an estimated 17.1% of application demand in 2026. A process facility needs its cooling system to support the temperature conditions of connected equipment, making reliability and maintainability central to procurement. The owner also needs to consider the cooling-water circuit and treatment arrangement when assessing a change to thermal equipment. A targeted retrofit can address a valve, pipe or control limitation without replacing the whole plant, as the DOE blowdown project illustrates in a different industrial setting. [1] For petrochemical purchasers, the useful comparison is therefore application-specific: the proposed scope must fit the process duty and the installation responsibilities. A supplier can strengthen the offer by explaining how the equipment will be maintained and how the work fits the site's available shutdown programme.
The Petrochemicals segment is estimated to account for 17.1% of application demand in 2026.
- Petrochemicals represents an estimated 17.1% of application demand in 2026; other applications together represent 82.9%.
- The process duty, treatment arrangement and shutdown schedule affect the preferred equipment and service scope.
- Water treatment is a connected operating requirement in many circuits. The Water Treatment System Market provides related coverage of equipment managing water quality.
What are the drivers, restraints, and opportunities in the Industrial Water Cooling System Market?
Industrial capacity and installed-system needs support demand; thermal, water and material constraints limit substitution; measured operating data and a defined retrofit scope improve the purchasing case.
Driver
New industrial capacity creates cooling requirements, while operating facilities generate replacement and retrofit work as their thermal duties or equipment condition change. The resulting purchase can range from a complete cooling package to a specific water-management improvement. DOE's February 2025 determination identifies an undersized blowdown line and additional control work at an existing installation. [1] That is a project-specific example of demand arising within an installed system. Suppliers need to establish which constraint the customer is resolving and then price the equipment and interfaces required to address it, including the work that must be completed during a maintenance window.
Restraint
A cooling-system change can affect energy use, water quality and the equipment it serves. Those interactions limit the value of comparing nominal capacity alone. An alternative water source may also need additional treatment or a different permitting assessment. EPA's industrial reuse hub identifies variation in the uses authorised by US states and points to resources on cooling-water supply. [3] Buyers therefore need a realistic operating and water-quality baseline before accepting a water-saving or cost claim. A proposal must also account for the existing piping, controls and materials, since their modification can alter both installation cost and production downtime. The useful comparison includes those site responsibilities as well as the new equipment.
Opportunity
Suppliers can make a stronger customer case by combining measured operating conditions with a defined retrofit or replacement scope. That includes accessible flow and water-quality information, appropriate controls and a service arrangement that the owner can maintain. CDC's cooling-tower guidance places automated monitoring and blowdown within continuing system management. [2] Such measures need to be assessed for the actual installation rather than offered as an identical package to every plant. The opportunity also extends to the installed base: a local register such as Slough's identifies equipment requiring ongoing management, although it does not determine when each unit will be replaced. [4]
The Produced Water Treatment Market covers a separate industrial water source and treatment setting; its process requirements should remain distinct from those of an ordinary cooling circuit.
Which country CAGRs are profiled in the Industrial Water Cooling System Market?
Table 6: Country CAGR Comparison for Industrial Water Cooling System Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| UK | 5.2% |
| India | 4.9% |
| Japan | 4.4% |
| China | 3.8% |
| USA | 3.7% |
Country-wise Analysis
UK Industrial Water Cooling System Market Outlook (2026 to 2036)
Slough's cooling-tower register provides a specific view of an operating equipment base, listing 16 premises with 241 notifiable towers or evaporative condensers as of May 2025. [4] It is a local record rather than a national market-size measure. The installed base creates a continuing assessment task for owners: thermal performance, treatment and controls need to remain suited to the site. A supplier considering service or replacement opportunities needs the actual condition and duty of each installation. A clear proposal distinguishes the equipment that will be changed from the supporting components retained, allowing the owner to compare the complete job and the time required to carry it out.
India Industrial Water Cooling System Market Outlook (2026 to 2036)
A new process line can create a cooling-equipment order, but its operating needs determine whether the purchase is a standalone unit or a broader system package. Buyers need the design heat load, temperature range and available water conditions established before comparing products. A retrofit adds another constraint because existing pumps, pipes and controls may remain in place. Suppliers can make those interfaces visible by stating the installation work and service responsibilities included in the price. The commercial opportunity is application-specific: an equipment rating becomes useful only when it can be delivered under the site's expected operating conditions and maintained within the owner's production schedule.
Japan Industrial Water Cooling System Market Outlook (2026 to 2036)
Reliability at the process interface is central to a Japanese industrial cooling purchase. A unit needs to deliver the required thermal duty while fitting the plant's controls and maintenance practices. For an existing installation, the buyer needs to decide whether a performance limitation belongs to the heat-rejection equipment, the water circuit or a particular control arrangement. That diagnosis changes the purchasing scope. Suppliers can therefore improve the comparison through a proposal that identifies the assumed operating conditions and the components that must be modified. The owner can then assess equipment cost together with service access and the interruption required for installation, rather than choose between unmatched nominal-capacity quotations.
China Industrial Water Cooling System Market Outlook (2026 to 2036)
Industrial cooling demand in China needs to be assessed through the process and site using the equipment. FMI's published growth estimate is 3.8% for 2026 to 2036. A large thermal load does not determine a single technology choice because ambient conditions, water availability and the existing circuit can point to different configurations. A buyer comparing alternatives needs the same duty and system boundary in each proposal. The quotation should also distinguish equipment supply from the piping, control and commissioning work required to put it into service. This is particularly useful when a site expands in stages and retains some existing components. Suppliers that resolve those interfaces early can give the owner a clearer view of the operating and delivery responsibilities attached to the purchase.
USA Industrial Water Cooling System Market Outlook (2026 to 2036)
DOE's February 2025 project determination documents a targeted cooling-water retrofit: larger blowdown piping, a motor-operated valve and a new control input were proposed to improve flow and reduce manual operation. [1] The record is not a contract award or a completed-installation result. It nevertheless shows how an existing system can generate a specific equipment and integration requirement. Purchasers need to establish the constraint being addressed before selecting the scope. Cooling-tower operation also requires continuing management, as CDC's January 2025 guidance describes. [2] Suppliers can support that assessment by connecting the proposed hardware with the controls, treatment and maintenance responsibilities needed to keep the system usable.
Who are the notable companies in the Industrial Water Cooling System Market?
IWC (Pty) Ltd.; Cold Shot Chillers; Thermal Care; Parker Hannifin Corporation; ThermoTek Inc.
The market coverage identifies IWC, Cold Shot Chillers, Thermal Care, Parker Hannifin and ThermoTek among representative participants. Their relevant offers need to be compared against the same process duty and site conditions. A cooling-system supplier and a component provider can have different responsibilities within a project, so the quotation must identify the actual scope. The comparison below focuses on thermal performance, integration and service requirements that a purchaser needs to resolve. It keeps a representative product area distinct from the suitability of any particular model for the proposed installation.
Competitive Benchmarking: Industrial Water Cooling System Market
Table 7: Competitive positioning for the industrial water cooling system market
| Company | Positioning | Buyer comparison focus |
|---|---|---|
| IWC (Pty) Ltd. | Industrial cooling systems | Compare the proposed heat-rejection duty and the site integration scope. |
| Cold Shot Chillers | Industrial chillers | Assess the chiller rating against process temperature and operating conditions. |
| Thermal Care | Process cooling equipment | Clarify the equipment, water circuit and controls included in the package. |
| Parker Hannifin Corporation | Thermal-management components and systems | Define the relevant thermal component and interface responsibilities in the offer. |
| ThermoTek Inc. | Thermal-management equipment | Check the equipment duty, service access and support arrangement for the application. |
Key Developments in the Industrial Water Cooling System Market
- DOE documented a cooling-water blowdown modification in February 2025. [1]
- CDC's cooling-tower management module is dated January 2025. [2]
- Slough's public cooling register provides a May 2025 installed-base snapshot. [4]
Key Players in the Industrial Water Cooling System Market
Industrial cooling systems
- IWC (Pty) Ltd.
Industrial chillers
- Cold Shot Chillers
Process cooling equipment
- Thermal Care
Thermal-management components and systems
- Parker Hannifin Corporation
Thermal-management equipment
- ThermoTek Inc.
Industrial Water Cooling System Market Report Scope
Table 8: Report Scope for Industrial Water Cooling System Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Industrial cooling arrangements covered by product type and process application. |
| Units | USD billion; percentage |
| Market reference | USD 1.9 billion in 2025 |
| Forecast period | 2026 to 2036 |
| Charted shares | Dry cooling product type and petrochemicals application, 2026. |
| Country profiles | UK; India; Japan; China; USA. |
| Representative companies | IWC (Pty) Ltd.; Cold Shot Chillers; Thermal Care; Parker Hannifin Corporation; ThermoTek Inc. |
Industrial Water Cooling System Market Research Methodology
Table 9: Research Methodology for Industrial Water Cooling System Market, 2026 edition
| Method | Approach |
|---|---|
| Forecast basis | Published FMI headline values for 2025, 2026 and 2036 and 4.7% CAGR. |
| Product scope | Dry, wet and hybrid cooling and other equipment categories retain the source taxonomy. |
| Share comparisons | Product type and application remain separate 2026 breakdowns. |
| Country periods | Five published country rates retain 2026 to 2036. |
| Public evidence | A project determination, operating guidance, industrial reuse resources and a council register provide distinct demand and operating context. |
| Company comparison | Assessment covers the process duty, equipment boundary, site interfaces and continuing support. |
Industrial Water Cooling System Market by Segments
Industrial Water Cooling System Market segmented by Product Type:
- Dry Cooling
- Natural Draft Cooling Towers
- Mechanical Draft Cooling Towers
- Wet Cooling
- Condensers
- Hybrid Cooling
- Water Chillers
- Heat Exchangers
Industrial Water Cooling System Market segmented by Application:
- Petrochemicals
- Pharmaceuticals
- Power Generation Plants
- Metal Working
- Food and Beverage
Industrial Water Cooling System Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Western Europe
- Germany
- Italy
- France
- United Kingdom
- Spain
- BENELUX
- Nordic countries
- Eastern Europe
- Poland
- Hungary
- Romania
- Czech Republic
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia
- New Zealand
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkiye
- Israel
Research Sources and Bibliography
- [1] US Department of Energy. 5 February 2025. CX-033208: Modify Blowdown for A-Area Cooling Water System at 785-A
- [2] US Centers for Disease Control and Prevention. 3 January 2025. Controlling Legionella in Cooling Towers
- [3] US Environmental Protection Agency. Updated 1 October 2026; includes December 2025 webinar resources. Water Reuse for Industrial Applications Resources
- [4] Slough Borough Council. Register as of 19 May 2025. Cooling tower registration — Cooling tower register
This Report Answers
- How big is the industrial water cooling system market in 2026?
- What is the forecast for 2036?
- Which product is the published leading benchmark?
- Which application is the leading benchmark?
- Which profiled country has the highest growth rate?
- Does every retrofit replace the whole cooling system?
Frequently Asked Questions
What is the estimated market size in 2026?
FMI estimates USD 2.0 billion in 2026, compared with USD 1.9 billion in 2025.
What is the forecast for 2036?
The market is projected to reach USD 3.2 billion by 2036, with 4.7% CAGR from 2026 to 2036.
Which product is the published leading benchmark?
Dry cooling represents an estimated 16.0% of product-type demand in 2026.
Which application is the leading benchmark?
Petrochemicals represents an estimated 17.1% of application demand in 2026.
Which profiled country has the highest growth rate?
The UK has the highest profiled rate, at 5.2% for 2026 to 2036.
Does every retrofit replace the whole cooling system?
A retrofit can address a specific piping, control or water-management constraint within an existing system.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Dry Cooling
- Natural Draft Cooling Towers
- Mechanical Draft Cooling Towers
- Wet Cooling
- Condensers
- Hybrid Cooling
- Water Chillers
- Heat Exchangers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Petrochemicals
- Pharmaceuticals
- Power Generation Plants
- Metal Working
- Food and Beverage
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Italy
- France
- United Kingdom
- Spain
- BENELUX
- Nordic countries
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Hungary
- Romania
- Czech Republic
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia
- New Zealand
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia
- United Arab Emirates
- Turkiye
- Israel
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- IWC (Pty) Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cold Shot Chillers
- Thermal Care
- Parker Hannifin Corporation
- ThermoTek Inc.
- IWC (Pty) Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


