
- Market Size (2026)
- USD 5.0 Bn
- Forecast (2036)
- USD 11.4 Bn
- CAGR (2026 to 2036)
- 8.6%
How big is Europe Natural Cosmetics Market in 2026?
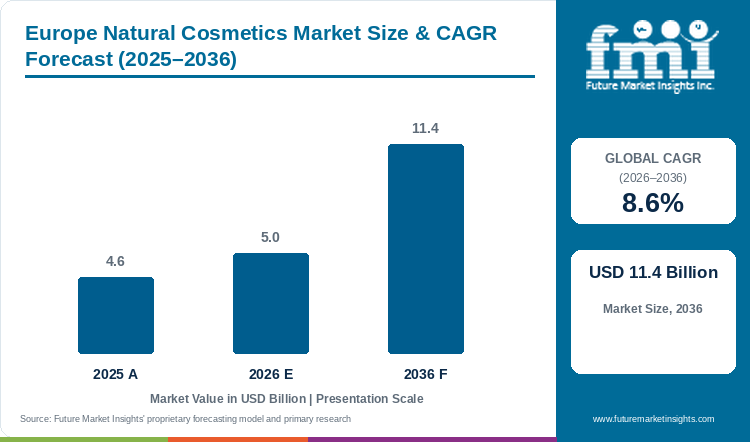
The Europe natural cosmetics market demonstrated steady progress from USD 4.6 billion in 2025 to USD 5.0 billion in 2026, building toward a targeted valuation of USD 11.4 billion by 2036 at a CAGR of 8.6%.
The Europe natural cosmetics market was valued at USD 4.6 billion in 2025 and is estimated to reach USD 5.0 billion in 2026. Overall industry valuation is projected to reach USD 11.4 billion by 2036, expanding at a compound annual growth rate (CAGR) of 8.6% between 2026 and 2036. Facial skincare covering organic cleansers and creams holds an estimated 48.0% share of 2026 category demand, given that European shoppers replace synthetic leave-on emulsions with certified botanical barrier formulas first. European pharmacies, bio-shops, and drugstores are delisting unverified clean-beauty labels and expanding shelf space for third-party audited natural cosmetics ahead of European Union green-claims enforcement. Financial disclosures from Weleda AG in April 2026 confirm this commercial shift, as the company achieved record 2025 revenue of EUR 484.6 million with cosmetics revenue climbing 10.2% on a currency-adjusted basis to EUR 401.9 million. That regulatory-verified substitution pushes European demand ahead of the 5.7% CAGR recorded across global natural cosmetics, since European Union bans on unverified environmental claims and cyclic silicones convert optional natural reformulation into a mandatory retail listing requirement. Multinational beauty groups and heritage DACH laboratories are investing heavily in biotech plant extraction, upcycled Mediterranean polyphenols, and refillable glass packaging to capture those retail upgrades. FMI finds that beauty brands retain long-term European pharmacy and bio-shop shelf space through 2036 when independent COSMOS or NATRUE certification backs every botanical efficacy claim.
Key Market Trends & Insights
- By product category: Natural and Organic Facial Skincare (Cleansers, Serums, and Creams) holds an estimated 48.0% share in 2026 since leave-on facial serums command premium retail pricing and daily replenishment.
- By certification standard: COSMOS Organic and Natural Certified represents an anticipated 56.0% in 2026 owing to unified auditing across Ecocert, BDIH, and Soil Association bodies.
- By distribution channel: Specialty Organic Health and Wellness Retailers (Bio-Shops) account for a projected 46.0% in 2026 supported by trained in-store naturopathic advisors across Germany, France, and Switzerland.
- By formulation active source: Botanical Cold-Pressed Oils, Hydrosols, and Plant Extracts secure an estimated 52.0% in 2026 driven by traceable calendula and sea buckthorn with sweet almond cultivation.
- By packaging format: Recycled Glass Jars, Dropper Bottles, and Airless Pumps command a projected 49.0% in 2026 as preservative-light organic emulsions require oxygen-barrier dispensing.
Regional Highlights
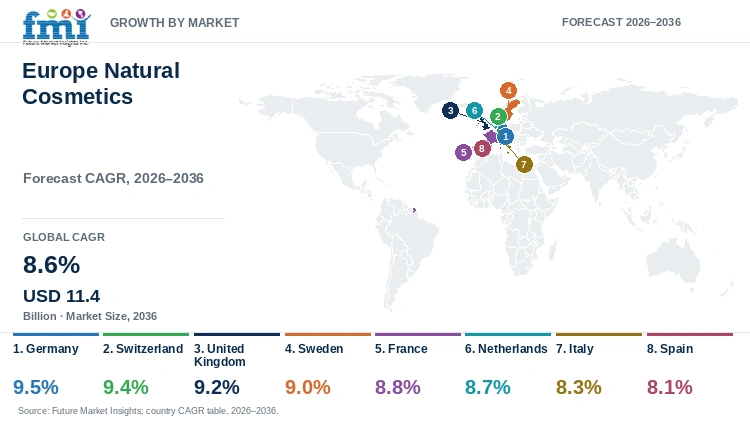
- Top national expansion: Germany leads national growth projections at a 9.5% CAGR through 2036 followed closely by Switzerland at a 9.4% CAGR under entrenched bio-shop, drugstore, and anthroposophic pharmacy demand.
- Broader country progression: The United Kingdom tracks at a 9.2% CAGR ahead of Sweden at 9.0% and France at 8.8%. The Netherlands advances at 8.7% ahead of Italy at 8.3% and Spain at 8.1%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Europe Natural Cosmetics Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.6 billion |
| Estimated Market Size in 2026 | USD 5.0 billion |
| Projected Market Size by 2036 | USD 11.4 billion |
| CAGR, 2026 to 2036 | 8.6% |
| Added Revenue, 2026 to 2036 | USD 6.4 billion |
European personal care buyers connect daily skincare and body-care routines with long-term dermatological health and environmental stewardship rather than superficial cosmetic coverage. Data from the Cosmetics Europe Socio-Economic and European Consumer Perception Study released in October 2026 shows that total European cosmetics retail sales reached EUR 110 billion in 2025 with France and Spain generating over EUR 14.7 billion of Europe's EUR 29.8 billion in cosmetic exports. Within that massive regional baseline, certified natural and certified organic cosmetics capture accelerating share as consumers trade up to audited botanical formulas.
Certified Product Base & Green-Claims Compliance Sizing
Table 2: Certified Natural Cosmetics Penetration and Retail Valuation Indicators in Europe, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Europe natural cosmetics market size (USD billion) | 4.6 | 5.0 | 11.4 |
| Natural & organic share of total European cosmetics (%) | 4.0% to 4.3% | 4.3% to 4.6% | 7.8% to 8.5% |
| COSMOS & NATRUE certified share of natural segment (%) | 78.0% | 81.5% | 92.0% |
| Facial skincare category share of natural revenue (%) | 47.5% | 48.0% | 50.5% |
Operational note: Certified natural share and audit indicators trace to Cosmetics Europe annual sector baselines, COSMOS-standard AISBL and NATRUE certification registries, and Weleda AG 2025 sustainability disclosures.
As documented by COSMOS-standard AISBL in June 2026, the European Union Empowering Consumers for the Green Transition Directive (EU) 2024/825 applies across all member states from September 27, 2026 and bans generic self-declared environmental claims unless verified by independent third-party certification. Retailers across Europe consequently require beauty and personal care products marketed as natural or organic to carry recognized COSMOS or NATRUE seals.
Organic Certification & Botanical Raw Material Sizing
Table 3: European Certified Beauty Growth & Sustainable Packaging Indicators, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Bio-shops & pharmacy combined channel share (%) | 68.5% | 69.5% | 72.0% |
| Recycled glass & refillable packaging penetration (%) | 64.0% | 67.5% | 84.0% |
| Botanical & upcycled bioactive formulation share (%) | 74.0% | 76.0% | 85.5% |
| Annual certified organic beauty sales growth UK/EU (%) | 8.0% | 8.6% | 8.8% |
Table 4: Institutional Regulatory & Corporate Reference Indicators for the Europe Natural Cosmetics Market, 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Estimated Europe natural cosmetics size, 2026 | USD 5.0 billion | FMI 2026 European certified & natural retail baseline |
| Total European cosmetics retail sales (2025) | EUR 110.0 billion | Cosmetics Europe Socio-Economic Report 2026 |
| Weleda AG global cosmetics revenue (2025) | EUR 401.9 million | Weleda Annual & Sustainability Report 2025 (+10.2% adj.) |
| Consumer importance rating for COSMOS certification | 84.0% | Soil Association Certification / YouGov Beauty Study 2025 |
Updated certification standards published by Soil Association Certification in September 2025 under COSMOS Version 4.2 confirm that certified organic leave-on cosmetics must contain at least 95% organic physically processed agro-ingredients and 20% total organic content. Brand formulators pair organic botanical certification with cruelty-free vegan cosmetics verification to satisfy ethical screening across European drugstores.
Analyst Perspective
"September 2026 marks a permanent commercial dividing line for natural beauty in Europe as EU Directive 2024/825 outlaws unsubstantiated green claims on retail shelves. Heritage certified houses such as Weleda, Dr Hauschka, and Lavera plus biotech-enabled dermocosmetic brands that pair COSMOS or NATRUE certification with clinical skin-barrier efficacy will capture the shelf space vacated by pseudo-natural brands through 2036."
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Europe natural cosmetics market segmented?
The Europe natural cosmetics market is segmented by product category, certification standard, distribution channel, formulation active source, and packaging format. In 2026, Natural and Organic Facial Skincare is projected at 48.0%, COSMOS Organic and Natural Certified at 56.0%, Specialty Organic Health and Wellness Retailers (Bio-Shops) at 46.0%, Botanical Cold-Pressed Oils and Plant Extracts at 52.0%, and Recycled Glass Jars and Airless Pumps at 49.0%.
By product category: Natural and Organic Facial Skincare, Natural Haircare, Natural Body Care, Natural Color Cosmetics, and Natural Fragrances.
By certification standard: COSMOS Organic and Natural Certified, NATRUE Certified True Natural, BDIH Standard Certified, Ecocert Greenlife Certified, and The Vegan Society Trademarked.
By distribution channel: Specialty Organic Health and Wellness Retailers, Pharmacies and European Apothekens, Conventional Supermarket Natural Aisles, Dedicated Brand Online D2C Boutiques, and Prestige Department Stores.
By formulation active source: Botanical Cold-Pressed Oils and Plant Extracts, Biotech-Fermented Peptides and Microalgae Bioactives, Upcycled Agro-Food Seed Actives, and Mineral Pigments and Marine Algae.
By packaging format: Recycled Glass Jars and Airless Pumps, Refillable Pods and In-Store Refill Cartridges, Post-Consumer Recycled Aluminum Tubes, and Waterless Solid Bars.
Why does Natural and Organic Facial Skincare lead the product category?
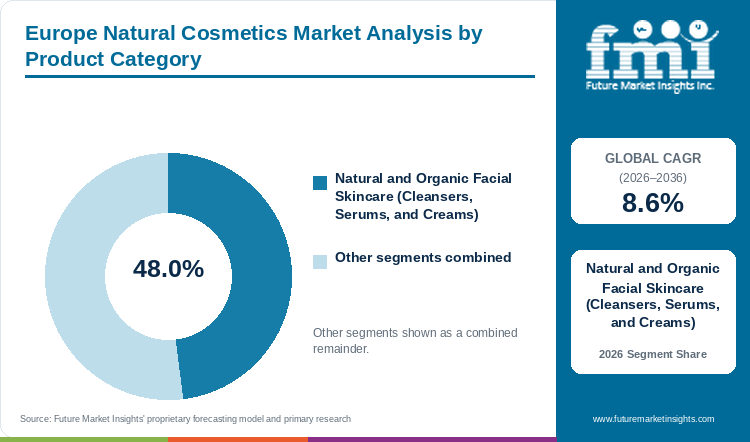
Natural and Organic Facial Skincare (Cleansers, Serums, and Creams) holds an estimated 48.0% of product category demand in 2026, anchored by daily barrier-repair and anti-aging serum replenishment.
Table 5: Product Category Share for the Europe Natural Cosmetics Market (percentage share), 2026
| Product Category | Share (2026) |
|---|---|
| Natural and Organic Facial Skincare (Cleansers, Serums, and Creams) | 48.0% |
| Other Segments Combined | 52.0%* |
| Total | 100.0% |
*Note: Remaining product categories (Natural Haircare, Natural Body Care, and Natural Color Cosmetics with Fragrances) account for the balance of 2026 European natural cosmetics demand.
Table 6: Product Category Leadership and Market Growth for the Europe Natural Cosmetics Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Europe CAGR (2026 to 2036) | 8.6% |
| Leading Segment | Natural and Organic Facial Skincare (Cleansers, Serums, and Creams) |
Natural and organic facial skincare leads European revenue, owing to consumers apply facial serums, eye creams, and barrier moisturizers twice daily to sensitive skin zones and willingly pay premium prices for clinically proven botanical actives. Formulators enrich organic facial emulsions with upcycled cosmetic actives extracted from Mediterranean olive, grape, and citrus pressing residues to boost antioxidant potency. Peer-reviewed research published in Pharmaceutics in March 2026 substantiates this formulation approach, showing how botanical and upcycled bioactives improve cutaneous delivery and skin barrier repair through sustainability-by-design pathways. Long ambient shelf stability without synthetic parabens or phenoxyethanol remains the primary technical hurdle requiring airless pump packaging.
- Within the product category segment, Natural and Organic Facial Skincare is projected to account for a leading 48.0% share in 2026, driven by high repeat purchase frequency of anti-aging and barrier-repair serums.
- Silicone-free natural haircare and mineral sun-care emulsions are forecast to record strong secondary expansion through 2036 as green-chemistry surfactants improve foam and sensory slip.
What sustains COSMOS Organic and Natural Certified leadership in the certification standard segment?
COSMOS Organic and Natural Certified represents an anticipated 56.0% of the certification standard category in 2026, supported by unified auditing across Ecocert, BDIH, Soil Association, and Cosmebio.
The harmonized COSMOS-standard dominates European certification demand since it unites five founding European inspection bodies (BDIH in Germany and Ecocert in France plus ICEA in Italy and the Soil Association in the UK) under a single internationally recognized seal. Brands sourcing supercritical botanical CO2 extracts and organic plant oils can use one COSMOS audit dossier to qualify products simultaneously across German drugstores, French pharmacies, and British organic retailers. Annual ingredient-origin auditing fees and strict petrochemical moiety limits nonetheless pose compliance hurdles for smaller indie beauty startups.
- In 2026, COSMOS Organic and Natural Certified products are anticipated to capture 56.0% of certification standard demand across Europe, supported by cross-border retail recognition.
- Official compliance guidance issued by COSMOS-standard AISBL in June 2026 confirms that COSMOS signatures satisfy the independent third-party verification rules mandated under EU Directive 2024/825 from September 2026.
How do Specialty Organic Health and Wellness Retailers (Bio-Shops) lead the distribution channel category?
Specialty Organic Health and Wellness Retailers (Bio-Shops) account for a projected 46.0% of distribution channel demand in 2026, driven by strict ingredient curation and trained in-store advisors.
Dedicated organic supermarkets and health-food bio-shops such as Alnatura, Dennree, and Biocoop anchor European distribution by curating 100% certified natural beauty aisles where shoppers trust that synthetic silicones and mineral oils are excluded. Store staff in European bio-shops and reformhäuser provide personalized skin-type consultations for herbal beauty formulations that mass-market supermarket shelves cannot match. Regulatory analysis published by NATRUE in February 2025 confirms that EU anti-greenwashing rules under Directive (EU) 2024/825 blacklist unverified organic claims and reinforce consumer reliance on specialist certified retail assortments. High bio-shop real estate rents in metropolitan centers still limit store count expansion in smaller towns.
- By distribution channel, Specialty Organic Health and Wellness Retailers (Bio-Shops) are estimated to reach 46.0% of category share in 2026 as core organic shoppers consolidate grocery and personal care baskets.
- European pharmacies (Apotheken and parapharmacies) and direct-to-consumer digital skin-diagnostic boutiques are projected to capture rising channel share through 2036.
Why do Botanical Cold-Pressed Oils, Hydrosols, and Plant Extracts lead the formulation active source category?
Botanical Cold-Pressed Oils, Hydrosols, and Plant Extracts secure an estimated 52.0% of formulation active source value in 2026, supported by traceable European medicinal plant cultivation.
Cold-pressed botanical seed oils, steam-distilled floral hydrosols, and standardized medicinal plant extracts form the lipid and active backbone of European natural cosmetics as they replace petroleum-derived mineral oils and synthetic emollients directly. Heritage European formulators grow biodynamic calendula, chamomile, and sweet almond in European agroecological gardens to guarantee batch traceability and zero pesticide residue. Seasonal harvest weather variability and high solvent-free extraction costs represent ongoing supply-chain challenges that require multi-origin farming contracts.
- Consumer preference for recognizable whole-plant ingredients places Botanical Cold-Pressed Oils, Hydrosols, and Plant Extracts on course to hold an estimated 52.0% share of the formulation active source category in 2026.
- Formulation research published in Cosmetics in November 2025 demonstrated that loan-extraction technology using natural cosmetic base components isolates up to 50% bioactive Calendula officinalis petal extracts while lowering manufacturing cost.
What gives Recycled Glass Jars, Dropper Bottles, and Airless Pumps the leading position in packaging format?
Recycled Glass Jars, Dropper Bottles, and Airless Pumps command a projected 49.0% of packaging format share in 2026, anchored by oxygen-barrier preservation and EU circularity rules.
Recycled amber and flint glass dropper bottles, apothecary jars, and airless dispenser pumps lead packaging format selection since natural cosmetics formulated without synthetic preservatives require inert oxygen-tight containers that prevent lipid oxidation. Glass packaging also aligns with strict European Union Packaging and Packaging Waste Regulation recyclability targets and signals premium apothecary quality on pharmacy shelves. Corporate disclosures in the LVMH 2025 Social and Environmental Responsibility Report published in May 2026 confirm that its Perfumes and Cosmetics maisons expanded recycled glass and eco-designed refillable packaging across European boutiques. Heavier transport weight of glass jars compared with mono-material tubes remains a freight emissions tradeoff.
- Recycled Glass Jars and Airless Pumps are predicted to command 49.0% of packaging format demand in 2026, anchored by formula preservation and European circular-packaging mandates.
- In-store refill fountains and snap-in refillable cream pods are forecast to expand rapidly across French and German perfumeries through 2036.
What are the drivers, restraints, and opportunities in the Europe natural cosmetics market?
In the Europe natural cosmetics market, EU Directive 2024/825 anti-greenwashing rules and REACH restrictions on leave-on cyclic silicones and microplastics are projected to drive adoption, while essential-oil allergen limits and organic raw-material volatility restrain low-cost formulas and upcycled agro-food bioactives open high-margin pharmacy growth.
- Driver: Enforcement of EU Directive 2024/825 against greenwashing and REACH restrictions on leave-on cyclic silicones and microplastics compel brands and retailers to adopt certified natural formulations.
- Restraint: Strict allergen labeling thresholds and guidance concentration limits on natural essential oils and volatile organic botanical harvest prices restrain low-cost mass formulation.
- Opportunity: Upcycling European wine, olive, and fruit agro-industrial byproducts into clinically validated biotech dermocosmetic serums and refillable packaging opens high-margin pharmacy growth.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Mandatory European Union chemical restrictions on synthetic silicones and microplastics are accelerating the structural migration of European consumers and formulators toward certified plant-based and mineral cosmetics. When synthetic emollients and plastic glitter or exfoliating beads are legally phased out, beauty brands must reformulate around biodegradable botanical esters and plant-derived cosmetic pigments. Official European Union legal provisions under Commission Regulation (EU) 2024/1328 confirm that the REACH restriction on cyclosiloxanes D4, D5, and D6 in leave-on cosmetic products applies from June 2026. This regulatory deadline directly boosts demand for natural plant-oil alkanes and certified organic emulsions across Europe.
Risk Assessment of the Europe Natural Cosmetics Market: Operational and Formulation Friction
Expanded European fragrance allergen labeling rules and dermatological concentration caps on volatile essential oils represent the primary technical restraints challenging natural cosmetic formulators. Many consumers assume that plant essential oils are completely risk-free, yet undiluted terpenes can trigger contact sensitization on reactive or atopic facial skin. The German Federal Institute for Risk Assessment (BfR) Commission for Cosmetics published updated guidance in September 2026 recommending that leave-on cosmetic products contain no more than 1% eucalyptus oil, camphor, or menthol. Brands developing concentrated facial serum drops must therefore invest in allergen-fractionated botanical extracts or fragrance-free soothing actives to pass European safety assessments.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Cosmetic ingredient houses and European natural beauty brands capture superior gross margins by converting Mediterranean agricultural side-streams such as grape pomace, olive leaves, and pomegranate peels into high-potency dermocosmetic actives. Circular extraction of food-chain byproducts lowers raw-material land footprint while delivering concentrated polyphenols and resveratrol for nourishing botanical hair and skin care lines. A comprehensive review published in Applied Sciences in May 2026 documented how agro-industrial residues provide high-value antioxidant, anti-inflammatory, and photoprotective bioactives for circular skincare innovation. Use of upcycled bioactives in refillable glass packaging enables European brands to satisfy both efficacy-driven pharmacy shoppers and zero-waste regulations.
Europe Natural Cosmetics Market by Country (2026 to 2036)
FMI country modeling indicates that Germany leads Europe natural cosmetics expansion at a 9.5% CAGR through 2036 ahead of Switzerland at 9.4% and the United Kingdom at 9.2%.
Table 7: Country CAGR and Primary Growth Levers for the Europe Natural Cosmetics Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 9.5% | Nationwide drugstore (dm, Rossmann) and bio-shop Naturkosmetik penetration |
| Switzerland | 9.4% | Europe's highest per-capita organic spend and Arlesheim/alpine phytochemistry R&D |
| United Kingdom | 9.2% | Soil Association COSMOS and Vegan Society growth with D2C clean beauty |
| Sweden | 9.0% | Nordic cold-climate barrier balms and strict apotek chemical-exclusion lists |
| France | 8.8% | Parapharmacy dermo-botanical skincare, Ecocert/COSMOS audits, and AGEC refills |
| Netherlands | 8.7% | Zero-waste solid bars, Ekoplaza bio-retail, and strict green-claims screening |
| Italy | 8.3% | Traditional erboristerie network and Mediterranean olive/grape bioactive extraction |
| Spain | 8.1% | Organic mineral sun care, aloe/olive body care, and Barcelona cosmetic clusters |
Source: Future Market Insights analysis
Germany Europe Natural Cosmetics Market Outlook (2026 to 2036)
Demand for natural cosmetics in Germany is projected to expand at a leading 9.5% CAGR between 2026 and 2036 across organic bio-shops and nationwide drugstore chains dm, Rossmann, and Müller. What sets Germany apart as Europe's largest natural beauty market is the combination of heritage BDIH and NATRUE pioneer brands (Dr Hauschka, Lavera, and ANNEMARIE BÖRLIND) with deeply entrenched household trust in certified Naturkosmetik seals. In May 2026, NATRUE hosted its inaugural Natural Cosmetics Industry Forum in Berlin featuring WALA CEO Prof. Dr. Florian Stintzing on natural complex substances and science-driven formulation. German drugstores also stock certified private-label lines such as Alverde and Alterra beside clinical botanical serums, sustaining broad demographic adoption.
Key takeaway: In Germany, nationwide drugstore and bio-shop distribution with Berlin regulatory and formulation leadership are projected to drive a leading 9.5% CAGR.
France Europe Natural Cosmetics Market Outlook (2026 to 2036)
Sales of natural cosmetics in France are estimated to grow at an 8.8% CAGR from 2026 to 2036, anchored by dermo-botanical pharmacy brands and prestige eco-designed skincare. Compared with German shoppers who buy primarily in drugstores and bio-shops, French consumers purchase natural skincare heavily through parapharmacies and organic chains such as Biocoop. French dermo-cosmetics leader Laboratoires Pierre Fabre reported in March 2026 that its Dermo-Cosmetics and Personal Care division grew 3.9% in 2025 to EUR 1.7 billion while filing 35 INPI patents and earning AFNOR Exemplary RSE certification. Strict French AGEC circular-packaging rules and Ecocert/COSMOS verification further push French laboratories to pioneer refillable glass bottles and waterless botanical cleansers.
Key takeaway: In France, parapharmacy dermo-botanical demand and AGEC refillable packaging standards are estimated to sustain an 8.8% CAGR.
United Kingdom Europe Natural Cosmetics Market Outlook (2026 to 2036)
Market revenue in the United Kingdom is forecast to progress at a 9.2% CAGR between 2026 and 2036, reflecting high digital D2C beauty adoption and Soil Association COSMOS and Vegan Society certification growth. British shoppers show strong willingness to trial botanical facial oils, aromatherapy balms, and vegan mineral makeup through online subscription platforms and pharmacy chains such as Boots and Holland & Barrett. Industry disclosures from the Soil Association UK at its July 2025 BOOM Awards and Organic Market Report confirm that certified organic beauty sales grew 8% while 84% of surveyed British consumers prioritize COSMOS standards. Domestic brands mitigate essential-oil import volatility by blending upcycled British berry seed oils with biotech hyaluronic acid.
Key takeaway: In the United Kingdom, Soil Association COSMOS and Vegan Society certification with digital D2C skincare adoption are forecast to propel a 9.2% CAGR.
Italy Europe Natural Cosmetics Market Outlook (2026 to 2036)
In Italy, natural cosmetics demand is anticipated to advance at an 8.3% CAGR over the 2026 to 2036 forecast period, supported by the country's dense network of traditional herbalist shops (erboristerie) and contract cosmetic manufacturers in Lombardy. Italian formulators excel at extracting Mediterranean olive squalane, red grape polyphenols, and Sicilian blood-orange bioactives for anti-aging facial creams and phyto-haircare. Peer-reviewed cosmetic research published in Cosmetics in June 2025 demonstrated how digital skin diagnostics and targeted bioactive delivery systems are reshaping personalized facial skincare formulations across European laboratories. High fragmentation among family-owned Italian erboristerie requires brands to invest in unified ICEA/COSMOS certification and pharmacist detailing.
Key takeaway: In Italy, erboristerie and pharmacy channel strength paired with Mediterranean olive and grape bioactive extraction are anticipated to support an 8.3% CAGR.
Spain Europe Natural Cosmetics Market Outlook (2026 to 2036)
Natural cosmetics adoption in Spain is forecast to climb at an 8.1% CAGR from 2026 to 2036 as sun-care, after-sun aloe and olive body care, and pharmacy dermocosmetics transition toward biodegradable organic formulas. High year-round solar UV exposure and coastal tourism in Spain create strong domestic and export demand for mineral reef-safe sunscreens and antioxidant botanical serums produced in Barcelona and Valencia cosmetic clusters. Official industry statistics published by Spain National Perfumery and Cosmetics Association (STANPA) in April 2026 confirm that Spanish cosmetics consumption surpassed EUR 11.8 billion in 2025 and achieved record international exports. Spanish natural brands and Basque Coast laboratories capitalize on this microplastic ban with certified organic mineral sun care.
Key takeaway: In Spain, mineral sun-care demand and Mediterranean botanical manufacturing under EU microplastic restrictions are forecast to drive an 8.1% CAGR.
Switzerland Europe Natural Cosmetics Market Outlook (2026 to 2036)
Commercial revenue in the Switzerland natural cosmetics market is anticipated to progress at a 9.4% CAGR through 2036, supported by Europe's highest per-capita spending on certified organic products and world-renowned alpine phytochemistry R&D. Swiss consumers in Zurich, Geneva, and Basel prioritize anthroposophic pharmacy skincare and biodynamic alpine edelweiss and gentian extracts. Regulatory guidance updated by Swissmedic and the Federal Food Safety and Veterinary Office in December 2025 under Swiss Ordinance SR 817.02 enforces strict delimitation and purity criteria for essential oils in Swiss cosmetics. High Swiss retail pharmacy margins allow brands to commercialize clinically tested alpine stem-cell and biotech-botanical serums.
Key takeaway: In Switzerland, high per-capita organic expenditure and Arlesheim and alpine phytochemistry innovation are projected to sustain a 9.4% CAGR.
Netherlands Europe Natural Cosmetics Market Outlook (2026 to 2036)
Dutch natural cosmetics sales are slated to grow at an 8.7% CAGR across the 2026 to 2036 horizon as urban consumers in Amsterdam and Rotterdam adopt zero-waste solid shampoo bars, refillable deodorants, and vegan facial serums. What distinguishes the Netherlands in Benelux is the rapid convergence of e-commerce clean-beauty platforms, specialty organic chains such as Ekoplaza and Holland & Barrett, and strict national consumer-protection enforcement against greenwashing. In September 2025, the Netherlands Authority for Consumers and Markets (ACM) enforced the removal of unverified sustainability labels on cosmetics and clothing at Dutch retailer De Bijenkorf in favor of clear third-party certification. Dutch retailers consequently prioritize compact waterless and COSMOS-certified SKUs that lower packaging waste.
Key takeaway: In the Netherlands, zero-waste solid and refillable formats with strict green-claims retail screening are slated to support an 8.7% CAGR.
Sweden Europe Natural Cosmetics Market Outlook (2026 to 2036)
Sweden natural cosmetics demand is predicted to advance at a 9.0% CAGR from 2026 to 2036, driven by Nordic cold-climate skin barrier protection needs and water-conscious biodegradable formulation standards. Sub-zero winter temperatures and dry indoor heating across Stockholm and Gothenburg compel Swedish consumers to purchase lipid-rich cloudberry, oat-ceramide, and sea-buckthorn facial balms and body oils. Clinical dermatology research published in Frontiers in Medicine in July 2025 confirmed that cold-pressed plant oils and essential oils from lavender, rosemary, and chamomile improve skin hydration and barrier recovery in topical creams and serums. Swedish state-backed and private apotek chains enforce rigorous chemical-exclusion lists that accelerate consumer switching to COSMOS and Swan-ecolabeled skincare.
Key takeaway: In Sweden, Nordic cold-climate barrier skincare demand and strict pharmacy chemical-exclusion screening are predicted to drive a 9.0% CAGR.
Full report country CAGRs cover: Germany; France; United Kingdom; Italy; Spain; Switzerland; Netherlands; Sweden; Benelux; Nordics; Austria; Poland; and Rest of Europe.
Who are the notable companies in the Europe natural cosmetics market?
Weleda AG, Dr. Hauschka (WALA Heilmittel GmbH), L'Oréal S.A. (Sanoflore), Yves Rocher (Groupe Rocher), LVMH Moët Hennessy Louis Vuitton SE, Lavera Naturkosmetik (Laverana GmbH), Laboratoires de Biarritz, LOGOCOS Naturkosmetik GmbH & Co. KG, Laboratoire NUXE, and ANNEMARIE BÖRLIND are the notable companies in the Europe natural cosmetics market.
Competitive positioning in the European natural cosmetics industry separates heritage certified anthroposophic pioneers, multinational beauty groups, and specialized French pharmacy laboratories. Weleda, Dr Hauschka, and Lavera compete with L'Oréal and Yves Rocher.
- Heritage Pioneer Certified Natural Houses: Weleda AG, Dr. Hauschka, Lavera Naturkosmetik, and ANNEMARIE BÖRLIND formulate 100% NATRUE, COSMOS, and BDIH certified skincare lines.
- Multinational Beauty Groups & Dermo-Botanical Leaders: L'Oréal S.A., Yves Rocher (Groupe Rocher), and LVMH combine global R&D with certified organic and eco-designed skincare.
- Specialized French Pharmacy & Marine Organic Laboratories: Laboratoires de Biarritz and Laboratoire NUXE engineer COSMOS-certified marine algae sunscreens, organic dry oils, and apothecary facial treatments.
Competitive Benchmarking: Europe Natural Cosmetics Market
Table 8: Competitive Benchmarking for the Europe Natural Cosmetics Market (qualitative capability ratings), 2026
| Company | Third-Party Certification Depth | Botanical & Biotech R&D | Pharmacy & Bio-Shop Reach | European Geographic Reach |
|---|---|---|---|---|
| Weleda AG | High | High | High | Pan-European leader (Switzerland, Germany, France, UK); 100% NATRUE certified cosmetics |
| Dr. Hauschka (WALA GmbH) | High | High | High | Germany, Switzerland, France, UK, and Nordics; NATRUE certified rhythmic medicinal skincare |
| L'Oréal S.A. (Sanoflore) | High | High | High | Pan-European pharmacy and mass retail; ECOCERT/COSMOS Sanoflore and La Provençale Bio |
| Yves Rocher (Groupe Rocher) | Medium | High | High | France, Spain, Italy, Germany, and Benelux; La Gacilly organic agroecology and boutiques |
| LVMH Moët Hennessy Louis Vuitton | Medium | High | High | Pan-European selective perfumeries; 69% eco-designed Perfumes & Cosmetics and refills |
| Lavera Naturkosmetik (Laverana) | High | High | High | Germany, Austria, Switzerland, and UK; NATRUE and GREEN BRAND certified drugstore/bio lines |
| Laboratoires de Biarritz | High | High | High | France, Spain, and Benelux parapharmacies; COSMOS Organic marine algae sun and skin care |
| LOGOCOS Naturkosmetik | High | Medium | High | DACH and Western Europe bio-shops; Logona, Sante, and Heliotrop NATRUE/COSMOS brands |
| Laboratoire NUXE | Medium | High | High | France, Italy, Spain, and UK pharmacies; Huile Prodigieuse Neroli and Bio organic lines |
| ANNEMARIE BÖRLIND | High | High | High | Germany, Switzerland, and Western Europe Reformhäuser and perfumeries; CSE/COSMOS skincare |
Evaluation basis: Third-Party Certification Depth evaluates portfolio coverage under COSMOS and NATRUE audits. Botanical & Biotech R&D rates medicinal plant extraction, while Pharmacy & Bio-Shop Reach measures European shelf presence.
Key Developments in the Europe Natural Cosmetics Market
- Laverana GmbH (lavera Naturkosmetik) was awarded the GREEN BRAND Germany certification and won the Sustainable Beauty Award Europe in November 2025 for its certified natural skincare and climate-conscious production.
- Symrise AG documented in its November 2025 Corporate Report the expansion of its traceable botanical cosmetic active ingredients and natural preservation boosters for European personal care formulators.
- L'Oréal Groupe launched its multi-division Join the Refill Movement campaign in June 2025 across European perfumeries and pharmacies to accelerate consumer adoption of refillable skincare jars and fragrance bottles.
Key Players in the Europe Natural Cosmetics Market
Heritage Pioneer Certified Natural & Anthroposophic Houses
- Weleda AG
- Dr. Hauschka (WALA Heilmittel GmbH)
- Lavera Naturkosmetik (Laverana GmbH)
- LOGOCOS Naturkosmetik GmbH & Co. KG
Multinational Beauty Groups & Dermo-Botanical Leaders
- L'Oréal S.A. (Sanoflore & La Provençale Bio)
- Yves Rocher (Groupe Rocher)
- LVMH Moët Hennessy Louis Vuitton SE
- ANNEMARIE BÖRLIND (Börlind GmbH)
Specialized French Pharmacy & Marine Organic Laboratories
- Laboratoires de Biarritz
- Laboratoire NUXE
Europe Natural Cosmetics Market - Report Scope
Table 9: Report Scope for the Europe Natural Cosmetics Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Category; Certification Standard; Distribution Channel; Formulation Active Source; Packaging Format |
| Quantitative Units | USD Billion |
| Market Definition | Includes European retail and D2C manufacturer revenue from certified and authentic natural and organic facial skincare, haircare, body care, color cosmetics, and essential-oil fragrances meeting COSMOS, NATRUE, BDIH, Ecocert, Vegan Society, or ISO 16128 high-naturality criteria. Category Scope Note: Excludes conventional petrochemical personal care, prescription dermatological drugs, and raw unformulated bulk agricultural commodities. |
| Regions & Countries Covered | Germany, France, United Kingdom, Italy, Spain, Switzerland, Netherlands, Sweden, and additional European countries in the full report |
| Regulatory Frameworks Covered | EU Regulation (EC) No 1223/2009, EU Empowering Consumers Directive (EU) 2024/825, ECHA REACH D4/D5/D6 and Microplastics Regulation (EU) 2023/2055 |
| Key Companies Covered | Weleda AG, Dr. Hauschka (WALA Heilmittel GmbH), L'Oréal S.A. (Sanoflore), Yves Rocher (Groupe Rocher), LVMH Moët Hennessy Louis Vuitton SE, Lavera Naturkosmetik (Laverana GmbH), Laboratoires de Biarritz, LOGOCOS Naturkosmetik, Laboratoire NUXE, ANNEMARIE BÖRLIND |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Europe Natural Cosmetics Market - Research Methodology
Table 10: Research Methodology for the Europe Natural Cosmetics Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with European natural cosmetic R&D directors, COSMOS and NATRUE certification auditors, German drugstore and bio-shop category managers, and French parapharmacy buyers. |
| Secondary Research | Analysis of Cosmetics Europe sector reports, ECHA REACH restriction dossiers, BfR essential-oil safety opinions, COSMOS-standard AISBL and NATRUE regulatory briefings, and corporate annual reports. |
| Market Sizing and Forecasting | Top-down Cosmetics Europe personal care baselines (EUR 110B in 2025) reconciled against bottom-up certified natural/organic category shares across DACH, France, UK, Southern Europe, and Nordics from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight bio-shop and drugstore store counts, per-capita organic expenditure, EU Directive 2024/825 enforcement readiness, and domestic botanical brand launches. |
| Operational Benchmark Traceability | Certification, revenue, and regulatory indicators in Tables 2, 3, and 4 trace directly to Weleda 2025 Annual Report, Cosmetics Europe 2026 study, Soil Association 2025 report, and COSMOS-standard AISBL guides. |
| Data Triangulation and Validation | Revenue estimates isolate finished natural and organic cosmetic products across European retail and D2C channels while excluding synthetic mass-market personal care and oral pharmaceuticals. |
Europe Natural Cosmetics Market by Segments
Europe Natural Cosmetics Market segmented by Product Category:
- Natural and Organic Facial Skincare (Cleansers, Serums, and Creams)
- Natural Haircare (Shampoos, Conditioners, and Hair Oils)
- Natural Body Care (Lotions, Balms, and Body Washes)
- Natural Color Cosmetics and Natural Fragrances
Europe Natural Cosmetics Market segmented by Certification Standard:
- COSMOS Organic and Natural Certified
- NATRUE Certified True Natural
- BDIH Standard Certified
- Ecocert Greenlife Certified and The Vegan Society Trademarked
Europe Natural Cosmetics Market segmented by Distribution Channel:
- Specialty Organic Health and Wellness Retailers (Bio-Shops)
- Pharmacies and European Apothekens
- Conventional Supermarket Natural Aisles
- Dedicated Brand Online D2C Boutiques
- Prestige Department Stores and Clean-Beauty Perfumeries
Europe Natural Cosmetics Market segmented by Formulation Active Source:
- Botanical Cold-Pressed Oils, Hydrosols, and Plant Extracts
- Biotech-Fermented Peptides and Microalgae Bioactives
- Upcycled Agro-Food Seed and Fruit Peel Actives
- Mineral Pigments and Marine Algae Complexes
Europe Natural Cosmetics Market segmented by Packaging Format:
- Recycled Glass Jars, Dropper Bottles, and Airless Pumps
- Refillable Pods and In-Store Refill Cartridges
- Post-Consumer Recycled (PCR) Aluminum and Mono-Material Tubes
- Waterless Solid Bars and Paperboard Compacts
Europe Natural Cosmetics Market by Region
- DACH Region
- Germany
- Switzerland and Austria
- Western Europe Core
- France
- Belgium
- Netherlands
- Luxembourg
- Northern Europe & United Kingdom
- United Kingdom
- Sweden
- Denmark
- Norway
- Finland
- Ireland
- Iceland
- Southern Europe
- Italy
- Spain
- Portugal
- Greece
- Central & Eastern Europe
- Poland
- Czech Republic
- Hungary
- Southeastern Europe & Baltics
- Romania
- Estonia, Latvia, and Lithuania
- Croatia and Slovenia
- Primary European Certification Jurisdictions
- EU-27 Single Market (Directive 2024/825 & Regulation 1223/2009)
- United Kingdom (UK Cosmetics Regulation & Soil Association)
- Switzerland (FSVO Cosmetics Ordinance)
- European Economic Area (Norway & Iceland)
Research Sources and Bibliography
- [1] Weleda AG. (2026, April 30). Weleda Annual and Sustainability Report 2025: Record EUR 484.6 Million Turnover and Certified Cosmetics Growth. Weleda AG Corporate Financial Publications.
- [2] L'Oréal Groupe. (2026, June 11). L'Oréal Unveils the Future of Beauty at VivaTech 2026: Microphyt Microalgae Biotech and Green Sciences. L'Oréal Groupe Research and Innovation Press Releases.
- [3] Cosmetics Europe. (2026, October 16). Beauty and Beyond: European Consumer Perception Study 2026 and EUR 110 Billion Sector Socio-Economic Report. Cosmetics Europe Personal Care Association.
- [4] COSMOS-standard AISBL. (2026, June 10). EU Directive 2024/825 Empowering Consumers for the Green Transition and COSMOS-Certified Products Guide for Retailers. COSMOS-standard AISBL Regulatory Guidance.
- [5] Soil Association Certification. (2025, September 1). COSMOS Version 4.2 Organic and Natural Health and Beauty Certification Standards Update. Soil Association Certification UK Official Standards.
- [6] Panza, S., et al. (2026, March 18). Botanical and Upcycled Bioactives for Advanced Topical Formulations: Mechanistic Pathways and Cutaneous Delivery. Pharmaceutics, 18(3), 375 (MDPI Open Access).
- [7] COSMOS-standard AISBL. (2026, June 10). EU Directive 2024/825 and Your COSMOS Certification: Compliance Requirements for Certified Brands. COSMOS-standard AISBL Technical Communications.
- [8] NATRUE. (2025, February 25). New EU Directives on Greenwashing: How Natural and Organic Cosmetics Must Adapt by September 2026. The International Natural and Organic Cosmetics Association.
- [9] Orzechowicz, W., et al. (2025, November 24). A New Cost-Effective Facial Skin Care Serum Rich in Bioactive Ingredients Isolated from Calendula officinalis Petals. Cosmetics, 13(2), 69 (MDPI Open Access).
- [10] LVMH Moët Hennessy Louis Vuitton SE. (2026, May 19). LVMH Publishes Its 2025 Social and Environmental Responsibility Report: Eco-Designed Perfumes and Cosmetics Packaging. LVMH Group Official Newsroom.
- [11] European Commission. (2025, May 16). Commission Regulation (EU) 2024/1328 Amending Annex XVII to REACH as Regards Cyclosiloxanes D4, D5, and D6 in Leave-On Cosmetics From June 2026. Official Journal of the European Union EUR-Lex.
- [12] German Federal Institute for Risk Assessment (BfR). (2026, September 2). Essential Oils in Cosmetic Products: Fragrant Benefits with Guidance Concentration Limitations. Bundesinstitut für Risikobewertung (BfR) Commission for Cosmetics.
- [13] Fernandez Martinez, S., et al. (2026, May 11). From Waste to Dermocosmetic Value: A Narrative Review of Agro-Industrial Residues in Skincare Innovation. Applied Sciences, 16(10), 4777 (MDPI Open Access).
- [14] NATRUE. (2026, May 20). Natural Cosmetics Industry Forum 2026 in Berlin: Natural Complex Substances and Science-Driven Innovation. The International Natural and Organic Cosmetics Association.
- [15] Laboratoires Pierre Fabre. (2026, March 19). Laboratoires Pierre Fabre Confirms 2025 Performance with EUR 1.7 Billion in Dermo-Cosmetics and AFNOR Exemplary RSE Certification. Laboratoires Pierre Fabre Castres Official Newsroom.
- [16] Soil Association Certification. (2025, July 11). 2025 BOOM Award Winners Announced Alongside 2025 UK Organic Beauty and Wellbeing Market Growth. Soil Association UK Official Newsroom.
- [17] Bom, S., et al. (2025, June 25). Emerging Trends in Facial Cosmetics: Innovation, Science, and Personalized Bioactive Delivery. Cosmetics, 13(2), 58 (MDPI Open Access).
- [18] Asociación Nacional de Perfumería y Cosmética (STANPA). (2026, April 23). La Industria Cosmética Supera los 11.800 Millones de Euros en Consumo y Consolida su Liderazgo Exportador en 2025. STANPA Official Press Releases.
- [19] Swissmedic, Federal Office of Public Health (FOPH), & Federal Food Safety and Veterinary Office (FSVO). (2025, December 15). Fact Sheet: Classification of Essential Oils and Natural Cosmetic Delimitation Criteria Under Swiss Ordinance SR 817.02. Swiss Agency for Therapeutic Products Official Regulatory Publications.
- [20] Netherlands Authority for Consumers and Markets (ACM). (2025, September 11). Dutch Department Store De Bijenkorf Removes Incorrect Sustainability Claims on Cosmetics and Clothing Following ACM Action. Authority for Consumers and Markets Official Publications.
- [21] Markiewicz, A., et al. (2025, July 15). Evaluating Efficacy, Safety, and Innovation in Skin Care Applications of Essential Oils and Plant Extracts. Frontiers in Medicine, 12, 1589691.
- [22] L'Oréal Groupe. (2025, June 13). L'Oréal Invites Consumers Around the World to Join the Refill Movement Across Multi-Division Brands. L'Oréal Groupe Sustainability Commitments.
- [23] Laverana GmbH & Co. KG. (2025, November 24). lavera Natural Beauty Recognized Again with GREEN BRAND Germany Certification and Sustainable Beauty Award Europe 2025. lavera Naturkosmetik Official Newsroom.
- [24] Symrise AG. (2025, November 7). Symrise Corporate Report 2025: Botanical Cosmetic Active Ingredients and Sustainable Raw Material Traceability. Symrise AG Investor Publications.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Europe natural cosmetics market in 2026 and what is forecast for 2036?
- Which EU anti-greenwashing directives and REACH silicone and microplastic bans support demand for certified natural cosmetics?
- Why does Natural and Organic Facial Skincare lead the product category?
- Why does COSMOS Organic and Natural Certified lead the certification standard category across Europe?
- How do growth rates differ across Germany, Switzerland, and key European markets?
- Which leading companies supply 100% certified anthroposophic skincare versus multinational dermo-botanical lines today?
- What limits essential-oil concentrations or raises audit compliance costs in the Europe natural cosmetics market?
- What should European beauty brands evaluate before the September 2026 enforcement of EU Directive 2024/825?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Category, 2026 to 2036
- Natural and Organic Facial Skincare (Cleansers, Serums, and Creams)
- Natural Haircare (Shampoos, Conditioners, and Hair Oils)
- Natural Body Care (Lotions, Balms, and Body Washes)
- Natural Color Cosmetics and Natural Fragrances
- Y-o-Y Growth Trend Analysis By Product Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Category, 2026 to 2036
- Global Market Analysis and Forecast, By Certification Standard, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Certification Standard, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Certification Standard, 2026 to 2036
- COSMOS Organic and Natural Certified
- NATRUE Certified True Natural
- BDIH Standard Certified
- Ecocert Greenlife Certified and The Vegan Society Trademarked
- Y-o-Y Growth Trend Analysis By Certification Standard, 2021 to 2025
- Absolute $ Opportunity Analysis By Certification Standard, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Organic Health and Wellness Retailers (Bio-Shops)
- Pharmacies and European Apothekens
- Conventional Supermarket Natural Aisles
- Dedicated Brand Online D2C Boutiques
- Prestige Department Stores and Clean-Beauty Perfumeries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Formulation Active Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Formulation Active Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Formulation Active Source, 2026 to 2036
- Botanical Cold-Pressed Oils, Hydrosols, and Plant Extracts
- Biotech-Fermented Peptides and Microalgae Bioactives
- Upcycled Agro-Food Seed and Fruit Peel Actives
- Mineral Pigments and Marine Algae Complexes
- Y-o-Y Growth Trend Analysis By Formulation Active Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Formulation Active Source, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Recycled Glass Jars, Dropper Bottles, and Airless Pumps
- Refillable Pods and In-Store Refill Cartridges
- Post-Consumer Recycled (PCR) Aluminum and Mono-Material Tubes
- Waterless Solid Bars and Paperboard Compacts
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- DACH Region
- Western Europe Core
- Northern Europe & United Kingdom
- Southern Europe
- Central & Eastern Europe
- Southeastern Europe & Baltics
- Primary European Certification Jurisdictions
- Market Attractiveness Analysis By Region
- DACH Region Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Switzerland and Austria
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Western Europe Core Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- Belgium
- Netherlands
- Luxembourg
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Northern Europe & United Kingdom Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Sweden
- Denmark
- Norway
- Finland
- Ireland
- Iceland
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Southern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Italy
- Spain
- Portugal
- Greece
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Central & Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Hungary
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Southeastern Europe & Baltics Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Romania
- Estonia, Latvia, and Lithuania
- Croatia and Slovenia
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Primary European Certification Jurisdictions Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- EU-27 Single Market (Directive 2024/825 & Regulation 1223/2009)
- United Kingdom (UK Cosmetics Regulation & Soil Association)
- Switzerland (FSVO Cosmetics Ordinance)
- European Economic Area (Norway & Iceland)
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Key Takeaways
- Key Countries Market Analysis
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Germany
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Formulation Active Source
- By Packaging Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Weleda AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Dr. Hauschka (WALA GmbH)
- L'Oréal S.A. (Sanoflore)
- Yves Rocher (Groupe Rocher)
- LVMH Moët Hennessy Louis Vuitton
- Lavera Naturkosmetik (Laverana)
- Laboratoires de Biarritz
- LOGOCOS Naturkosmetik
- Laboratoire NUXE
- ANNEMARIE BÖRLIND
- Dr. Hauschka (WALA Heilmittel GmbH)
- Lavera Naturkosmetik (Laverana GmbH)
- LOGOCOS Naturkosmetik GmbH & Co. KG
- L'Oréal S.A. (Sanoflore & La Provençale Bio)
- LVMH Moët Hennessy Louis Vuitton SE
- ANNEMARIE BÖRLIND (Börlind GmbH)
- Weleda AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: DACH Region Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: DACH Region Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 9: DACH Region Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 10: DACH Region Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: DACH Region Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 12: DACH Region Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 13: Western Europe Core Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Core Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 15: Western Europe Core Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 16: Western Europe Core Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Western Europe Core Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 18: Western Europe Core Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Northern Europe & United Kingdom Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Northern Europe & United Kingdom Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 21: Northern Europe & United Kingdom Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 22: Northern Europe & United Kingdom Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Northern Europe & United Kingdom Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 24: Northern Europe & United Kingdom Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 25: Southern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Southern Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 27: Southern Europe Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 28: Southern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Southern Europe Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 30: Southern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: Central & Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: Central & Eastern Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 33: Central & Eastern Europe Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 34: Central & Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: Central & Eastern Europe Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 36: Central & Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 37: Southeastern Europe & Baltics Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: Southeastern Europe & Baltics Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 39: Southeastern Europe & Baltics Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 40: Southeastern Europe & Baltics Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: Southeastern Europe & Baltics Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 42: Southeastern Europe & Baltics Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 43: Primary European Certification Jurisdictions Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Primary European Certification Jurisdictions Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 45: Primary European Certification Jurisdictions Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 46: Primary European Certification Jurisdictions Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Primary European Certification Jurisdictions Market Value (USD Billion) Forecast by Formulation Active Source, 2021 to 2036
- Table 48: Primary European Certification Jurisdictions Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Category
- Figure 6: Global Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Certification Standard
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Formulation Active Source
- Figure 15: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Packaging Format
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: DACH Region Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Western Europe Core Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Northern Europe & United Kingdom Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Southern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Central & Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: Southeastern Europe & Baltics Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Primary European Certification Jurisdictions Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: DACH Region Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: DACH Region Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 30: DACH Region Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 31: DACH Region Market Attractiveness Analysis by Product Category
- Figure 32: DACH Region Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 33: DACH Region Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 34: DACH Region Market Attractiveness Analysis by Certification Standard
- Figure 35: DACH Region Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: DACH Region Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: DACH Region Market Attractiveness Analysis by Distribution Channel
- Figure 38: DACH Region Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 39: DACH Region Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 40: DACH Region Market Attractiveness Analysis by Formulation Active Source
- Figure 41: DACH Region Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 42: DACH Region Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 43: DACH Region Market Attractiveness Analysis by Packaging Format
- Figure 44: Western Europe Core Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Western Europe Core Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 46: Western Europe Core Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 47: Western Europe Core Market Attractiveness Analysis by Product Category
- Figure 48: Western Europe Core Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 49: Western Europe Core Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 50: Western Europe Core Market Attractiveness Analysis by Certification Standard
- Figure 51: Western Europe Core Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Western Europe Core Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Western Europe Core Market Attractiveness Analysis by Distribution Channel
- Figure 54: Western Europe Core Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 55: Western Europe Core Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 56: Western Europe Core Market Attractiveness Analysis by Formulation Active Source
- Figure 57: Western Europe Core Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 58: Western Europe Core Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 59: Western Europe Core Market Attractiveness Analysis by Packaging Format
- Figure 60: Northern Europe & United Kingdom Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Northern Europe & United Kingdom Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 62: Northern Europe & United Kingdom Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 63: Northern Europe & United Kingdom Market Attractiveness Analysis by Product Category
- Figure 64: Northern Europe & United Kingdom Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 65: Northern Europe & United Kingdom Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 66: Northern Europe & United Kingdom Market Attractiveness Analysis by Certification Standard
- Figure 67: Northern Europe & United Kingdom Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Northern Europe & United Kingdom Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Northern Europe & United Kingdom Market Attractiveness Analysis by Distribution Channel
- Figure 70: Northern Europe & United Kingdom Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 71: Northern Europe & United Kingdom Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 72: Northern Europe & United Kingdom Market Attractiveness Analysis by Formulation Active Source
- Figure 73: Northern Europe & United Kingdom Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: Northern Europe & United Kingdom Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: Northern Europe & United Kingdom Market Attractiveness Analysis by Packaging Format
- Figure 76: Southern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Southern Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 78: Southern Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 79: Southern Europe Market Attractiveness Analysis by Product Category
- Figure 80: Southern Europe Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 81: Southern Europe Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 82: Southern Europe Market Attractiveness Analysis by Certification Standard
- Figure 83: Southern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Southern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Southern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Southern Europe Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 87: Southern Europe Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 88: Southern Europe Market Attractiveness Analysis by Formulation Active Source
- Figure 89: Southern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 90: Southern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 91: Southern Europe Market Attractiveness Analysis by Packaging Format
- Figure 92: Central & Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: Central & Eastern Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 94: Central & Eastern Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 95: Central & Eastern Europe Market Attractiveness Analysis by Product Category
- Figure 96: Central & Eastern Europe Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 97: Central & Eastern Europe Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 98: Central & Eastern Europe Market Attractiveness Analysis by Certification Standard
- Figure 99: Central & Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: Central & Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: Central & Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 102: Central & Eastern Europe Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 103: Central & Eastern Europe Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 104: Central & Eastern Europe Market Attractiveness Analysis by Formulation Active Source
- Figure 105: Central & Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 106: Central & Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 107: Central & Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 108: Southeastern Europe & Baltics Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: Southeastern Europe & Baltics Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 110: Southeastern Europe & Baltics Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 111: Southeastern Europe & Baltics Market Attractiveness Analysis by Product Category
- Figure 112: Southeastern Europe & Baltics Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 113: Southeastern Europe & Baltics Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 114: Southeastern Europe & Baltics Market Attractiveness Analysis by Certification Standard
- Figure 115: Southeastern Europe & Baltics Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: Southeastern Europe & Baltics Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: Southeastern Europe & Baltics Market Attractiveness Analysis by Distribution Channel
- Figure 118: Southeastern Europe & Baltics Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 119: Southeastern Europe & Baltics Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 120: Southeastern Europe & Baltics Market Attractiveness Analysis by Formulation Active Source
- Figure 121: Southeastern Europe & Baltics Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 122: Southeastern Europe & Baltics Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 123: Southeastern Europe & Baltics Market Attractiveness Analysis by Packaging Format
- Figure 124: Primary European Certification Jurisdictions Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Primary European Certification Jurisdictions Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 126: Primary European Certification Jurisdictions Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 127: Primary European Certification Jurisdictions Market Attractiveness Analysis by Product Category
- Figure 128: Primary European Certification Jurisdictions Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 129: Primary European Certification Jurisdictions Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 130: Primary European Certification Jurisdictions Market Attractiveness Analysis by Certification Standard
- Figure 131: Primary European Certification Jurisdictions Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Primary European Certification Jurisdictions Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Primary European Certification Jurisdictions Market Attractiveness Analysis by Distribution Channel
- Figure 134: Primary European Certification Jurisdictions Market Value Share and BPS Analysis by Formulation Active Source, 2026 and 2036
- Figure 135: Primary European Certification Jurisdictions Market Y-o-Y Growth Comparison by Formulation Active Source, 2026-2036
- Figure 136: Primary European Certification Jurisdictions Market Attractiveness Analysis by Formulation Active Source
- Figure 137: Primary European Certification Jurisdictions Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 138: Primary European Certification Jurisdictions Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 139: Primary European Certification Jurisdictions Market Attractiveness Analysis by Packaging Format
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Europe natural cosmetics market in 2026, and what is forecast for 2036?
FMI estimates that Europe natural cosmetics demand stood at USD 4.6 billion in 2025 and reached USD 5.0 billion in 2026. Overall valuation is forecast to hit USD 11.4 billion by 2036.
What is the CAGR for the Europe natural cosmetics market from 2026 to 2036?
The Europe natural cosmetics sector is projected to expand at an 8.6% CAGR over the 2026 to 2036 window, adding USD 6.4 billion in incremental retail sales across European markets.
Which product category segment leads the Europe natural cosmetics market?
Natural and Organic Facial Skincare (Cleansers, Serums, and Creams) holds an estimated 48.0% of product category demand in 2026 since daily leave-on barrier serums and moisturizers drive high repeat purchasing.
Which certification standard segment leads the Europe natural cosmetics market?
COSMOS Organic and Natural Certified represents an anticipated 56.0% of the certification standard category in 2026 supported by unified recognition across Ecocert, BDIH, and Soil Association bodies.
Which country has a notable growth outlook during the assessment period?
Germany leads national expansion projections at a 9.5% CAGR through 2036, followed closely by Switzerland at a 9.4% CAGR and the United Kingdom at a 9.2% CAGR.
Who are the key players in the market?
Weleda AG, Dr. Hauschka, L'Oréal S.A., Yves Rocher, LVMH, Lavera Naturkosmetik, Laboratoires de Biarritz, LOGOCOS Naturkosmetik, Laboratoire NUXE, and ANNEMARIE BÖRLIND lead European supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
