

- Market Size (2026)
- USD 5.3 Bn
- Forecast (2036)
- USD 8.4 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Automotive Glass Film Market in 2026?
USD 5.3 billion in 2026 and USD 8.4 billion by 2036 at a 4.6% CAGR.
Automotive glass film demand is projected to rise from USD 5.3 billion in 2026 to USD 8.4 billion by 2036 at 4.6% CAGR. The installed automotive glass base keeps retrofit opportunities active long after first registration across ownership cycles. ACEA reported in January 2026 that 256 million passenger cars were on EU roads during 2024. That fleet depth creates repeated purchase occasions for heat control and glare reduction without relying on new-vehicle production alone.
Country economics diverge as legal light transmission and installer capability determine which functional films convert into completed work. China’s National Bureau of Statistics reported in February 2026 that civilian motor vehicles reached 366.11 million at the end of 2025. A large vehicle parc expands the addressable retrofit pool, but glass-position rules and workmanship requirements still determine the usable specification and the final installation value.
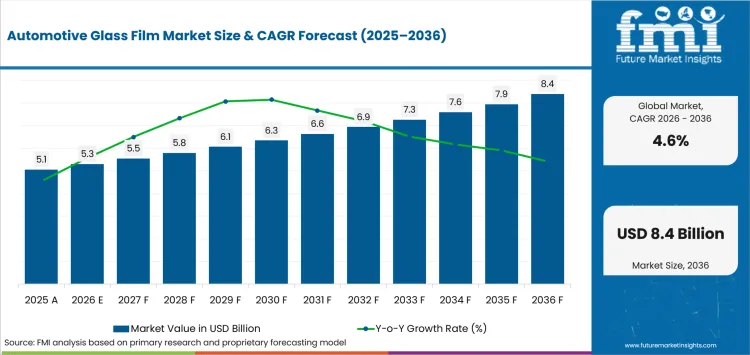
Key Takeaways of Automotive Glass Film Market
- Large vehicle fleets support recurring retrofit demand as owners address cabin heat, glare and privacy needs between vehicle replacement cycles.
- By film type, ceramic films are estimated to hold 37.0% in 2026 owing to metal-free heat control that suits electronics-rich vehicles.
- In 2026, windshields are expected to lead application with 31.0% share because front glazing needs solar control without sacrificing forward visibility.
- Passenger cars are projected to hold 69.0% share in 2026 owing to frequent consumer-led customization across a large installed vehicle base.
- Visible-light-transmission rules and inconsistent fitment constrain conversion as an attractive film loses commercial value if the finished installation is illegal or defective.
- Some of the key players in this market include Eastman Chemical Company, 3M Company, Avery Dennison Corporation, Garware Hi-Tech Films Limited, Madico, Inc., Johnson Window Films, Inc., XPEL, Inc., and LINTEC Corporation.
Analyst Perspective
“Automotive glass film earns a premium when the installed glazing meets heat-rejection targets and local visible-light-transmission rules. The strongest manufacturers pair verified film specifications with installer training that protects optical quality and wireless compatibility while limiting warranty exposure.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the automotive glass film market segmented?
The automotive glass film market is segmented by film type, application, vehicle type, installation, sales channel and region.
Film types include ceramic films, dyed films, nano-ceramic films, metalized films and others. Applications cover windshield, door glass, back glass, moon/sun roof, quarter glass and vent glass. Vehicle types comprise passenger cars, light commercial vehicles, heavy commercial vehicles and off-highway vehicles. Installation covers aftermarket and OEM/factory-fitted work. Sales channels include authorized installers, automotive dealers, independent aftermarket and online/retail.
Why do ceramic films lead the film type category?
Ceramic films manage solar heat without metallic layers that can interfere with signal-sensitive vehicle electronics across connected cabins and forward-view glazing. Avery Dennison introduced its Encore series in February 2025 with a metal-free nanoceramic Supreme IR tier that extends high infrared rejection to functional films and clearer UV-blocking films.
- By film type, ceramic films are estimated to hold 37.0% in 2026 owing to metal-free heat control that protects wireless connectivity.
- Installers can sell a premium heat-control upgrade without deep visible tint while preserving navigation signals and consistent optical quality across modern passenger vehicle cabin systems.
Why do passenger cars lead the vehicle type category?
Passenger cars generate frequent customization purchases as private owners revisit cabin comfort and appearance throughout ownership. Sensor-rich cabins and automotive HUD zones also raise the value of films that preserve optical clarity across windshields and side glass near cameras and other forward-view sensors.
- Passenger cars are projected to hold 69.0% share in 2026 owing to frequent consumer-led customization across a large installed vehicle base.
- Federal Highway Administration data published in January 2026 counted 97,413,321 registered passenger automobiles in the United States for 2024. That mature fleet gives installers repeated retrofit occasions beyond annual new-vehicle sales and dealer accessory programs.
Why does aftermarket lead the installation category?
Aftermarket work reaches vehicles already in service and lets installers tailor film to ownership changes or climate exposure. SEMA reported in June 2025 that USA consumers spent about USD 52.65 billion accessorizing and modifying vehicles during 2024, giving shops that fit anti-scratch films a substantial paid personalization base for related glass upgrades.
- In 2026, aftermarket is expected to lead installation with 72.0% share because retrofit demand extends beyond annual new-vehicle production.
- The same customer visit lets specialist shops sell heat control beside protection work while spreading acquisition costs across several vehicle-care services within one scheduled installation appointment.
Why do authorized installers lead the sales channel category?
Authorized installers sell workmanship with the film because contamination and poor edge finishing can erase a premium while anti-glare film around sensor zones leaves little tolerance for optical defects.
- By sales channel, authorized installers are forecast to represent 44.0% in 2026 driven by warranty-backed fitment that reduces authenticity and rework risk.
- Garware Hi-Tech Films held an applicator competition in Lucknow, India during June 2026 with live speed and precision challenges. The event paired professional window-film masterclasses with hands-on assessment and exposed applicators to preparation discipline needed for repeatable warranty-backed work on curved automotive glazing consistently worldwide.
What are the drivers, restraints and opportunities in the Automotive Glass Film Market?
Large vehicle fleets and recurring cabin-comfort upgrades support demand, while legal light-transmission limits restrict installation choices and transparent ceramic films create the clearest premium route.
- Driver: Installed vehicle fleets sustain paid retrofit work as owners revisit heat control and customization during normal ownership cycles.
- Restraint: Light-transmission rules and workmanship failures raise the risk that requested tint cannot become a compliant finished installation.
- Opportunity: High-transparency metal-free films preserve visibility and signal performance while improving heat rejection on demanding glazing positions.
Installed Fleets Sustain Recurring Retrofit Work
Active vehicle fleets return to installers for heat and appearance upgrades long after first registration. XPEL reported in February 2026 that automotive window-film revenue rose 21.7% during 2025 as sales increased across several regions. Similar compatibility checks affect adjacent transparent conductive films, but automotive film revenue depends on clean fitment and legally usable specifications that preserve repeat business across service networks.
Compliance Friction Limits Front-Glass Conversion
Front glazing carries the highest conversion risk because heat performance does not guarantee legal light transmission. DVSA found in January 2025 that 25 of 42 customer-install tint products gave no information on current tint rules. Electrochromic glass requires similar specification discipline because installed film must preserve lawful visibility and optical performance across the completed glazing system during routine vehicle operation.
Transparent Ceramic Films Extend Premium Applications
Premium demand concentrates on films that reject infrared heat without requiring visibly dark tint across forward-view glazing. LINTEC said in May 2025 that it planned to expand Japanese sales of highly transparent heat-resistant automotive window films launched the prior year. The same requirement applies to AR windshield films because front-glass upgrades must protect optical clarity near sensors while managing heat at usable light-transmission levels.
Which country CAGRs are profiled in the Automotive Glass Film Market?
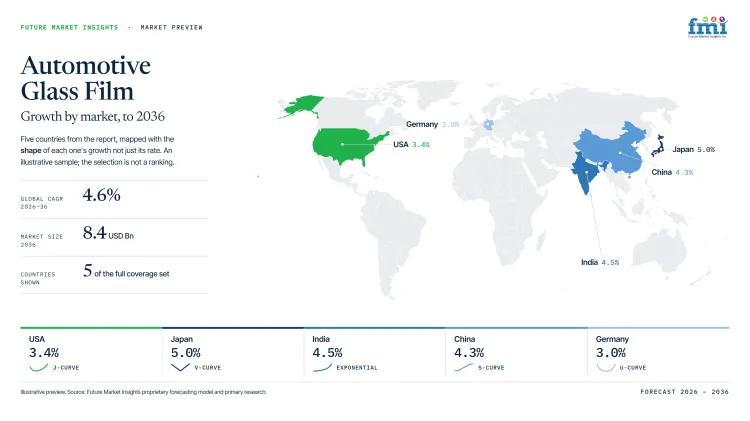
| Country | CAGR |
|---|---|
| Mexico | 5.1% |
| Japan | 5.0% |
| Brazil | 4.8% |
| United States | 3.4% |
| Germany | 3.0% |
How do country-level CAGRs compare in the Automotive Glass Film Market?
The 2.1 percentage-point range between Mexico and Germany separates retrofit expansion from replacement economics. Mexico and Japan form the upper pair near 5.0% while Brazil remains close enough to justify installer investment. The United States and Germany expand more slowly, so premium mix and service productivity matter more than category growth.
- Mexico converts new-car turnover into tinting work across state enforcement systems.
- Japan rewards transparent front-glass film as MLIT enforcement requires measured light transmission.
- Brazil’s large vehicle fleet supports replacement work under position-specific non-reflective film rules.
- United States customization spending converts through restyling shops despite different state tint limits.
- Germany relies on premium replacement work as slow fleet growth raises documentation value.
Similar growth rates mask different entry conditions across fleet depth and enforcement. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- Mexican vehicle-film sales benefit from a growing new-car flow and a sizeable retrofit base across state-level registration environments where enforcement practices vary. Mexico is forecast to expand at 5.1% CAGR through 2036, driven by August 2026 INEGI data showing 885,353 light vehicles sold domestically from January through July, 5.04% above the same 2025 period. Added vehicle turnover creates fresh tinting occasions and supports premium heat-control packages. Local compliance interpretation and inconsistent installer quality make distributor training and clearly labeled visible-light-transmission ranges essential for brands seeking repeatable coverage beyond the largest metropolitan areas and secondary urban markets.
- Japan favors disciplined front-glass installation because MLIT enforcement treats sub-70% visible-light transmission on windshield and front-side film as a priority illegal modification across a vehicle stock exceeding 80 million. This framework is attributable to demand for highly transparent ceramic grades, documented post-installation measurement and tight optical tolerances, particularly on curved glass or sensor zones. Automotive glass film demand in Japan is forecast to rise at 5.0% CAGR over the forecast period, with specialist installers using April 2026 regulatory guidance to build higher-confidence premium work across a mature vehicle base that values optical quality, factory-like appearance, documented compliance and measured installation discipline.
- In Brazil, installers operate in a very large vehicle fleet where film selection must match the glass position and the combined visible-light-transmission result. Brazil is estimated to post 4.8% CAGR over the forecast period, supported by the transport ministry’s national fleet series showing about 129.1 million registered vehicles for December 2025. Fleet depth underpins recurring replacement and heat-control work, yet long service distances outside major cities and compliance checks favor manufacturers that train regional applicators and provide non-reflective product ranges with clear technical labeling for windshield and other visibility-critical applications across coastal and inland service corridors with uneven service density.
- The United States remains highly installer-based, with owners often purchasing appearance and comfort upgrades through independent restyling shops alongside dealer channels. SEMA reported in 2026 that about one in four vehicle owners purchased accessory or performance products for personalization during 2025, creating a broad paid aftermarket while leaving legal friction in place. Demand for automotive glass film in the United States is projected to record 3.4% CAGR during the assessment period, attributable to state-by-state tint limits and warranty exposure that reward brands with broad shade ladders, documented installation guidance and dealer support that keeps front-side work inside local rules across hot-climate states and dense urban markets.
- Germany’s film market depends on premium replacement work across a mature passenger-car base where optical quality outweighs deep tinting. The country’s automotive glass film outlook is anticipated to advance at 3.0% CAGR over the assessment period, reflecting Federal Ministry of Transport data from March 2026 showing passenger-car stock at 49.5 million in July 2025 with only 0.3% year-over-year growth. Slow fleet expansion increases the value of higher-grade heat-control film for specialist installers, while technical approval expectations around front-glass cameras and driver-assistance zones raise the cost of weak documentation or inconsistent workmanship.
Who are the notable companies in the Automotive Glass Film Market?
Eastman Chemical Company, 3M Company, Avery Dennison Corporation, Garware Hi-Tech Films Limited, Madico, Inc., Johnson Window Films, Inc., XPEL, Inc. and LINTEC Corporation are the notable companies serving this market.
Competition turns on heat-control chemistry and installer support. Eastman and 3M run broad branded platforms while Avery Dennison and LINTEC focus on heat-control constructions. XPEL links film sales with installation while Garware, Madico and Johnson rely on applicator networks serving low-haze windshield coatings.
- Eastman Chemical Company, 3M Company and Avery Dennison Corporation operate broad automotive-film platforms.
- Garware Hi-Tech Films Limited, Madico, Inc. and Johnson Window Films, Inc. focus on film production and dealer distribution.
- XPEL, Inc. and LINTEC Corporation use direct or distributor-led installer routes.
Competitive Benchmarking: Automotive Glass Film Market
| Company | Automotive Film Portfolio Depth | Installer and Dealer Support | Automotive Glazing Coverage | Geographic Reach |
|---|---|---|---|---|
| Eastman Chemical Company | High | High | High | Global |
| 3M Company | High | High | Medium | Global |
| Avery Dennison Corporation | High | High | Medium | North America, Europe and Asia-Pacific |
| Garware Hi-Tech Films Limited | High | High | High | India and international markets |
| Madico, Inc. | High | High | High | North America, Europe and Latin America |
| Johnson Window Films, Inc. | Medium | Medium | Medium | North America and Europe |
| XPEL, Inc. | High | High | High | North America, Europe, China and Asia-Pacific |
| LINTEC Corporation | Medium | Medium | High | Japan, North America and Asia |
Scoring basis: High portfolio depth requires three verified automotive film families while Medium requires two and Low one. High channel support requires training plus an authorized or direct installation route while Medium requires one formal support route and Low distribution. High glazing coverage requires tint plus windshield or protection-film capability while Medium covers multiple tint constructions and Low one glazing route.
Key Developments in the Automotive Glass Film Market
- In July 2026, Garware Hi-Tech Films Limited conducted a certification workshop in Siliguri with hands-on installation training for automotive heat-rejection film and protective glass coatings.
- In January 2026, Madico, Inc. entered a definitive agreement to acquire Johnson Laminating & Coating and Johnson Window Films while retaining the Johnson brand and dealer network.
- In September 2025, XPEL, Inc. acquired assets from its exclusive China distributor and obtained a 76% controlling interest in a new Shanghai entity to establish direct market presence.
Key Players in the Automotive Glass Film Market
Diversified Film and Materials Platforms
- Eastman Chemical Company
- 3M Company
- Avery Dennison Corporation
Specialist Film and Installation Platforms
- Garware Hi-Tech Films Limited
- Madico, Inc.
- Johnson Window Films, Inc.
- XPEL, Inc.
Japanese Automotive Film Platform
- LINTEC Corporation
Automotive Glass Film Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By film type, application, vehicle type, installation, sales channel and region. |
| Quantitative Units | USD billion. |
| Market Definition | Revenue from automotive glass film sold for vehicle glazing across thermal-control, tint, privacy, safety and windshield-protection uses within the stated taxonomy. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | Mexico, Japan, Brazil, United States, Germany, and 20+ countries included in the full report. |
| Key Companies Profiled | Eastman Chemical Company, 3M Company, Avery Dennison Corporation, Garware Hi-Tech Films Limited, Madico, Inc., Johnson Window Films, Inc., XPEL, Inc., LINTEC Corporation. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Automotive Glass Film Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Automotive Glass Film Market by Segments
Automotive Glass Film Market segmented by Film Type:
- Ceramic Films
- Dyed Films
- Others
- Nano-Ceramic Films
- Metalized Films
Automotive Glass Film Market segmented by Application:
- Windshield
- Door Glass (Side Window)
- Back Glass (Safety Window)
- Moon/Sun Roof
- Quarter Glass
- Vent Glass
Automotive Glass Film Market segmented by Vehicle Type:
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Off-highway Vehicles
Automotive Glass Film Market segmented by Installation:
- Aftermarket
- OEM / Factory-fitted
Automotive Glass Film Market segmented by Sales Channel:
- Authorized Installers
- Automotive Dealers
- Independent Aftermarket
- Online / Retail
Automotive Glass Film Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- European Automobile Manufacturers’ Association. (2026, January 15). Report - Vehicles on European roads 2026.
- National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People’s Republic of China on the 2025 national economic and social development.
- Avery Dennison Graphics Solutions. (2025, February 25). Avery Dennison introduces new Encore series of automotive window films that redefine performance and style.
- Federal Highway Administration. (2026, January). Highway Statistics 2024: Table MV-1.
- Specialty Equipment Market Association. (2025, June 30). New SEMA research: 2025 market report.
- Garware Hi-Tech Films Limited. (2026, July 3). Garware Window Film & PPF Training Program.
- XPEL, Inc. (2026, February 27). Annual report for the fiscal year ended December 31, 2025.
- Driver and Vehicle Standards Agency. (2025, January 21). Vehicle Market Surveillance Unit: Results of the 2024 programme.
- LINTEC Corporation. (2025, May 15). Financial results briefing for the fiscal year ended March 31, 2025.
- Instituto Nacional de Estadística y Geografía. (2026, August 7). Registro Administrativo de la Industria Automotriz de Vehículos Ligeros, julio de 2026.
- Ministry of Land, Infrastructure, Transport and Tourism. (2026, April). Implementation guidelines for the campaign to eliminate illegally modified vehicles.
- Ministério dos Transportes. (2026, March 30). Frota de veículos - 2025.
- Intraplan Consult GmbH & Bundesamt für Logistik und Mobilität. (2026, March). Gleitende Mittelfristprognose für den Güter- und Personenverkehr - Mittelfristprognose Winter 2025/26.
- Specialty Equipment Market Association. (2026, June). New 2026 SEMA market report reveals a nearly USD 53 billion aftermarket.
- Madico, Inc. (2026, June 24). Madico expands sales organization to strengthen dealer support and regional market coverage.
- 3M. (2025, September 8). 3M at IAA Mobility 2025: What the automotive industry needs next, 3M is innovating now.
- Eastman Chemical Company. (2026, February 13). Annual report on Form 10-K for the year ended December 31, 2025.
- Madico, Inc. (2026, January 21). Madico to acquire Johnson Window Films.
- Johnson Window Films, Inc. (2026, January 21). Madico to acquire Johnson Window Films.
- Avery Dennison Graphics Solutions. (2026, April). Automotive window film training and certification schedule.
- Garware Hi-Tech Films Limited. (2026, January 31). Investor presentation for the period ended December 31, 2025.
- XPEL, Inc. (2026, May 8). Quarterly report on Form 10-Q for the quarter ended March 31, 2026.
- LINTEC Corporation. (2026, May 8). Consolidated financial results for the fiscal year ended March 31, 2026.
- STEK USA. (2025, December 31). Leveling up window tint.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What are the 2026 and 2036 automotive glass film values?
- Why do ceramic films lead the film type category in 2026?
- Why do passenger cars lead vehicle type demand in 2026?
- Why does aftermarket installation generate recurring automotive glass film work?
- How do growth rates compare across the five profiled countries?
- Which companies pair film technology with installer and channel support?
- How do light-transmission rules and workmanship failures restrict installations?
- How should installers evaluate premium heat-control film?
Frequently Asked Questions
How big is the automotive glass film market in 2026?
The automotive glass film market is valued at USD 5.3 billion in 2026 and is projected to reach USD 8.4 billion by 2036. Growth is driven by recurring retrofit demand from large global vehicle fleets seeking heat reduction, glare control, and privacy enhancement.
What is the CAGR of the automotive glass film market from 2026 to 2036?
The automotive glass film market is projected to grow at a CAGR of 4.6% between 2026 and 2036. Expansion is supported by rising adoption of solar-control and comfort-enhancing films across passenger and commercial vehicles.
Which film type leads the automotive glass film market?
Ceramic films are projected to account for 37.0% of the market in 2026. Their leading share is supported by metal-free heat rejection, signal compatibility, and suitability for modern electronics-rich vehicles.
Which application dominates the automotive glass film market?
Windshield applications are projected to account for 31.0% of the market in 2026. Their dominance reflects growing demand for solar control and glare reduction while maintaining visibility and compliance with safety requirements.
Which vehicle type leads the automotive glass film market?
Passenger cars are projected to account for 69.0% of the market in 2026. Their leading share is driven by a large installed vehicle base and sustained consumer demand for customization and cabin-comfort upgrades.
Which installation type leads the automotive glass film market?
Aftermarket installations are projected to account for 72.0% of the market in 2026. Their dominance is supported by extensive retrofit activity and growing demand for vehicle personalization beyond factory-fitted solutions.
Which sales channel leads the automotive glass film market?
Authorized installers are projected to account for 44.0% of the market in 2026. Their leading share reflects consumer preference for warranty-backed installations, professional workmanship, and compliance with local regulations.
Which companies are active in the automotive glass film market?
Key companies operating in the market include Eastman Chemical Company, 3M Company, Avery Dennison Corporation, Garware Hi-Tech Films Limited, Madico, Inc., Johnson Window Films, Inc., XPEL, Inc., and LINTEC Corporation. These companies compete through advanced film technologies, installer networks, product innovation, and global distribution capabilities.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Film Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Film Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Film Type, 2026 to 2036
- Ceramic Films
- Dyed Films
- Others
- Nano-Ceramic Films
- Metalized Films
- Ceramic Films
- Y-o-Y Growth Trend Analysis By Film Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Film Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Windshield
- Door Glass (Side Window)
- Back Glass (Safety Window)
- Moon-Sun Roof
- Quarter Glass
- Vent Glass
- Windshield
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Off-highway Vehicles
- Passenger Cars
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Installation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Installation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Installation, 2026 to 2036
- Aftermarket
- OEM - Factory-fitted
- Aftermarket
- Y-o-Y Growth Trend Analysis By Installation, 2021 to 2025
- Absolute $ Opportunity Analysis By Installation, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Authorized Installers
- Automotive Dealers
- Independent Aftermarket
- Online - Retail
- Authorized Installers
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Film Type
- By Application
- By Vehicle Type
- By Installation
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Eastman Chemical Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Saint-Gobain S.A.
- 3M Company
- Lintec Corporation
- Avery Dennison Corporation
- Garware Hi-Tech Films Limited
- Johnson Window Films, Inc.
- Madico, Inc.
- Nexfil Co., Ltd.
- Solar Gard (Saint-Gobain)
- Eastman Chemical Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


