

- Market Size (2026)
- USD 72.9 Bn
- Forecast (2036)
- USD 127.0 Bn
- CAGR (2026 to 2036)
- 5.7%
How big is Automotive ECU Market in 2026?
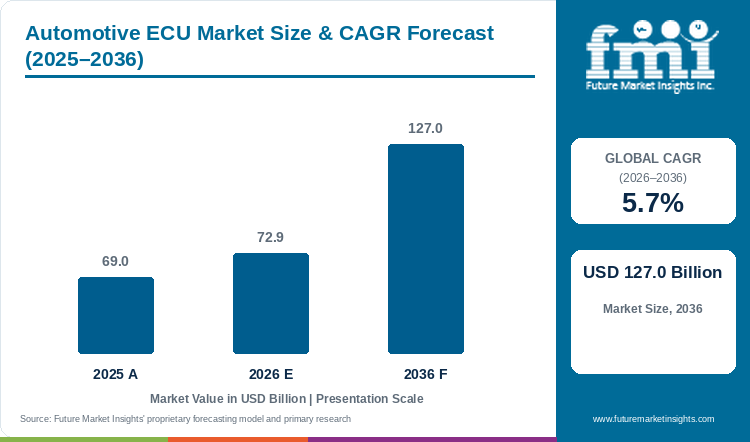
Electronic control units for vehicles carry a 5.7% CAGR over 2026 to 2036. Sales stood at USD 69.0 billion in 2025, are estimated at USD 72.9 billion for 2026 and are projected to reach USD 127.0 billion by 2036.
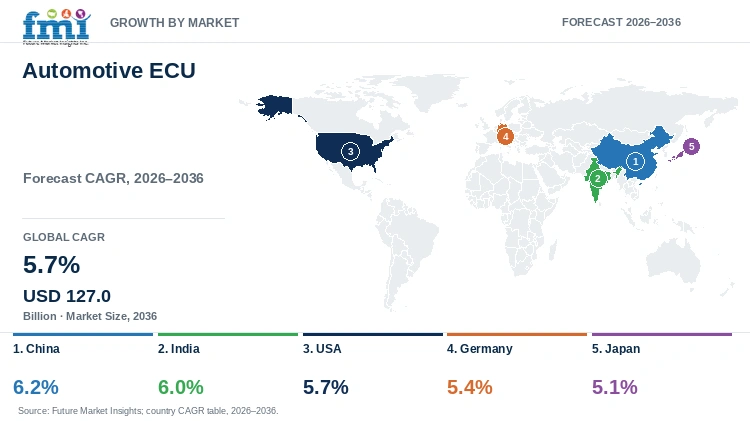
The automotive ECU market size stood at USD 69.0 billion in 2025 and is estimated at USD 72.9 billion in 2026. FMI’s analysis indicates that the market is projected to reach USD 127.0 billion by 2036, at a 5.7% CAGR from 2026 to 2036. China leads at a 6.2% CAGR from 2026 to 2036 on electric car output, and India follows at 6% on truck and bus growth. Sales in the USA match the 5.7% global CAGR, Germany grows at 5.4%, and Japan, at 5.1%, is the slowest of the five, as home new car sales of 4,565,777 units in 2025 stayed short of the 5 million sold before the pandemic.
China’s GB 39901-2025 AEB rule is raising the bar for safety ECUs. Due to this, carmakers building light vehicles for China are ordering braking and sensor fusion controllers ahead of 1 January 2028. Each added controller carries more silicon, and the automotive semiconductor market is forecast at a 6.8% CAGR from 2026 to 2036 as carmakers order more chips per vehicle. NXP reported automotive revenue of $1,938 million for Q2 2026, up 12% on Q2 2025.[1] NXP’s 12% automotive gain shows chip makers unlocking value across the supply chain as carmakers fit more controllers per vehicle. The parent automotive electronics market runs at a 4.6% CAGR over 2026 to 2036, so control units on a 5.7% CAGR will gain share of vehicle electronics. Passenger cars take 64% of 2026 vehicle type sales, and every new car model needs body, safety and powertrain controllers.
Key Market Trends & Insights
- Passenger vehicles hold 64% of 2026 vehicle type sales in the FMI study, with a 5.9% CAGR from 2026 to 2036.
- Sales of battery ECUs follow electric car output, and battery-powered vehicles held 41% of propulsion sales in 2026. Gasgoo, citing CAAM, reported that NEV production and sales in China passed 16 million units in 2025.[2]
- Cost and processing headroom favour 32-bit units, at an estimated 46.8% of ECU capacity sales.
- ADAS and safety systems, near 31.4% (estimated), form the largest application on the back of braking and collision rules.
- Carmakers buy most controllers at the assembly stage, giving OEM supply about 83.6% (estimated) of 2026 channel sales.
Regional Highlights
- Quickest growth belongs to China, at 6.2% from 2026 to 2036, as FMI predicts.
- Indian sales grow at 6%, US sales match the global 5.7%, and Germany (5.4%) and Japan (5.1%) are slower.
- China issued GB 39901-2025, which makes AEB standard equipment for light-duty vehicles, effective 1 January 2028.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive ECU Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 69.0 billion |
| Estimated Market Size in 2026 | USD 72.9 billion |
| Projected Market Size by 2036 | USD 127.0 billion |
| CAGR, 2026 to 2036 | 5.7% |
| Added Revenue, 2026 to 2036 | USD 54.1 billion |
| Market Expansion Multiple | 1.7x |
China leads ECU expansion over the forecast in the view of analysts at FMI. Electric drive programs add battery management and motor control units on each new model. Every electric battery pack needs a battery management ECU, so growth of the electric vehicle battery market at an 8.5% CAGR from 2026 to 2036 will keep battery controller orders rising. Faster pack sales will move ECU content toward high-voltage control.
Semiconductor Supply Signals for ECU Programs
Chip makers report demand for ECUs before carmakers do, because silicon ships months ahead of vehicle assembly. NXP cited software-defined vehicles as a company growth driver in July 2026, with automotive revenue up 9% from the prior quarter.[1] Infineon said positive momentum in software-defined vehicles continues, offset by subdued demand for high-voltage electromobility components.[4] Automotive orders at Infineon were picking up noticeably, chief executive Jochen Hanebeck said in August 2026.[4] Bosch began sending third-generation silicon carbide chip samples to automakers in April 2026, with 20 percent higher performance.[5] DENSO Manufacturing Tennessee produces the inverter for a two-motor hybrid drive module on the new Jeep Cherokee.[6] Each hybrid inverter adds a control board to the vehicle. Slower high-voltage demand will hold back battery-powered ECU volume in 2026, and hybrid control units will fill part of the gap.
Table 2: Semiconductor and Program Indicators for the Automotive ECU Market (USD, percentage and dates), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| NXP automotive revenue, Q2 2026 | $1,938 million, up 12% year on year | Chip shipments lead ECU builds. | [1] |
| NXP automotive revenue change versus Q1 2026 | Up 9% | Quarter-on-quarter order momentum. | [1] |
| Infineon group revenue, Q3 FY2026 | €4.172 billion | Record quarter for an automotive chip supplier. | [4] |
| Infineon automotive contribution to sequential revenue increase | €102 million | Automotive orders picking up. | [4] |
| Bosch third-generation SiC chips, April 2026 | 20 percent higher performance | Power chips for electric drive control. | [5] |
| China NEV production and sales, 2025 | More than 16 million units | Base for demand for battery-powered ECUs. | [2] |
| China AEB standard GB 39901-2025 | Takes effect 1 January 2028 | ADAS and safety ECUs become standard on light-duty vehicles. | [3] |
| US FMVSS 127 AEB compliance date | 1 September 2029 | Federal deadline for crash mitigation features. | [7] |
Analyst Perspective
“Carmakers will choose 64-bit central controllers for new software-defined platforms, since a 64-bit controller can take over-the-air updates for ADAS and safety functions. I expect Chinese buyers to make that choice first, ahead of the 2028 AEB rule, and US buyers to follow as the FMVSS 127 date nears.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive ECU market segmented?
Five product axes and region define the automotive ECU market. Passenger vehicles hold 64% and battery-powered models 41% in 2026, with 32-bit units, ADAS and safety systems and OEM supply leading the other axes on estimated shares.
By vehicle type: passenger vehicle, heavy commercial vehicle, and electric vehicle.
By propulsion type: battery powered, hybrid, and internal combustion engine.
By ECU capacity: 16-bit, 32-bit, and 64-bit.
By application: ADAS and safety system, body control and comfort system, infotainment and communication system, and powertrain system.
By sales channel: OEM and aftermarket.
By region: ECU coverage counts East Asia, South Asia and Pacific, two American regions (North and Latin), two European regions (Western and Eastern), and Middle East and Africa.
Why do passenger vehicles lead vehicle type sales?
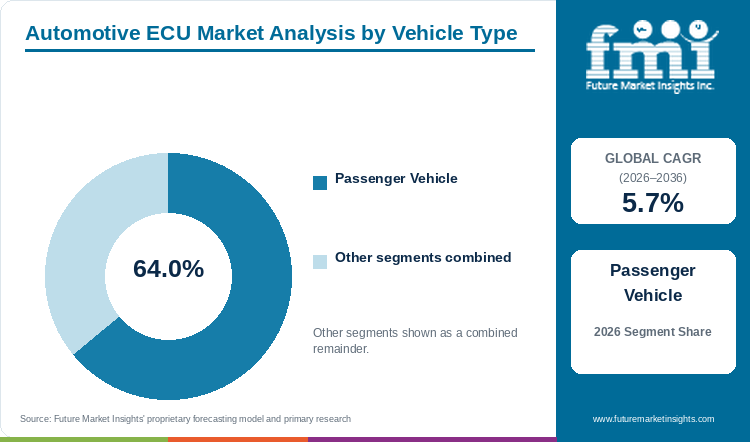
Passenger vehicles account for 64% of 2026 vehicle type sales, electric vehicles for an estimated 21.3% and heavy commercial vehicles for about 14.7%.
Table 3: Vehicle Type Share for the Automotive ECU Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Vehicle | 64% |
| Electric Vehicle | 21.3% |
| Heavy Commercial Vehicle | 14.7% |
| Total | 100.0% |
Table 4: Vehicle Type Leadership and Market Growth for the Automotive ECU Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.7% |
| Leading Segment | Passenger Vehicle |
Passenger vehicles lead on sheer volume, holding 64% of vehicle type sales according to FMI’s report. CAAM data carried by Gasgoo show 34.531 million vehicles produced in China during 2025.[2] Electric vehicles, at about 21.3% (estimated), carry battery and motor controllers on top of body and safety units. China built just over 16 million NEVs in 2025 out of 34.531 million vehicles, so electric models are still fewer than other cars.[2] Heavy commercial vehicles hold an estimated 14.7%, as truck volumes are small and many fleets replace vehicles on long cycles.
- Chinese commercial vehicle production and sales both rose more than 10% in 2025.[2]
Why do battery-powered vehicles hold the top propulsion share?
Battery-powered vehicles hold 41% of 2026 propulsion sales, internal combustion engine models an estimated 36.5% and hybrids about 22.5%.
Table 5: Propulsion Type Share for the Automotive ECU Market (percentage share), 2026
| Propulsion Type | Estimated Share (2026) |
|---|---|
| Battery Powered | 41% |
| Internal Combustion Engine | 36.5% |
| Hybrid | 22.5% |
| Total | 100.0% |
German plants built 1.67 million electric cars in 2025, up 23%, AUTOHAUS reported in February 2026.[8] The updated report by FMI puts battery-powered vehicles at 41% of propulsion sales, on a 6.3% CAGR from 2026 to 2036, since each battery model needs control units for charging, thermal and battery management. Combustion models keep an estimated 36.5%, and falling combustion output at German plants is shrinking that pool. Hybrids hold about 22.5% (estimated), held back by smaller model ranges, although each hybrid needs both engine and motor controllers. In Germany, plug-in hybrid production jumped 54% to 450,000 vehicles and led the rise in electric output.[8]
- Engine and transmission ECUs will stay in demand through 2036 on combustion models, still near 36.5% (estimated).
- Plug-in hybrids add a charger controller on top of engine and motor units.
Why do 32-bit units lead ECU capacity sales?
32-bit ECUs take an estimated 46.8% of 2026 capacity sales, 64-bit units about 31.5% and 16-bit units about 21.7%.
Table 6: ECU Capacity Share for the Automotive ECU Market (percentage share), 2026
| ECU Capacity | Estimated Share (2026) |
|---|---|
| 32-bit | 46.8% |
| 64-bit | 31.5% |
| 16-bit | 21.7% |
| Total | 100.0% |
Unit cost and processing headroom decide each controller choice at the carmaker, and 32-bit units balance both at an estimated 46.8%. 64-bit units, about 31.5% (estimated), cost more per board and go mainly into ADAS and central computing programs. 16-bit designs, near 21.7% (estimated), lack the memory for over-the-air updates, which confines them to simple actuators and window and seat modules. Microcontroller suppliers ship the chips for both 32-bit and 64-bit designs, so each new ECU award adds to growth of the automotive microcontroller market.
Why do ADAS and safety systems lead application sales?
ADAS and safety systems top application sales, near 31.4% in 2026 (estimated), with powertrain next at about 28.6%.
Table 7: Application Share for the Automotive ECU Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| ADAS and Safety System | 31.4% |
| Powertrain System | 28.6% |
| Body Control and Comfort System | 22.3% |
| Infotainment and Communication System | 17.7% |
| Total | 100.0% |
Braking and collision rules make safety controllers mandatory on new cars, and ADAS and safety systems hold about 31.4% of the application split (estimated). NHTSA set 1 September 2029 as the FMVSS 127 deadline for automatic emergency braking and other crash mitigation features, Nelson Mullins wrote in April 2026.[7] Powertrain systems, near 28.6% (estimated), come second, as every combustion, hybrid and battery model still needs engine or motor control. Body control and comfort take an estimated 22.3%, with each module priced low. Infotainment and communication, about 17.7% (estimated), is moving into central computers, so fewer stand-alone units ship per car.
- Infotainment and communication ECUs carry V2X and over-the-air update functions.
Why does OEM supply lead sales channel sales?
Carmaker contracts give OEM supply about 83.6% of 2026 channel sales (estimated), leaving roughly 16.4% to the aftermarket.
Table 8: Sales Channel Share for the Automotive ECU Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| OEM | 83.6% |
| Aftermarket | 16.4% |
| Total | 100.0% |
OEM supply keeps about 83.6% (estimated), because ECUs are coded to one vehicle platform and carmakers buy most units at assembly. The aftermarket, at about 16.4%, is held back by software pairing and by repair shops that often fix modules instead of replacing them. Over-the-air updates will extend the life of fitted ECUs and cap replacement volume.
What are the drivers, restraints, and opportunities in the automotive ECU market?
Demand for automotive ECUs is rising with China’s 2028 AEB mandate, the FMVSS 127 braking rule in the USA and hybrid programs such as the Jeep Cherokee drive module. ECU suppliers face softer high-voltage chip demand and longer software validation.
- Driver: AEB and crash-avoidance rules in China and the USA.
- Restraint: Subdued demand for high-voltage electromobility parts.
- Opportunity: Controllers for hybrid drive modules and software-defined platforms.
Braking Mandates Put Safety Controllers on Every Light Vehicle
MIIT announced that GB 39901-2025 was approved for release on 31 December 2025, with an effective date of 1 January 2028.[3] Passenger vehicles need to activate AEB automatically between 10 and 80 km/h under the rule.[3] Every light-duty model built for China after 2027 needs a braking controller and sensor fusion unit. ADAS ECU orders for Chinese programs will rise ahead of the 2028 date.
High-Voltage Softness Slows Battery Controllers
Electric drive parts face a soft patch in 2026. Infineon cited subdued demand for high-voltage components in electromobility in August 2026.[4] Infineon also guided the automotive segment to grow slower than the group average for FY2026.[4] Battery management and inverter controllers will see slower orders in 2026, and suppliers will shift capacity to hybrid and ADAS lines.
Hybrid Drive Modules Add Control Content
Hybrid platforms carry two power sources and need extra controllers. DENSO said on 27 August 2026 that a two-motor hybrid drive module, jointly developed with BluE Nexus and AISIN, went into the Stellantis Jeep Cherokee.[6] The module optimizes control of the motor and the boost converter.[6] DENSO Manufacturing Tennessee builds the inverter for the module, so the Jeep program adds US orders for inverter and motor controllers.[6] Each new module also needs control code from software suppliers, and the automotive software market will expand with every hybrid program.
Which country CAGRs are profiled in the automotive ECU market?
Table 9: Country CAGR Comparison for the Automotive ECU Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 6.2% |
| India | 6% |
| USA | 5.7% |
| Germany | 5.4% |
| Japan | 5.1% |
How do country-level CAGRs compare in the automotive ECU market?
China made AEB standard equipment on light-duty vehicles under GB 39901-2025, effective 1 January 2028, and FMI ranks China first at 6.2% from 2026 to 2036.[3] India comes next at 6%, after commercial vehicle wholesales rose 12.6% in FY26, and the changing geography of production is moving truck ECU orders to Indian plants.[9] US growth equals the 5.7% global CAGR, on safety regulation. Germany at 5.4% and Japan at 5.1% grow below the global rate.
- NEVs took over half of Chinese new-car sales in 2025, and each one adds battery and motor controllers.
- Truck and bus programs carry India at 6%, the second-fastest profiled rate.
- US carmakers face a 1 September 2029 FMVSS 127 deadline for automatic emergency braking.
- Record electric car output at German plants keeps battery controller work at home.
- Japan grows slowest, as domestic car sales are only now recovering.
Full report country CAGRs cover: more than 30 countries across seven ECU regions.
Country-wise Analysis
Germany Automotive ECU Market Outlook (2026 to 2036)
Four in ten cars built in Germany in 2025 were electric, AUTOHAUS reported.[8] Battery-electric output rose 15% to 1.22 million units.[8] German ECU sales grow at a 5.4% CAGR from 2026 to 2036. Electric output gives German suppliers steady battery and motor controller work at home.
Key takeaway: German growth comes from electric model output at home plants, so battery management ECUs will gain share.
USA Automotive ECU Market Outlook (2026 to 2036)
The DOT said in March 2026 that the department is preparing a proposal to amend FMVSS 127 and give OEMs two more years, Nelson Mullins reported.[7] The September 2029 deadline stays in place unless the change is adopted.[7] US ECU sales grow at a 5.7% CAGR through 2036, level with the global rate. A two-year delay would move part of the AEB controller volume past 2029.
Key takeaway: The final FMVSS 127 timeline will decide when US ADAS controller orders peak.
China Automotive ECU Market Outlook (2026 to 2036)
NEVs took more than 50% of Chinese new-car sales in 2025.[2] NEV volume puts China ahead of the profiled countries for ECU growth, at a 6.2% CAGR. The GB 39901-2025 AEB rule adds a safety controller to every light-duty model from 2028.[3] Chinese programs will therefore order ADAS controllers in bulk before the 2028 date.
Key takeaway: China gives ECU makers both the largest EV base and a firm AEB date.
Japan Automotive ECU Market Outlook (2026 to 2036)
Jiji Press put 2025 Japanese new vehicle sales at 4,565,777 units, up 3.3% but still short of the 5 million units sold before the pandemic.[10] Japan grows at a 5.1% CAGR, below the other four countries, and home sales below 5 million units will push Japanese ECU suppliers toward export programs.
Key takeaway: Japanese suppliers will look abroad for ECU volume as home sales stay below 5 million units.
India Automotive ECU Market Outlook (2026 to 2036)
Truck and bus sales give India the second-fastest rate. SIAM figures for FY26 showed 10,79,871 commercial vehicles sold at wholesale, a 12.6% rise.[9] Each new truck carries engine, transmission and brake controllers, so fleet growth adds ECU volume. India grows at a 6% CAGR from 2026 to 2036.
Key takeaway: Wholesales of 10,79,871 commercial vehicles in FY26 give ECU suppliers a growing truck base in India.
Who are the notable companies in the automotive ECU market?
Robert Bosch GmbH, Denso Corporation, Continental AG, Transtron Inc., ZF Friedrichshafen AG, Hitachi Automotive Systems Ltd., Mitsubishi Electric Mobility Corporation, Syrma SGS, Panasonic Industry Co., Ltd. and MicroAutotech supply control units in this market.
Tier-1 status belongs to Bosch, Denso and Continental, a group FMI places at about 50 to 55% of the market. Transtron, MicroAutotech and the other second-tier suppliers hold about 45 to 50%. Bosch began sampling third-generation SiC chips to carmakers in April 2026, so Tier-1 suppliers are also selling the silicon inside ECUs.[5]
Chip launches and hybrid programs marked the supplier calendar in 2026. Bosch sent third-generation SiC chip samples to automakers in April 2026.[5] DENSO Manufacturing Tennessee produces the inverter for the new Jeep Cherokee hybrid module.[6]
- Tier-1 suppliers: Robert Bosch GmbH, Denso Corporation, and Continental AG.
- Tier-2 and other suppliers: Transtron Inc., MicroAutotech, ZF Friedrichshafen AG, Hitachi Automotive Systems Ltd., Mitsubishi Electric Mobility Corporation, Syrma SGS, and Panasonic Industry Co., Ltd.
Competitive Benchmarking: Automotive ECU Market
Table 10: Competitive Benchmarking for the Automotive ECU Market (qualitative documentation ratings), 2026
| Company | Controller Breadth | Chip Access | Electrification Programs | Dated Disclosure |
|---|---|---|---|---|
| Robert Bosch GmbH | High | High | High | High |
| Denso Corporation | High | Medium | High | High |
| Continental AG | High | Medium | Medium | Medium |
| ZF Friedrichshafen AG | Medium | Medium | Medium | Medium |
| Transtron Inc. | Low | Low | Low | Low |
Each company is scored High, Medium or Low against the dated filings and releases behind every column.
Key Developments in the Automotive ECU Market
- In August 2026, DENSO said a two-motor hybrid drive module developed with BluE Nexus and AISIN was adopted for the new Jeep Cherokee.[6]
- In August 2026, Infineon reported record Q3 FY2026 revenue of €4.172 billion.[4]
- In July 2026, NXP posted $1,938 million of Q2 automotive revenue.[1]
- In April 2026, Bosch started to introduce third-generation silicon carbide chips.[5]
- In April 2026, SIAM data showed Indian commercial vehicle wholesales up 12.6% in FY26.[9]
- In March 2026, the DOT reported work on a proposal to amend FMVSS 127.[7]
- In January 2026, MIIT announced GB 39901-2025, the first mandatory standard for AEB on light-duty vehicles in China.[3]
Key Players in the Automotive ECU Market
Tier-1 Suppliers
- Robert Bosch GmbH
- Denso Corporation
- Continental AG
Tier-2 and Other Suppliers
- Transtron Inc.
- MicroAutotech
- ZF Friedrichshafen AG
- Hitachi Automotive Systems Ltd.
- Mitsubishi Electric Mobility Corporation
- Syrma SGS
- Panasonic Industry Co., Ltd.
Automotive ECU Market - Report Scope
Table 11: Report Scope for the Automotive ECU Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Vehicle type; propulsion type; ECU capacity; application; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Automotive electronic control units of 16-bit, 32-bit and 64-bit capacity for ADAS and safety, body control and comfort, infotainment and communication, and powertrain systems, sold to OEMs and the aftermarket. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; India; USA; Germany; Japan |
| Key companies profiled | Robert Bosch GmbH, Denso Corporation, Continental AG, Transtron Inc., ZF Friedrichshafen AG, Hitachi Automotive Systems Ltd., Mitsubishi Electric Mobility Corporation, Syrma SGS, Panasonic Industry Co., Ltd., MicroAutotech |
| Forecast period | 2026 to 2036 |
Automotive ECU Market - Research Methodology
Table 12: Research Methodology for the Automotive ECU Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Chip maker results, supplier releases, safety rule notices, production statistics and trade press dated May 2025 or later. |
| Desk Research | Desk research covers semiconductor orders, AEB rules in China and the USA, electric car output and hybrid programs. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 69.0 billion and the 5.7% CAGR. |
| Data Validation | Chip order trends were set against vehicle production data for the same year. |
Automotive ECU Market by Segments
Automotive ECU Market segmented by Vehicle Type:
- Passenger Vehicle
- Heavy Commercial Vehicle
- Electric Vehicle
Automotive ECU Market segmented by Propulsion Type:
- Battery Powered
- Hybrid
- Internal Combustion Engine
Automotive ECU Market segmented by ECU Capacity:
- 16-bit
- 32-bit
- 64-bit
Automotive ECU Market segmented by Application:
- ADAS and Safety System
- Body Control and Comfort System
- Infotainment and Communication System
- Powertrain System
Automotive ECU Market segmented by Sales Channel:
- OEM
- Aftermarket
Automotive ECU Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] NXP Semiconductors N.V. (2026, July 28). NXP Semiconductors Reports Second Quarter 2026 Results. https://mfn.se/all/a/nxp-semiconductors/nxp-semiconductors-reports-second-quarter-2026-results-5d29ebc9
- [2] Gasgoo. (2026, January 15). China's auto sales reach 34.40 million in 2025, 2026 expected to edge up 1%. https://autonews.gasgoo.com/articles/market-industry/chinas-auto-sales-reach-3440-million-in-2025-2026-expected-to-edge-up-1-2011759388677484544
- [3] CnEVPost. (2026, January 28). China issues 1st mandatory standard for driver assist systems, mandating AEB as standard in light vehicles. https://cnevpost.com/2026/01/28/china-issues-1st-mandatory-standard-driver-assist-aeb-as-standard/
- [4] Infineon Technologies AG. (2026, August 5). Infineon Technologies AG Q3 FY 2026 concluded with record sales driven by strong AI business. https://www.placera.se/pressmeddelanden/infineon-technologies-infineon-technolgies-ag-q3-fy-2026-concluded-with-record-sales-driven-by-strong-ai-business-further-significant-increase-in-revenue-and-margin-expected-in-q4-fy-2026-20260805
- [5] Robert Bosch GmbH. (2026, April 22). A leap in semiconductor efficiency: Bosch introduces third generation of SiC chips. https://www.bosch-presse.de/pressportal/de/en/a-leap-in-semiconductor-efficiency-bosch-introduces-third-generation-of-sic-chips-282432.html
- [6] DENSO Corporation. (2026, August 27). Newly Developed Two-Motor Hybrid Drive Module Adopted for STELLANTIS New Jeep Cherokee. https://www.denso.com/global/en/newsroom/news/2026/20260827-g01
- [7] Nelson Mullins. (2026, April 22). The Road Ahead for FMVSS 127: Whither the Automatic Emergency Braking Mandate? https://www.nelsonmullins.com/insights/blogs/driving-forward-developments-in-transportation-law-and-innovation/all/the-road-ahead-for-fmvss-127-whither-the-automatic-emergency-braking-mandate
- [8] AUTOHAUS. (2026, February 5). Autoproduktion in Deutschland: Stromer boomen, Verbrenner bremsen. https://www.autohaus.de/nachrichten/autohersteller/autoproduktion-in-deutschland-stromer-boomen-verbrenner-bremsen-3765835
- [9] Outlook Business (PTI). (2026, April 14). Automobile wholesales in India clock record 2.83 crore units in FY26: SIAM. https://www.outlookbusiness.com/industry/automobile-wholesales-in-india-clock-record-283-crore-units-in-fy26-siam
- [10] Jiji Press (Adnkronos). (2026, January 5). Japan's New Auto Sales Up for 1st Time in 2 Yrs. https://english.adnkronos.com/2026/01/05/japans-new-auto-sales-up-for-1st-time-in-2-yrs/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will automotive ECU sales total in 2026 and 2036?
- What CAGR will ECU sales record from 2026 to 2036?
- Which vehicle type and propulsion type will hold the largest shares?
- Which ECU capacity will gain most from software-defined vehicles?
- Which countries will grow fastest?
- Which suppliers will shape ECU competition through 2036?
Frequently Asked Questions
What is the size of the automotive ECU market in 2026?
ECU sales are estimated at USD 72.9 billion in 2026, and a 5.7% CAGR will take market size to USD 127.0 billion by 2036, per FMI.
What will drive ECU sales through 2036?
China’s 2028 AEB rule, the US FMVSS 127 deadline and hybrid programs such as the Jeep Cherokee module will drive ECU sales. Battery-powered propulsion will post the quickest rate, a 6.3% CAGR.
Which vehicle type will hold the top share in 2026?
Passenger vehicles will hold 64% of vehicle type sales, with electric vehicles next at an estimated 21.3%.
Which ECU capacity will gain the most?
64-bit units, at about 31.5% (estimated), will gain as carmakers move ADAS and over-the-air functions onto central computers.
Which country will post the fastest ECU growth?
On FMI numbers, China will grow fastest with a 6.2% CAGR, ahead of India at 6%.
Who are the key ECU suppliers?
Bosch, Denso and Continental will form the Tier-1 group, and Transtron and MicroAutotech will compete in Tier-2.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Vehicle
- Heavy Commercial Vehicle
- Electric Vehicle
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Propulsion Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Propulsion Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Propulsion Type, 2026 to 2036
- Battery Powered
- Hybrid
- Internal Combustion Engine
- Y-o-Y Growth Trend Analysis By Propulsion Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Propulsion Type, 2026 to 2036
- Global Market Analysis and Forecast, By ECU Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By ECU Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By ECU Capacity, 2026 to 2036
- 16-bit
- 32-bit
- 64-bit
- Y-o-Y Growth Trend Analysis By ECU Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By ECU Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- ADAS and Safety System
- Body Control and Comfort System
- Infotainment and Communication System
- Powertrain System
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- China
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Vehicle Type
- By Propulsion Type
- By ECU Capacity
- By Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Robert Bosch GmbH
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Denso Corporation
- Continental AG
- ZF Friedrichshafen AG
- Transtron Inc.
- MicroAutotech
- Hitachi Automotive Systems Ltd.
- Mitsubishi Electric Mobility Corporation
- Syrma SGS
- Panasonic Industry Co., Ltd.
- Robert Bosch GmbH
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


