
- Market Size (2026)
- USD 18.5 Bn
- Forecast (2036)
- USD 39.2 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is Food Testing Services Market in 2026?
Sales in the food testing services market are projected to grow at 7.8% CAGR through 2036. Market valuation increases from USD 17.2 billion in 2025 to USD 18.5 billion in 2026 and is estimated to reach USD 39.2 billion by 2036.
Stringent contamination thresholds across commercial food plants, coupled with the need to reduce recall liabilities from undeclared allergens or microbial outbreaks, have propelled spending on outsourced food testing services. According to Future Market Insights analysis, the global market stands at USD 17.2 billion in 2025 and rises to USD 18.5 billion in 2026. Industry revenue is projected to reach USD 39.2 billion by 2036, expanding at a 7.8% CAGR from 2026 to 2036 and generating USD 20.7 billion in added revenue. Food manufacturers and retail grocery chains contract independent laboratories to test incoming raw ingredients and finished food batches when internal plant labs lack high-resolution instrumentation. In January 2026, United States Department of Agriculture Food Safety and Inspection Service recall summaries recorded that product contamination accounted for 48% of federal food recalls during calendar year 2025, while unreported allergens represented 24% [1]. Owing to this recall exposure, standard commercial testing captures 38.9% of service type revenue in 2026. Growth across profiled countries spans 6.2% CAGR in France to 9.5% in Canada, although skilled microbiologist shortages continue to restrain laboratory margin expansion.
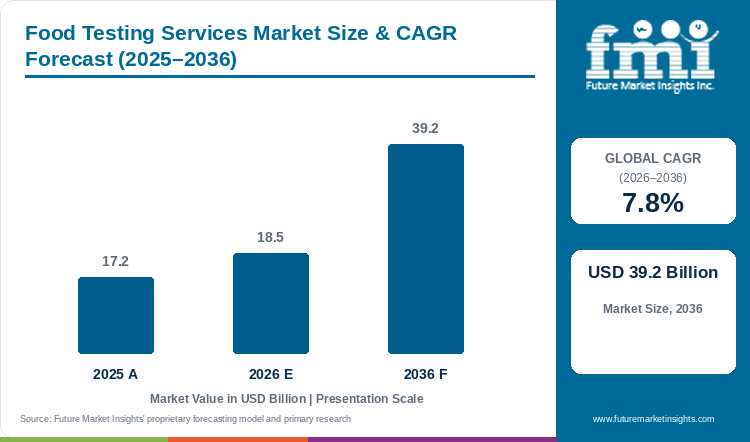
Key Market Trends & Insights
- By service type: Standard commercial testing led the market with a share of 38.9% in 2026, supported by mandatory batch release screening for bacterial pathogens and agricultural pesticide residues.
- By food matrix tested: Fresh / ambient packaged accounted for 45.3% of demand in 2026, owing to stringent border quarantine inspections for shelf-stable grain and packaged grocery shipments.
- By end-use application: Direct retail consumer protection represented 49.9% of revenue in 2026, as supermarket chains enforce private-label vendor audits and allergen label verification.
- By sales channel: With a 57.6% share in 2026, direct commercial laboratory contracts led the category, underpinned by multi-year enterprise testing agreements and automated sample tracking.
Regional Highlights
- Fastest-growing profiled country: Canada, at 9.5% CAGR from 2026 to 2036.
- By country: South Korea (8.7%), USA (8.1%), and Japan (7.5%) follow, while France records the lowest profiled CAGR at 6.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Food Testing Services Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 17.2 billion |
| Estimated Market Size in 2026 | USD 18.5 billion |
| Projected Market Size by 2036 | USD 39.2 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 20.7 billion |
Country demand conditions differ as domestic food import reliance and regulatory sampling schedules vary across national jurisdictions. Future Market Insights research indicates that food importers and export grain terminals face mounting pressure to prove chemical purity before customs clearance. In June 2026, the U.S. Food and Drug Administration updated Import Alert 23-14 compliance rules requiring accredited third-party mycotoxin testing documentation for designated imported food shipments prior to port admission [2]. As a result, contract laboratories are upgrading food safety testing workflows with automated liquid handling and tandem mass spectrometry, which separates routine compliance screening from specialized forensic adduct testing.
Laboratory Testing Sample Throughput and Instrumentation Sizing
Table 2: Laboratory Testing Sample Throughput and Instrumentation Sizing for the Food Testing Services Market (USD billion, million assays, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 17.2 | 18.5 | 39.2 |
| Commercial food samples tested (million assays) | 480.0 to 510.0 | 515.0 to 545.0 | 1,120.0 to 1,190.0 |
| Rapid automated molecular pathogen assay share (percent) | 32.5 to 34.0 | 34.0 to 35.8 | 48.0 to 51.5 |
| Average revenue realization per commercial assay (USD) | 34.5 to 36.8 | 34.8 to 37.2 | 33.5 to 36.0 |
Per Capita Food Safety Testing Compliance Indicators
Increasing requirement of mitigating contamination risks in ready-to-eat foods and removing manual transcription errors from plant quality checks drives enterprise spending per manufacturing site. Commercial laboratories integrate industrial microbiology swabbing programs with digital laboratory information management systems so quality teams can release production lots within a single shift. Furthermore, rising enforcement of whole-genome sequencing across meat and dairy plants continues to expand annual testing budgets per facility.
Table 3: Per Capita and Industrial Spending Indicators for the Food Testing Services Market (USD and billion people), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 2.09 | 2.23 | 4.38 |
| Spend per 1,000 people (USD) | 2,090.0 | 2,228.9 | 4,379.9 |
| Commercial food processing plant annual testing spend (USD thousand) | 140.0 to 155.0 | 150.0 to 166.0 | 315.0 to 345.0 |
Table 4: Facility & Industrial Channel Sizing Indicators for the Food Testing Services Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 18.5 billion | 2026 market estimate |
| Licensed commercial food manufacturing facilities worldwide | 122.5 thousand | 2024 industrial registry |
| Average annual food testing spend per manufacturing facility | USD 151.0 thousand | Facility spending benchmark |
| Direct retail consumer protection testing revenue, 2026 | USD 9.2 billion | 49.9% application share |
Analyst Perspective
"Rapid PCR and tandem mass spectrometry allow contract laboratories to cut pathogen and residue turnaround times for perishable food batches. Complex food matrices still require extensive method validation before processors approve automated routine screening."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Food Testing Services Market segmented?
The food testing services market is segmented by service type, testing technology, food matrix tested, end-use application, sales channel, and region.
By service type: Standard commercial testing (pathogen and residue), food authenticity and adulteration screening, nutritional labeling analysis, and shelf-life and stability testing.
By testing technology: Polymerase chain reaction (PCR), liquid chromatography-mass spectrometry (LC-MS/MS), enzyme-linked immunosorbent assay (ELISA), and classical culture microbiology.
By food matrix tested: Fresh / ambient packaged, meat and poultry, dairy products, processed fruits and vegetables, and beverages.
By end-use application: Direct retail consumer protection, commercial food manufacturing plants, and foodservice and hospitality.
By sales channel: Direct commercial laboratory contracts, government and municipal regulatory testing, and third-party quality auditor referrals.
Why does Standard Commercial Testing lead the service type category?
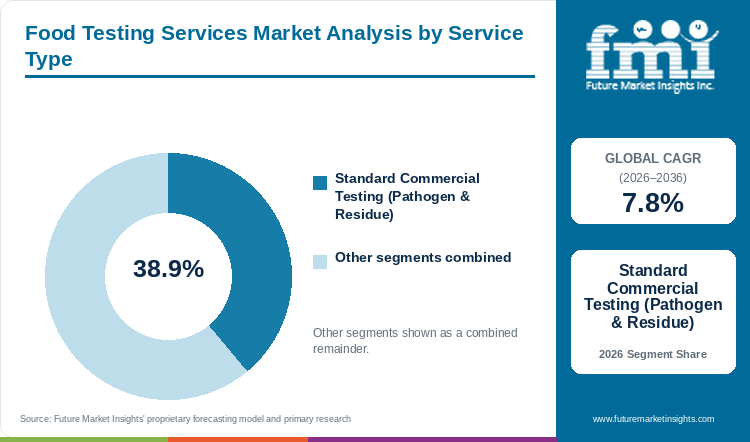
Standard commercial testing is expected to hold 38.9% of service type revenue in 2026, supported by mandatory pathogen release screening.
Table 5: Service Type Share for the Food Testing Services Market (percentage share), 2026
| Service Type | Share (2026) |
|---|---|
| Standard Commercial Testing | 38.9% |
| Other Segments Combined | 61.1%* |
| Total | 100.0% |
Table 6: Service Type Leadership and Market Growth for the Food Testing Services Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | Standard Commercial Testing |
Food plant quality managers prioritize standard commercial testing panels because food safety regulators require documented negative pathogen and residue certificates before commercial lots enter retail distribution. Unlike discretionary shelf-life trials or ad-hoc adulteration checks, pathogen and multi-residue pesticide screens must be executed on every production shift to satisfy food certification programs. In addition to this, contract laboratories use multiplexed PCR assays that cut enrichment and confirmation cycles from five days down to under twenty-four hours. That speed reduces cold-storage holding costs for meat and dairy plants, although high-fat matrices still require extraction cleanup before amplification.
- Standard commercial testing is expected to account for 38.9% of service type revenue in 2026, supported by mandatory batch release testing across food plants.
- In March 2025, International Organization for Standardization ISO 16140-3 verification protocols established standardized single-laboratory method verification rules for rapid food microbiology assays [3].
What makes Fresh / Ambient Packaged central to the food matrix tested category?
Fresh and ambient packaged goods are projected to capture 45.3% of food matrix tested volume in 2026, driven by customs inspections.
Ambient packaged foods and fresh produce shipments generate the largest sample volume because international grain traders and grocery importers must clear border quarantine checks across multiple jurisdictions. Container loads of spices and cereal flours as well as packaged snacks are routinely sampled for aflatoxins and agricultural chemical residues before port release. Besides this, grain processors pair laboratory chromatography testing with feed mycotoxin binders when raw harvest lots show elevated fungal contamination during humid storage seasons. Because a single rejected container results in demurrage penalties and buyer delisting, exporters submit duplicate composite samples prior to vessel loading.
- Fresh and ambient packaged samples are projected to hold 45.3% of food matrix tested demand in 2026, driven by cross-border shipment volume and port customs audits.
- In May 2026, the Joint FAO/WHO Meeting on Pesticide Residues published its 2025 evaluation report establishing updated maximum residue limits and toxicological thresholds for international food trade [4].
What keeps Direct Retail Consumer Protection ahead by end-use application?
Direct retail consumer protection is estimated to represent 49.9% of end-use application revenue in 2026, reflecting strict supermarket audits.
Supermarket chains and consumer brand owners account for nearly half of testing expenditure because retail labels carry direct legal and financial exposure when a contaminated product reaches grocery shoppers. Private-label grocery buyers require co-packers to submit third-party certificates of analysis covering undeclared milk and peanut proteins as well as gluten before warehouse intake. Owing to the advantages associated with rapid ELISA and PCR workflows, food allergen testing has become a standard line-changeover verification step in shared bakery and snack plants. However, cross-reactivity in fermented or hydrolyzed ingredients still forces laboratories to run confirmatory mass spectrometry before issuing final clearance.
- Direct retail consumer protection is estimated to represent 49.9% of end-use application revenue in 2026, reflecting mandatory supermarket supplier verification rules.
- In May 2026, the European Food Safety Authority released its latest European Union pesticide residue monitoring report covering more than 125,000 food samples analyzed across member states [5].
How do Direct Commercial Laboratory Contracts anchor the sales channel category?
Direct commercial laboratory contracts are anticipated to contribute 57.6% of sales channel revenue in 2026, underpinned by annual volume agreements.
Multi-plant food manufacturers prefer direct annual service agreements with accredited commercial laboratory networks rather than routing samples through third-party brokers. Direct contracting integrates the food processor's enterprise quality software directly with the laboratory's LIMS portal, automating sample barcoding and out-of-specification alerts. Furthermore, large testing networks deploy allergen screening instruments and refrigerated courier routes near major agricultural processing corridors to guarantee same-day sample pickup. Smaller regional food makers still rely on ad-hoc testing, but enterprise processors lock in multi-year contracts to secure volume pricing and priority rush capacity.
- Direct commercial laboratory contracts are anticipated to hold 57.6% of sales channel revenue in 2026, underpinned by integrated LIMS reporting and dedicated courier logistics.
- In October 2026, Eurofins Scientific completed the acquisition of Element Materials Technology's North American Life Sciences testing business, adding 27 food and bioanalytical laboratory sites [6].
What are the drivers, restraints, and opportunities in the Food Testing Services Market?
In the Food Testing Services Market, preventive food safety enforcement and recall liability will continue to support demand, high analytical instrumentation costs will constrain laboratory margins, and genomic authenticity testing is expected to expand commercial service scope through 2036.
- Driver:Enactment of strict preventive food safety rules and rising corporate recall expenses will continue to compel routine batch testing across food plants through 2036.
- Restraint:High capital expenditure for tandem mass spectrometers and complex matrix validation workflows will continue to pressure turnaround times and laboratory margins through 2036.
- Opportunity:Commercializing next-generation genomic sequencing and digital chain-of-custody verification is expected to unlock higher-margin authenticity contracts through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Stricter federal preventive control mandates and zero-tolerance retail audit policies are forcing food processors to test environmental swabs and finished product lots at higher frequencies. Rather than waiting for end-product failures, quality assurance teams now monitor processing lines continuously and link laboratory test results to mock recall management platforms so contaminated lots are isolated before shipment. FMI data suggests that outsourcing microbiology and residue panels costs less for mid-sized food plants than maintaining internal ISO 17025 accreditation. In June 2026, the World Health Organization updated its global food safety assessment, highlighting that unsafe food containing harmful bacteria or chemical substances causes more than 200 diseases worldwide [7]. Suppliers must deliver verified certificates of analysis before supermarket distribution centers accept delivery.
Risk Assessment of the Food Testing Services Market: Operational and Formulation Friction
High equipment acquisition costs and matrix interference during sample extraction remain the primary operational hurdles slowing laboratory expansion. Outfitting a commercial chromatography suite with liquid chromatography-tandem mass spectrometry and inductively coupled plasma mass spectrometry requires substantial capital investment alongside specialized analytical chemists. In addition to this, spices and high-fat sauces contain natural polyphenols and lipids that inhibit PCR enzymes or foul chromatography columns. In January 2026, the U.S. Food and Drug Administration updated its food facility registration and compliance framework, reinforcing strict verification standards for facilities handling commercial food shipments [8]. While rapid point-of-care sensitivity testing strips offer quick plant-floor checks, processors still face extended validation delays when certifying complex composite meals.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Growing buyer scrutiny over species substitution and geographic origin fraud is creating strong commercial demand for molecular authenticity services. High-value olive oils and premium seafood along with manuka honey are frequent targets of economic adulteration across multi-tier supply chains. Contract laboratories that combine next-generation DNA barcoding and isotope ratio mass spectrometry with food traceability systems allow food brands to substantiate organic and single-origin label claims. In September 2025, Mérieux NutriSciences completed its global acquisition of Bureau Veritas's food testing activities across 15 countries, integrating 34 laboratories and 1,900 technical staff into its global testing network [9]. Testing providers that pair genomic speciation with digital compliance portals are well positioned to secure multi-year retail audit contracts.
Food Testing Services Market by Country (2026 to 2036)
As per FMI, Canada represents the fastest-growing food testing services market among the six profiled countries at a 9.5% CAGR from 2026 to 2036, while France records a 6.2% CAGR. Across all six covered markets, commercial laboratory growth is shaped by national import inspection frequencies and export certification rules, along with how rapidly food plants outsource routine microbiology and residue panels.
Table 7: Country CAGR and Primary Growth Levers for the Food Testing Services Market (CAGR percentage and operational drivers), 2026 to 2036
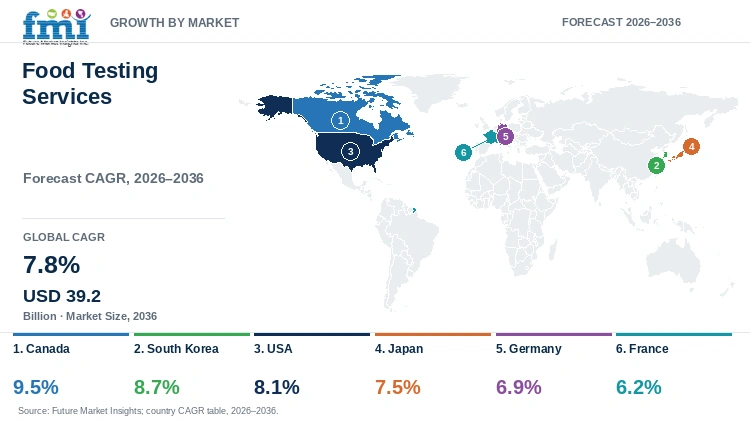
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Canada | 9.5% | Safe Food for Canadians Regulations preventive control audits and export grain and meat certification |
| South Korea | 8.7% | Imported food border residue screening and convenience store ready-to-eat meal microbiology mandates |
| USA | 8.1% | FSMA preventive control environmental swabbing and multi-allergen verification across retail grocery brands |
| Japan | 7.5% | Positive List System multi-residue agricultural chemical screening and imported seafood inspection |
| Germany | 6.9% | European Union maximum residue limit compliance and private-label organic supermarket sampling |
| France | 6.2% | Protected-origin dairy and wine authenticity verification alongside raw-milk pathogen screening |
Source: Future Market Insights analysis
Canada Food Testing Services Market Outlook (2026 to 2036)
Export-oriented agricultural processing and strict federal preventive control enforcement make Canada the fastest-expanding market among the profiled countries at a 9.5% CAGR from 2026 to 2036. Under the Safe Food for Canadians Regulations, meat packers and prairie grain exporters must maintain written preventive control plans backed by accredited third-party laboratory results. In June 2026, the Canadian Food Inspection Agency published its national food safety testing review confirming high compliance rates across thousands of domestic and imported food samples screened for chemical residues and bacterial pathogens [10]. However, vast transport distances between western agricultural plants and urban laboratory hubs can delay courier transit for chilled swabs. Contract laboratories are addressing this bottleneck by opening regional microbiology satellite labs across Alberta and Ontario as well as Saskatchewan.
Key takeaway:In Canada, federal preventive control verification and export grain and beef certification requirements sustain the highest country growth rate for commercial food testing laboratories.
South Korea Food Testing Services Market Outlook (2026 to 2036)
Heavy reliance on imported agricultural commodities and rapid expansion of chilled convenience store ready-meals are projected to drive South Korea's food testing services market at an 8.7% CAGR through 2036. Because domestic food processors import the majority of their wheat and soybeans along with frozen seafood, port laboratories in Incheon and Busan run continuous chromatography and heavy-metal assays prior to customs clearance. In July 2026, the Ministry of Food and Drug Safety updated its official registry of MFDS-Designated Foreign Testing Laboratories authorized to issue pre-import inspection certificates for food shipments entering South Korea [11]. At the same time, short shelf-life windows for convenience store bento meals leave little room for slow culture plating. Domestic testing providers are adopting rapid PCR pathogen kits to deliver same-day clearance for chilled food factories.
Key takeaway:In South Korea, strict border screening of imported food raw materials and daily hygiene testing for convenience ready-meals anchor commercial laboratory demand.
USA Food Testing Services Market Outlook (2026 to 2036)
In the United States, demand for food testing services is predicted to advance at an 8.1% CAGR between 2026 and 2036 as federal environmental monitoring rules and class-action recall litigation push food brands toward continuous verification. Under Food Safety Modernization Act preventive controls, ready-to-eat food plants must swab processing surfaces regularly for Listeria and Salmonella and verify allergen sanitation between production runs. In August 2026, the USDA Food Safety and Inspection Service issued updated public health alerts and recall summaries under its ready-to-eat meat and poultry pathogen testing program [12]. Even so, high turnover among bench technicians in commercial laboratories creates staffing pressure during peak harvest and holiday production months. Leading U.S. laboratory networks are installing robotic sample accessioning and automated PCR platforms to stabilize turnaround times.
Key takeaway:In the USA, federal environmental pathogen swabbing mandates and corporate allergen recall prevention underpin large-scale enterprise testing contracts.
Japan Food Testing Services Market Outlook (2026 to 2036)
Japanese food importers and retail buyers enforce some of the most detailed chemical residue specifications globally, supporting a projected 7.5% CAGR for Japan's food testing services sector through 2036. Under Japan's Positive List System, agricultural products and processed foods cannot exceed a uniform 0.01 parts-per-million default threshold for unapproved agricultural chemicals. In 2025, Japan's Ministry of Health, Labour and Welfare expanded its Imported Food Monitoring and Guidance Plan, digitizing import notification workflows and maintaining intensive quarantine inspection across port testing centers [13]. Because testing a single food shipment across hundreds of pesticide analytes requires high-sensitivity LC-MS/MS and GC-MS/MS runs, smaller in-house factory labs cannot justify the equipment cost. Japanese food companies consequently outsource multi-residue screening to accredited commercial laboratories in Tokyo and Osaka as well as Yokohama.
Key takeaway:In Japan, strict Positive List pesticide thresholds and intensive quarantine port monitoring sustain recurring demand for multi-residue chromatography testing.
Germany Food Testing Services Market Outlook (2026 to 2036)
Germany's food testing services sector is forecast to expand at a 6.9% CAGR from 2026 to 2036, shaped by strict European Union contaminant regulations and aggressive private-label quality policing by German discount and supermarket chains. German food retailers routinely require suppliers to satisfy residue limits that are stricter than statutory European maximum residue levels, while also demanding verification against mineral oil hydrocarbons and perfluoroalkyl substances. In September 2025, Germany's Federal Statistical Office and federal food safety monitoring releases documented sustained inspection intensity across commercial organic and conventional food processing enterprises [14]. However, price competition among European contract laboratories squeezes per-sample fees on basic hygiene tests. German laboratories protect operating margins by specializing in trace contaminant chromatography and organic authenticity verification.
Key takeaway:In Germany, strict retailer residue specifications and widespread organic food verification drive commercial laboratory spending on trace contaminant testing.
France Food Testing Services Market Outlook (2026 to 2036)
Protecting geographical indication authenticity and preventing bacterial contamination in raw-milk dairy and charcuterie products underpin France's projected 6.2% CAGR through 2036. French dairy cooperatives and specialty food makers must comply with national hygiene audits while defending protected appellation labels against lower-cost adulteration. In December 2025, France's Directorate-General for Competition, Consumer Affairs and Fraud Control published updated food fraud and sanitary inspection findings targeting origin misrepresentation and microbiological safety across domestic grocery supply chains [15]. Testing delicate raw-milk cheeses presents a specific technical challenge because background lactic flora can mask target pathogens in standard culture media. Commercial laboratories in France win dairy contracts by deploying validated phage-based and droplet digital PCR assays that distinguish pathogenic Shiga toxin-producing E. coli and Listeria within twenty-four hours.
Key takeaway:In France, appellation origin verification and rapid pathogen screening across raw-milk dairy and meat processors support steady contract laboratory demand.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Food Testing Services Market?
Eurofins Scientific, SGS S.A., Intertek Group plc, Bureau Veritas, ALS Limited, Mérieux NutriSciences, TÜV SÜD, and AsureQuality Limited are the notable companies in the food testing services market.
In the FMI report, competition across the food testing services sector is divided between global testing and certification groups and specialized food science laboratory networks. Eurofins Scientific, SGS S.A., and Intertek Group plc operate hub-and-spoke microbiology and analytical chemistry laboratories across major trade ports and agricultural regions. Mérieux NutriSciences and ALS Limited focus heavily on specialized pathogen genomics and ultra-trace contaminant chromatography. TÜV SÜD and AsureQuality Limited combine laboratory testing with factory hygiene auditing and export dairy certification. Food processors evaluate testing partners on ISO 17025 accreditation scope and LIMS integration alongside courier pickup cutoffs.
- Global High-Throughput TIC Networks: Eurofins Scientific, SGS S.A., Intertek Group plc, and Bureau Veritas operate international hub-and-spoke testing laboratories and supply chain audit programs.
- Specialized Food Science and Bioanalytical Platforms: Mérieux NutriSciences and ALS Limited provide dedicated food microbiology, allergen validation, and ultra-trace residue chromatography.
- Export Certification and Process Assurance Specialists: TÜV SÜD and AsureQuality Limited combine accredited laboratory testing with agricultural traceability and food safety system certification.
Competitive Benchmarking: Food Testing Services Market
Table 8: Competitive Benchmarking for the Food Testing Services Market (qualitative capability ratings), 2026
| Company | Microbiology & Pathogen Breadth | Chromatography & Residue Depth | Enterprise LIMS & Audit Access | Geographic Reach |
|---|---|---|---|---|
| Eurofins Scientific | High | High | High | High |
| SGS S.A. | High | High | High | High |
| Intertek Group plc | Medium | High | High | High |
| Bureau Veritas | Medium | Medium | High | High |
| ALS Limited | Medium | High | Medium | Medium |
| Mérieux NutriSciences | High | High | High | High |
| TÜV SÜD | Medium | Medium | High | Medium |
| AsureQuality Limited | High | Medium | Medium | Medium |
Key Developments in the Food Testing Services Market
- In October 2026, Eurofins Scientific completed the acquisition of Element Materials Technology’s Life Sciences Testing Services business in North America for USD 400 million, adding 27 laboratories across the United States and Canada and expanding its food testing, environmental testing, and biopharmaceutical product testing capacity across the region [16].
- In February 2026, SGS S.A. acquired Murray-Brown Laboratories in Denver, Colorado, expanding its accredited food safety, microbiology, and nutraceutical testing capabilities across North America through the addition of advanced PCR-based pathogen detection and analytical chemistry services [17].
- In January 2025, Mérieux NutriSciences completed the acquisition of Bureau Veritas’ food testing activities in the United States and Canada, integrating 12 accredited laboratories and approximately 400 employees across the region as the first phase of a global transaction valued at EUR 360 million [18].
Key Players in the Food Testing Services Market
Global High-Throughput TIC Networks
- Eurofins Scientific
- SGS S.A.
- Intertek Group plc
- Bureau Veritas
Specialized Food Science and Bioanalytical Platforms
- Mérieux NutriSciences
- ALS Limited
Export Certification and Process Assurance Specialists
- TÜV SÜD
- AsureQuality Limited
Food Testing Services Market - Report Scope
Table 9: Report Scope for the Food Testing Services Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Service Type; Testing Technology; Food Matrix Tested; End-Use Application; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial contract laboratory revenue from microbiological, chemical residue, allergen, nutritional, shelf-life, and authenticity testing of food and agricultural matrices. Excludes sales of standalone diagnostic hardware, reagents, and internal non-commercial factory quality checks. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Canada, South Korea, USA, Japan, Germany, France, and additional countries in the full report |
| Key Companies Covered | Eurofins Scientific, SGS S.A., Intertek Group plc, Bureau Veritas, ALS Limited, Mérieux NutriSciences, TÜV SÜD, AsureQuality Limited |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Food Testing Services Market - Research Methodology
Table 10: Research Methodology for the Food Testing Services Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with laboratory directors, food processing quality assurance managers, regulatory auditors, analytical chemists, and procurement teams across the value chain to validate testing frequencies, turnaround requirements, and pricing trends. |
| Secondary Research | Secondary research included federal food recall databases, border import refusal logs, ISO 17025 accreditation registries, company annual reports, investor presentations, technical standards, and publicly available regulatory publications. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up approaches assessing commercial assay volumes, average realization per test panel, and outsourcing penetration across food categories. |
| Data Triangulation and Validation | Estimates were cross-checked against commercial food manufacturing output, import inspection volumes, and reported testing division revenues to ensure accuracy without double counting diagnostic equipment sales. |
Food Testing Services Market by Segments
Food Testing Services Market segmented by Service Type:
- Standard Commercial Testing (Pathogen & Residue)
- Food Authenticity & Adulteration Screening
- Nutritional Labeling Analysis
- Shelf-Life & Stability Testing
Food Testing Services Market segmented by Testing Technology:
- Polymerase Chain Reaction (PCR)
- Liquid Chromatography-Mass Spectrometry (LC-MS/MS)
- Enzyme-Linked Immunosorbent Assay (ELISA)
- Classical Culture Microbiology
Food Testing Services Market segmented by Food Matrix Tested:
- Fresh / Ambient Packaged
- Meat & Poultry
- Dairy Products
- Processed Fruits & Vegetables
- Beverages
Food Testing Services Market segmented by End-Use Application:
- Direct Retail Consumer Protection
- Commercial Food Manufacturing Plants
- Foodservice & Hospitality
Food Testing Services Market segmented by Sales Channel:
- Direct Commercial Laboratory Contracts
- Government & Municipal Regulatory Testing
- Third-Party Quality Auditor Referrals
Food Testing Services Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Food Safety and Inspection Service. (2026, January 15). Summary of recall and public health alert cases in calendar year 2025. U.S. Department of Agriculture Food Safety and Inspection Service.
- [2] U.S. Food and Drug Administration. (2026, June 22). Import Alert 23-14: Detention without physical examination of food products due to mycotoxins and third-party testing requirements. FDA Import Alert Compliance Registry.
- [3] International Organization for Standardization. (2025, March 18). ISO 16140-3: Microbiology of the food chain: Protocol for the verification of reference and alternative methods in a single laboratory. ISO Standards Publication.
- [4] World Health Organization & Food and Agriculture Organization. (2026, May 29). Pesticide residues in food: 2025 report of the Joint FAO/WHO Meeting on Pesticide Residues (JMPR). World Health Organization Technical Series.
- [5] European Food Safety Authority. (2026, May 5). European Union report on pesticide residues in food: Latest analytical monitoring data across member states. EFSA Scientific Publications.
- [6] Eurofins Scientific. (2026, October 2). Eurofins completes the acquisition of Element Materials Technology's Life Sciences and food testing services business in North America. Eurofins Scientific Press Releases.
- [7] World Health Organization. (2026, June 4). Food safety: Global burden of foodborne diseases and chemical contamination surveillance. WHO Fact Sheets and Technical Updates.
- [8] U.S. Food and Drug Administration. (2026, January 12). Registration of food facilities and preventive controls compliance requirements. U.S. Department of Health and Human Services FDA Guidance.
- [9] January 2025: Mérieux NutriSciences completed the first phase of its acquisition of Bureau Veritas’ food testing business, integrating Bureau Veritas’ food testing activities in the United States and Canada, comprising 12 laboratories and approximately 400 employees, as part of a broader global agreement valued at EUR 360 million covering 34 laboratories and 1,900 staff across 15 countries.
- [10] Canadian Food Inspection Agency. (2026, June 5). Canadian Food Inspection Agency testing shows strong food safety compliance across domestic and imported foods. Government of Canada CFIA Reports.
- [11] Ministry of Food and Drug Safety. (2026, July 30). Updated registry of MFDS-designated foreign testing laboratories and imported food inspection standards. Republic of Korea MFDS Regulatory Notices.
- [12] Food Safety and Inspection Service. (2026, August 8). Microbiological testing program for ready-to-eat meat and poultry products and public health alert updates. U.S. Department of Agriculture FSIS Directives.
- [13] Ministry of Health, Labour and Welfare. (2025, November 18). Imported food safety monitoring and guidance plan under the Positive List System. Government of Japan MHLW Food Safety Division.
- [14] Federal Statistical Office (Destatis). (2025, September 14). Quality assurance and residue control monitoring across German food processing enterprises. Statistisches Bundesamt Sectoral Reports.
- [15] Directorate-General for Competition, Consumer Affairs and Fraud Control (DGCCRF). (2025, December 10). Annual surveillance report on food authenticity and microbiological safety in France. Ministry of the Economy and Finance Publications.
- [16] Eurofins Scientific Canada. (2026, June 5). Eurofins announces the acquisition of High North Laboratories to expand Canadian analytical food testing. Eurofins Canada Corporate Announcements.
- [17] SGS S.A. (2026, March 22). SGS acquires Murray-Brown Laboratories, expanding food safety and nutraceutical testing in North America. SGS Corporate Communications.
- [18] Intertek Group plc. (2025, January 16). Intertek Assuris Food & Nutrition Group regulatory affairs and meat safety assurance update. Intertek Industry Releases.
- [19] AsureQuality Limited. (2025, March 24). Auditing and inspection accreditations under MPI Risk-Based Measures and the Food Act. AsureQuality Corporate Disclosures.
- [20] ALS Limited. (2025, September 18). Expansion of ultra-trace LC-MS/MS and PFAS contaminant testing capabilities across food laboratories. ALS Limited Technical Releases.
- [21] TÜV SÜD. (2025, November 12). Food safety management system certification and accredited product testing integration. TÜV SÜD Division Reports.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the food testing services market in 2026 and what is forecast for 2036?
- Which regulatory frameworks and preventive food safety rules support demand for testing services?
- Why does standard commercial testing lead the service type category?
- Why does fresh and ambient packaged lead the food matrix tested category globally?
- How do growth rates differ across Canada, South Korea, the USA, and Japan?
- Which leading contract laboratories supply relevant pathogen and residue testing today?
- What limits adoption or laboratory sample throughput in the food testing services market?
- What should commercial food processing quality directors evaluate before contracting a third-party testing laboratory?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Service Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Type, 2026 to 2036
- Standard Commercial Testing (Pathogen & Residue)
- Food Authenticity & Adulteration Screening
- Nutritional Labeling Analysis
- Shelf-Life & Stability Testing
- Y-o-Y Growth Trend Analysis By Service Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Type, 2026 to 2036
- Global Market Analysis and Forecast, By Testing Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Testing Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Testing Technology, 2026 to 2036
- Polymerase Chain Reaction (PCR)
- Liquid Chromatography-Mass Spectrometry (LC-MS/MS)
- Enzyme-Linked Immunosorbent Assay (ELISA)
- Classical Culture Microbiology
- Y-o-Y Growth Trend Analysis By Testing Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Testing Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Food Matrix Tested, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Food Matrix Tested, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Food Matrix Tested, 2026 to 2036
- Fresh / Ambient Packaged
- Meat & Poultry
- Dairy Products
- Processed Fruits & Vegetables
- Beverages
- Y-o-Y Growth Trend Analysis By Food Matrix Tested, 2021 to 2025
- Absolute $ Opportunity Analysis By Food Matrix Tested, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Protection
- Commercial Food Manufacturing Plants
- Foodservice & Hospitality
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct Commercial Laboratory Contracts
- Government & Municipal Regulatory Testing
- Third-Party Quality Auditor Referrals
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Service Type
- By Testing Technology
- By Food Matrix Tested
- By End-Use Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Eurofins Scientific
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SGS S.A.
- Intertek Group plc
- Bureau Veritas
- ALS Limited
- Mérieux NutriSciences
- TÜV SÜD
- AsureQuality Limited
- Eurofins Scientific
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Service Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Testing Technology, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Food Matrix Tested, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Service Type
- Figure 6: Global Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Testing Technology
- Figure 9: Global Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Food Matrix Tested
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Application
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Service Type
- Figure 32: North America Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Testing Technology
- Figure 35: North America Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Food Matrix Tested
- Figure 38: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-Use Application
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Service Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Testing Technology
- Figure 51: Latin America Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Food Matrix Tested
- Figure 54: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Service Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Testing Technology
- Figure 67: Western Europe Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Food Matrix Tested
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Service Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Testing Technology
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Food Matrix Tested
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Service Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Testing Technology
- Figure 99: East Asia Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Food Matrix Tested
- Figure 102: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Service Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Testing Technology
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Food Matrix Tested
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Service Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Service Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Service Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Testing Technology, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Testing Technology, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Testing Technology
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Food Matrix Tested, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Food Matrix Tested, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Food Matrix Tested
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Food Testing Services Market in 2026, and what is forecast for 2036?
The global food testing services market is estimated to reach USD 18.5 billion in 2026. Revenue is projected to expand further and reach USD 39.2 billion by 2036 as food processors outsource pathogen and residue verification.
What is the CAGR for the Food Testing Services Market from 2026 to 2036?
As per FMI, the food testing services market is projected to grow at a 7.8% CAGR from 2026 to 2036. Expansion is supported by stricter federal preventive control rules and border quarantine screening.
Which service type segment leads the Food Testing Services Market?
Standard commercial testing is projected to hold 38.9% of service type demand in 2026. The segment leads because routine batch release screening for bacterial pathogens and pesticide residues is mandatory before retail shipment.
Which food matrix segment leads the Food Testing Services Market?
Fresh and ambient packaged goods are estimated to account for 45.3% of food matrix tested volume in 2026. Demand is underpinned by high cross-border trade volumes of grains, spices, and shelf-stable groceries.
Which country has a notable growth outlook during the assessment period?
FMI finds that Canada is projected to expand at a 9.5% CAGR during the 2026 to 2036 assessment period. Growth is supported by Safe Food for Canadians Regulations enforcement and export certification for grain and meat shipments.
Who are the key players in the market?
Notable companies active in the market include Eurofins Scientific, SGS S.A., Intertek Group plc, Bureau Veritas, ALS Limited, Mérieux NutriSciences, TÜV SÜD, and AsureQuality Limited. These providers focus on ISO 17025 laboratory automation, rapid PCR turnaround, and multi-residue chromatography.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
