

- Market Size (2026)
- USD 5.8 Bn
- Forecast (2036)
- USD 13.5 Bn
- CAGR (2026 to 2036)
- 8.8%
How big is Industrial Chiller Market in 2026?
The global industrial chiller market is estimated at USD 5.3 billion in 2025 and is expected to reach USD 5.8 billion in 2026. Sales of industrial chillers are projected to reach USD 13.5 billion by 2036, growing at a CAGR of 8.8% between 2026 and 2036. Screw chillers are expected to hold the largest share, at 29.5% of 2026 product type sales, according to FMI analysis.
FMI analysis points to data centre operators as the main source of new chiller demand. Demand for industrial chillers rises with each new server hall, since every hall needs a large chilled-water plant. For instance, Johnson Controls reported fourth quarter fiscal 2026 orders up 44% organically, with Americas orders up 58% on sustained demand for data centers [1]. Sales of chiller plants are also backed by a large volume of orders already placed. The Johnson Controls order backlog, for example, reached USD 23.0 billion at the end of fiscal 2026, up 43% organically [1]. Adoption of in-house component supply is spreading among large makers that need to ship faster, as Trane Technologies agreed on October 21, 2026 to acquire Cancoil, an Ontario heat-transfer maker that already supplies Trane chiller lines [2]. Consequently, chiller makers that own coil supply can shorten lead times and meet tight data centre schedules.
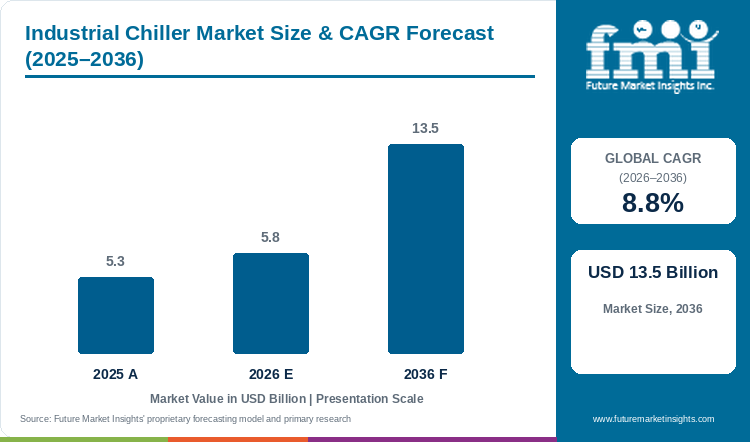
Table 1: Industrial Chiller Market Size and Forecast (USD billion), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 5.3 billion |
| Estimated market size in 2026 | USD 5.8 billion |
| Projected market size by 2036 | USD 13.5 billion |
| CAGR (2026 to 2036) | 8.8% |
| Added sales, 2026 to 2036 | USD 7.7 billion |
Key Market Trends & Insights
- By product type: Screw chillers will hold 29.5% of 2026 sales, since mid-to-large plants value the efficiency and part-load control of screw compressors.
- By end user: Food and beverage plants are expected to account for 31% of 2026 demand, as chilling, fermentation and cold storage run around the clock.
- By region: North America is likely to lead with 27.4% of 2026 sales, driven by hyperscale data centre construction and reshored manufacturing.
Regional Highlights
- Fastest-growing country: India is expected to grow fastest, at a CAGR of 10.6% between 2026 and 2036, as food processing, pharmaceutical and data centre capacity expand together.
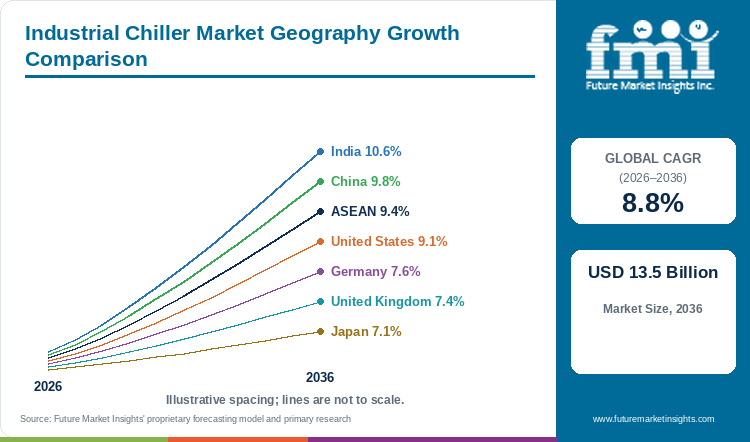
- Growth across other countries: China is set to grow at 9.8% as electronics and battery plants expand, and ASEAN at 9.4% as new data centres are built in a hot climate. Growth in the United States is put at 9.1%, supported by large hyperscale data centre campuses. European markets grow more slowly, as most demand comes from replacing older units, with Germany at 7.6% and the United Kingdom at 7.4%. Japan has the lowest rate at 7.1%, as most plants already have chillers installed.
Growth of the industrial chiller market is pushing makers to expand factories to keep up with a large volume of orders. Daikin Applied expanded the Phoenix Modular Solutions facility from 58,000 to 191,000 square feet, raising production capacity by about 150% [3]. Factory-built cooling modules cut site work, which suits data centres on tight build schedules. In Europe, Daikin inaugurated a heat pump production site in the Łódź region of Poland, an investment of about EUR 300 million [4]. Consequently, regional plants reduce shipping times for large thermal equipment, which supports chiller and heat pump supply in European projects.
Data centres generate the strongest orders for large chillers, and leading suppliers report rising volumes. Johnson Controls reported fourth quarter fiscal 2026 sales of USD 7.1 billion, up 12% organically [1]. The company guided organic sales growth of 11% to 12% for fiscal 2027, pointing to continued strength in building cooling. At the same time, suppliers are buying component makers to secure parts. Trane Technologies said Cancoil has more than 450 employees and plants in Ontario and Jacksonville, Texas [2]. Owning component suppliers protects chiller output, which matters more as order backlogs grow longer.
New power and refrigerant technology is reshaping chiller design. Trane Technologies demonstrated an 800-volt direct current chiller of more than 1,000 tons, or 3.5 MW, in September 2026 [5]. Direct current operation could raise system efficiency by up to 2%, which frees power for computing in AI data centres. Meanwhile, refrigerant rules continue to tighten in the United States. EPA states that manufacturers and importers of certain products have had to comply with HFC restrictions since January 1, 2025 [6]. As a result, chiller makers are moving to refrigerants with low global warming potential (low-GWP), which raises replacement demand for older units.
Table 2: Supporting Industry Indicators for the Industrial Chiller Market, 2025 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Supplier orders | Johnson Controls fourth quarter fiscal 2026 orders up 44% organically. | Orders signal future chiller installations. | [1] |
| Supplier backlog | Johnson Controls backlog of USD 23.0 billion, up 43% organically. | A large backlog supports multi-year equipment demand. | [1] |
| Supplier sales | Johnson Controls fourth quarter fiscal 2026 sales of USD 7.1 billion, up 12% organically. | Building cooling sales are growing quickly. | [1] |
| Supplier outlook | Johnson Controls fiscal 2027 organic sales growth guidance of 11% to 12%. | Guidance points to sustained cooling demand. | [1] |
| Component integration | Trane Technologies agreed to acquire Cancoil in October 2026. | Coil supply security shortens chiller lead times. | [2] |
| Data centre chiller technology | Trane 800 VDC chiller demonstration above 1,000 tons (3.5 MW) in September 2026. | AI data centres need efficient high-capacity chillers. | [5] |
| Modular capacity | Daikin Applied Phoenix facility expanded to 191,000 square feet, about 150% more capacity. | Factory-built cooling suits fast data centre builds. | [3] |
| Liquid cooling partnership | Daikin and Delta Electronics MOU for data centre CDU solutions, announced May 2026. | Liquid cooling loops still reject heat through chillers. | [7] |
| AI cooling control | Daikin and NTT DATA proof of concept on AI control of HVAC, chiller and liquid cooling, from July 2026. | Smarter controls raise chiller plant efficiency. | [8] |
| European production | Daikin heat pump site in Poland, about EUR 300 million, inaugurated May 2026. | Regional plants shorten thermal equipment supply chains. | [4] |
| Refrigerant rules | US HFC restrictions apply to certain products from January 1, 2025. | Rules drive replacement with low-GWP chillers. | [6] |
Demand Intensity Analysis
Supplier results give a first scale check on the market. Fiscal 2026 net sales at Johnson Controls came to USD 25.7 billion [1]. The 2025 market estimate of USD 5.3 billion therefore equals about 20.6% of that single company's annual sales. The scope differs, since Johnson Controls sales include controls, fire, security and comfort HVAC beyond industrial process chillers. Even so, the ratio shows that industrial chillers form a mid-sized niche within the wider building and process cooling business.
Popularity of large data centre projects shows up in order backlogs, which indicate demand for the next two years. Johnson Controls ended fiscal 2026 with a backlog of USD 23.0 billion [1]. The 2026 market estimate of USD 5.8 billion equals about 25.2% of that backlog. The food and beverage segment, at 31% of 2026 sales or about USD 1.8 billion, equals some 7.8% of the same backlog. Orders of this size suggest that chiller installations for 2026 and 2027 are already largely secured.
Comparing growth rates shows how the forecast relates to supplier momentum. Johnson Controls guided fiscal 2027 organic sales growth of 11% to 12% [1]. The 8.8% CAGR for industrial chillers is about 2.7 points below the 11.5% guidance midpoint. The gap reflects a ten-year horizon, as current data centre orders are unlikely to grow at the same rate every year. The forecast therefore assumes steady demand from process plants, with peaks in data centre orders averaged out over the decade.
Supply of very large chiller units raises the value of each installation. Trane put the capacity of the demonstrated 800 VDC chiller at more than 1,000 tons, or 3.5 MW [5]. A 2% efficiency gain in a 200 MW data centre could free up to 1.8 MW for computing, according to the same release. Large single units of this size raise contract values per site, which supports the value growth in the forecast.
Table 3: Demand Intensity Metrics for the Industrial Chiller Market, 2026 Supplier Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Johnson Controls fiscal 2026 net sales | USD 25.7 billion | Johnson Controls, October 2026 results |
| 2025 market value as a share of Johnson Controls sales | 20.6% | Calculated from Johnson Controls sales and the 2025 market value |
| Johnson Controls backlog, fiscal 2026 | USD 23.0 billion | Johnson Controls, October 2026 results |
| 2026 market value as a share of the backlog | 25.2% | Calculated from Johnson Controls backlog and the 2026 market value |
| Food and beverage segment as a share of the backlog | 7.8% | Calculated from the 31% end user share of the 2026 market value and the backlog |
| Johnson Controls fiscal 2027 organic growth guidance | 11% to 12% | Johnson Controls, October 2026 guidance |
| Gap between the CAGR and the guidance midpoint | 2.7 points | Calculated from the 8.8% CAGR and the 11.5% guidance midpoint |
| Demonstrated 800 VDC chiller capacity | More than 1,000 tons (3.5 MW) | Trane Technologies, September 2026 |
| Power freed in a 200 MW data centre | Up to 1.8 MW | Trane Technologies, September 2026 |
Analyst Perspective
“Industrial chillers now serve two very different buyers, process plants that want reliability and data centres that want capacity fast. Suppliers that can build modular plants, secure coils and compressors, and switch to low-GWP refrigerants will capture the largest orders. Food and pharmaceutical plants will keep the base steady when data centre cycles cool.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the industrial chiller market segmented?
The market is segmented into product type, end user, and region. Screw chillers are expected to lead product type with 29.5% share in 2026, and food and beverage industries lead end user with an estimated 31%.
By product type: screw chillers, absorption chillers, reciprocating chillers, and scroll chillers.
By end user: food and beverage industries, restaurants, pharmaceutical industries, chemical industries, cosmetic industries, rubber industries, and plastics industries.
By region: chiller plants in the Americas (North America and Latin America), across Europe (Western Europe and Eastern Europe), in East Asia, in South Asia and Pacific, and in the Middle East and Africa.
Why do screw chillers lead the industrial chiller market by product type?
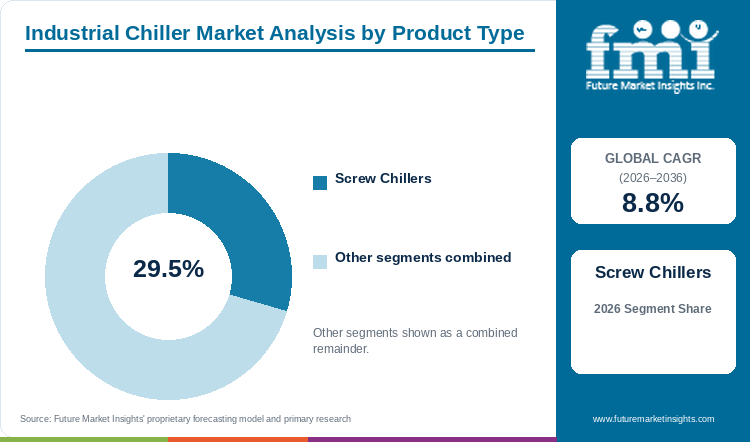
Screw chillers are expected to lead product type sales with 29.5% share in 2026, ahead of scroll chillers at an estimated 26.8% and reciprocating chillers near 22.4%.
Table 4: Product Type Share for the Industrial Chiller Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Screw Chillers | 29.5% |
| Scroll Chillers | 26.8% |
| Reciprocating Chillers | 22.4% |
| Absorption Chillers | 21.3% |
| Total | 100.0% |
Table 5: Product Type Leadership and Market Growth for the Industrial Chiller Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.8% |
| Leading Segment | Screw Chillers |
Screw chillers are expected to hold 29.5% in 2026, as screw compressors give high efficiency across the capacity range that most process plants need. Popularity of modular banks, which plants can expand one unit at a time, gives scroll chillers an estimated 26.8%. Reciprocating chillers, near 22.4%, remain in older plants and low-temperature duties. Absorption chillers hold about 21.3%, using waste heat or steam in plants with spare thermal energy. Screw chillers are expected to keep the lead through 2036, with scroll units gaining in modular installations.
- Air-cooled screw chillers, water-cooled screw chillers and variable-speed screw units make up the screw segment.
- Larger single units are raising the value of each order. Trane demonstrated a chiller of more than 1,000 tons running on 800-volt direct current in September 2026 [5]. High-capacity designs of this kind favour screw and centrifugal platforms in data centre plants.
Why do food and beverage industries lead the industrial chiller market by end user?
Food and beverage industries are estimated to lead end user sales with 31% share in 2026, ahead of pharmaceutical industries at about 17.6% and chemical industries near 15.8%.
Table 6: End User Share for the Industrial Chiller Market (percentage share), 2026
| End User | Estimated Share (2026) |
|---|---|
| Food and Beverage Industries | 31% |
| Pharmaceutical Industries | 17.6% |
| Chemical Industries | 15.8% |
| Plastics Industries | 12.4% |
| Restaurants | 9.1% |
| Rubber Industries | 7.3% |
| Cosmetic Industries | 6.8% |
| Total | 100.0% |
Food and beverage industries are estimated at 31% of end user sales in 2026, as dairies, breweries and processors chill products and process water around the clock. Use of tight temperature control in reactors and clean rooms gives pharmaceutical industries about 17.6%. Chemical industries hold near 15.8%, and plastics processors 12.4%, cooling moulds and extruders. Restaurants (9.1%), rubber (7.3%) and cosmetics (6.8%) make up the rest of end user sales. Demand for food equipment is growing at a similar pace, and the industrial mixer market is projected to grow at a 7.8% CAGR from 2025 to 2035, and FMI sees food and beverage keeping the lead.
- Dairy processing, brewing, beverage bottling and meat processing make up food and beverage demand.
- Smarter controls are also improving plant efficiency. Daikin and NTT DATA began a proof of concept in July 2026 on AI control of HVAC, chiller and liquid cooling systems [8]. Smarter plant control lowers running costs, which strengthens the case for upgrading older chillers.
Why does North America lead the industrial chiller market by region?
With hyperscale campuses and reshored plants, North America is likely to take 27.4% of chiller sales in 2026. East Asia is close at an estimated 25.8% and Western Europe near 19.6%.
Table 7: Region Share for the Industrial Chiller Market (percentage share), 2026
| Region | Estimated Share (2026) |
|---|---|
| North America | 27.4% |
| East Asia | 25.8% |
| Western Europe | 19.6% |
| South Asia and Pacific | 11.2% |
| Latin America | 6.3% |
| Middle East and Africa | 5.4% |
| Eastern Europe | 4.3% |
| Total | 100.0% |
North America is likely to hold 27.4% of 2026 sales, as hyperscale data centres and reshored factories order large chilled-water plants. East Asia, near 25.8%, has the largest manufacturing base and strong electronics demand. Western Europe holds about 19.6%, with refrigerant rules driving replacement. South Asia and Pacific, at 11.2%, grows fastest as new food and pharmaceutical plants open, ahead of Latin America (6.3%), Middle East and Africa (5.4%) and Eastern Europe (4.3%). Kitchen equipment adds to commercial cooling needs, with the industrial gas stove market projected to grow at a 3.3% CAGR from 2025 to 2035. North America is likely to keep the lead, with South Asia and Pacific gaining share.
- Hyperscale data centres, food processing plants and pharmaceutical facilities make up North American demand.
- Supply chains are moving closer to North American buyers. Cancoil runs plants in Ontario and a growing operation in Jacksonville, Texas, and Trane plans to acquire the company [2]. Local coil supply shortens delivery times for North American chiller orders.
What are the drivers, restraints, and opportunities in the industrial chiller market?
Data centre construction and growing process industries raise demand for precise cooling. High energy use and refrigerant transitions add cost, and modular and liquid-cooling-ready plants open new demand.
- Driver: Data centres, food plants and pharmaceutical sites need reliable cooling around the clock, and new capacity in these sectors adds large chiller orders.
- Restraint: Chillers use a lot of electricity, and refrigerant changes raise equipment cost and require retraining for service teams.
- Opportunity: Factory-built modular plants and chillers designed for liquid-cooled data centres let suppliers win faster, larger projects.
Data Centres Drive Large Chiller Orders
Data centre construction is the fastest-rising source of chiller orders. Johnson Controls said sustained demand for data centers supported order and backlog growth in the Americas in the fourth quarter of fiscal 2026 [1]. Data centre projects need multi-megawatt chilled-water plants, which raises value per order. As a result, suppliers with large-capacity chillers will see order backlogs stay full into the late 2020s.
Refrigerant Transition Raises Costs
Refrigerant rules remain a cost burden, as new low-GWP chillers carry higher prices for buyers and makers. EPA says manufacturers and importers of certain products have had to comply with HFC restrictions since January 1, 2025 [6]. New low-GWP designs cost more to build and service, which raises upfront prices. Consequently, some smaller plants delay replacement, though rising energy savings offset part of the cost.
Modular and Liquid-Cooling-Ready Plants
Factory-built and liquid-cooling-ready systems will account for a rising share of new chiller sales. Daikin Holdings Singapore and Delta Electronics agreed to develop coolant distribution units for AI data centres with rack densities of 100 kW to 3,000 kW [7]. Liquid-cooled servers still need chillers or dry coolers to remove heat, so chiller plants grow alongside liquid cooling. Kitchen and food equipment adds smaller cooling loads, with the countertop blast chiller market projected to grow at a 3.2% CAGR from 2025 to 2035. Suppliers that integrate chillers with liquid cooling will therefore win the largest new projects.
Which country CAGRs are profiled in the industrial chiller market?
Table 8: Country CAGR Comparison for the Industrial Chiller Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| India | 10.6% |
| China | 9.8% |
| ASEAN | 9.4% |
| United States | 9.1% |
| Germany | 7.6% |
| United Kingdom | 7.4% |
| Japan | 7.1% |
How do country-level CAGRs compare in the industrial chiller market?
FMI expects India to have the fastest chiller growth, at 10.6% a year against 8.8% globally, since dairies, drug plants and server halls all need chilled water at once. China (9.8%), ASEAN (9.4%) and the United States (9.1%) also run ahead of the global pace on manufacturing and data centre builds. Germany is projected at 7.6% and the United Kingdom at 7.4%, as replacement driven by refrigerant rules sets the pace. Japan grows slowest at 7.1%, given a mature installed base. Commercial kitchen equipment shows a slower profile, with the industrial dishwasher market projected to grow at a 3.3% CAGR from 2025 to 2035.
- New food processing and pharmaceutical plants in India add chiller demand at the build stage, favouring suppliers with local service.
- Electronics and battery factories in China need precise process cooling, which keeps screw and centrifugal orders strong.
- ASEAN attracts data centres and food plants, and tropical climates raise cooling loads per site.
- In the United States, hyperscale data centres and reshored factories order large chilled-water plants.
- Germany replaces older chillers to meet refrigerant rules, which supports steady retrofit demand.
- The United Kingdom adds data centre capacity around London, though process industry demand grows slowly.
- Most Japanese plants already have chillers, so upgrades to AI-based plant control account for much of new investment.
Full report country CAGRs cover: chiller growth rates for India, China, ASEAN, the United States, Germany, the United Kingdom and Japan, spanning 7.1% to 10.6%, plus each remaining standard country in the regional tables.
Country-wise Analysis
India Industrial Chiller Market Outlook (2026 to 2036)
India is adding food processing, pharmaceutical and data centre capacity at the same time. Supply of local engineering and service teams is growing as global suppliers chase these projects. New plants specify chillers at the design stage, which raises unit demand. FMI therefore expects Indian chiller demand to grow at a 10.6% CAGR, faster than in any other profiled country.
Key takeaway: Indian dairies, drug makers and data centre operators are all building new sites, so chiller suppliers with local service teams will win most new orders.
China Industrial Chiller Market Outlook (2026 to 2036)
Electronics, battery and chemical plants in China form the largest manufacturing base. Consumption of process cooling keeps rising as factories upgrade precision lines. With new battery and electronics lines, Chinese orders for process chillers are expected to rise 9.8% a year to 2036.
Key takeaway: Chinese electronics and battery factories need precise process cooling, so these plants will keep buying screw and centrifugal chillers as lines are upgraded.
ASEAN Industrial Chiller Market Outlook (2026 to 2036)
Southeast Asia is drawing new data centres and food plants, and hot climates raise cooling loads. Daikin and Delta Electronics agreed in April 2026 to develop data centre cooling solutions for the Asia-Oceania market [7]. Regional cooling partnerships widen the supplier base for tropical data centres. Southeast Asian chiller orders are set to expand at a 9.4% CAGR as more data centres open across the region.
Key takeaway: Data centre operators and food processors in Southeast Asia face hot climates, so these buyers will order larger chiller plants for each new site.
United States Industrial Chiller Market Outlook (2026 to 2036)
The United States leads global data centre construction, and chiller suppliers are expanding factories in the country. Daikin Applied raised Phoenix modular production capacity by about 150% in October 2026 [3]. Faster delivery of factory-built cooling suits hyperscale schedules. FMI expects American chiller sales to grow at a 9.1% CAGR as construction of new data centre campuses continues.
Key takeaway: American hyperscale operators need cooling delivered fast, so factory-built chiller modules will take a growing share of orders in the United States.
Germany Industrial Chiller Market Outlook (2026 to 2036)
Buyers of chillers in Germany include a large chemical and food industry with an ageing fleet. Refrigerant rules in Europe push plants toward low-GWP replacements. FMI projects German chiller sales to grow at a 7.6% CAGR, mainly from retrofits needed to meet refrigerant rules.
Key takeaway: German chemical and food plants will replace ageing chillers with low-GWP models to meet refrigerant rules, which keeps retrofit demand steady.
United Kingdom Industrial Chiller Market Outlook (2026 to 2036)
The United Kingdom is adding data centre capacity, though the heavy industry sector is small. Food and drink processors replace chillers on efficiency grounds. British chiller demand is likely to expand at a 7.4% CAGR.
Key takeaway: In the United Kingdom, new data centres around London will buy most new chillers, as heavy industry adds little fresh demand.
Japan Industrial Chiller Market Outlook (2026 to 2036)
Consumption of cooling in Japan is met by a large number of existing chillers built to high efficiency standards. Daikin and NTT DATA are testing AI control of chiller and liquid cooling systems at a data centre in Japan from July 2026 [8]. Control upgrades of this kind extend the life of existing plants, which slows new unit sales. Japan therefore has the lowest growth rate in the table, a 7.1% CAGR, as most plants run older chillers already in place.
Key takeaway: Sales of brand-new chillers in Japan will grow slowly, as plant owners mostly upgrade the controls on units already in service.
Who are the notable companies in the industrial chiller market?
The profiled HVAC groups with large-tonnage chiller ranges are Daikin Industries, Carrier Corporation, Trane Technologies, Johnson Controls-Hitachi Air Conditioning and Mitsubishi Electric Corporation. Process specialists Smardt Chiller Group, KKT Chillers, MTA S.p.A., Friulair S.r.l. and HYDAC International are also covered. The smaller regional and laboratory chiller suppliers covered are Reynold India, Ingersoll-Rand Company, Paul Mueller Company, Mueller Streamline Co., PolyScience and Sentry Equipment Corp.
In the industrial chiller market, the leading companies include global HVAC groups, process cooling specialists and regional makers. Large groups are securing supply chains, and Trane Technologies agreed to acquire coil maker Cancoil in October 2026 [2]. Control of key components shortens lead times, which makes competition harder for smaller assemblers. Specialists such as KKT Chillers, MTA and Friulair compete on process know-how, and FMI views engineering for specific applications as the main advantage for mid-sized suppliers. Laboratory and small process users are served by PolyScience, Paul Mueller Company and Sentry Equipment.
- Global HVAC groups with large-tonnage chiller ranges: Daikin Industries, Carrier Corporation and Trane Technologies, joined by Johnson Controls-Hitachi Air Conditioning and Mitsubishi Electric Corporation in applied systems.
- Process cooling specialists: Smardt Chiller Group, KKT Chillers, MTA S.p.A., Friulair S.r.l. and HYDAC International.
- Regional and niche suppliers: Reynold India, Ingersoll-Rand Company, Paul Mueller Company, Mueller Streamline Co., PolyScience and Sentry Equipment Corp.
Competitive Benchmarking: Industrial Chiller Market
Table 9: Competitive Benchmarking for the Industrial Chiller Market (qualitative ratings), 2026
| Company | Large-Capacity Chillers | Process Applications | Data Centre Solutions | Recent Activity |
|---|---|---|---|---|
| Trane Technologies | High | Medium | High | High |
| Daikin Industries | High | Medium | High | High |
| Carrier Corporation | High | Medium | Medium | Medium |
| Johnson Controls-Hitachi Air Conditioning | Medium | Medium | Medium | Medium |
| Smardt Chiller Group | Medium | Medium | Medium | Low |
| KKT Chillers | Low | High | Low | Low |
Ratings compare the companies on large-capacity chillers, process applications, data centre solutions and recent activity.
Key Developments in the Industrial Chiller Market
- Trane Technologies agreed to acquire Cancoil in October 2026, bringing a supplier of coils for Trane chiller lines in-house [2].
- On September 30, 2026, Trane Technologies demonstrated an 800-volt direct current chiller for AI data centres with Eaton and Danfoss [5].
- Daikin Applied tripled the Phoenix Modular Solutions footprint in October 2026, raising capacity for factory-built cooling by about 150% [3].
- Johnson Controls closed fiscal 2026 with a USD 23.0 billion backlog, up 43% organically, with data centre demand supporting Americas orders [1].
- Daikin and NTT DATA started a proof of concept in July 2026 on AI control of chiller and liquid cooling systems, aiming at lower power costs [8].
- In May 2026, Daikin Holdings Singapore and Delta Electronics announced an MOU on coolant distribution units for AI data centres [7].
- Daikin opened a heat pump plant in Poland in May 2026, investing about EUR 300 million in European thermal capacity [4].
Key Players in the Industrial Chiller Market
Global HVAC Groups
- Daikin Industries
- Carrier Corporation
- Trane Technologies
- Johnson Controls-Hitachi Air Conditioning
- Mitsubishi Electric Corporation
Process Cooling Specialists
- Smardt Chiller Group
- KKT Chillers
- MTA S.p.A.
- Friulair S.r.l.
- HYDAC International
Regional and Niche Suppliers
- Reynold India
- Ingersoll-Rand Company
- Paul Mueller Company
- Mueller Streamline Co.
- PolyScience
- Sentry Equipment Corp
Industrial Chiller Market - Report Scope
Table 10: Report Scope for the Industrial Chiller Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; end user; region |
| Quantitative units | USD billion |
| Market definition | Screw, scroll, reciprocating and absorption chillers that remove process and facility heat in industrial, commercial food service and data centre applications. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Daikin Industries, Carrier Corporation, Trane Technologies, Johnson Controls-Hitachi Air Conditioning, Mitsubishi Electric Corporation, Smardt Chiller Group, KKT Chillers, MTA S.p.A., Friulair S.r.l., HYDAC International, Reynold India, Ingersoll-Rand Company, Paul Mueller Company, Mueller Streamline Co., PolyScience, Sentry Equipment Corp |
| Forecast period | 2026 to 2036 |
Industrial Chiller Market - Research Methodology
Table 11: Research Methodology for the Industrial Chiller Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Process industry capacity, data centre construction, refrigerant regulation, chiller technology and supplier strategy. |
| Market Sizing | Sizing combines unit shipments, capacity mix and pricing across product types, end users and regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Industrial Chiller Market by Segments
Industrial Chiller Market segmented by Product Type:
- Screw Chillers
- Absorption Chillers
- Reciprocating Chillers
- Scroll Chillers
Industrial Chiller Market segmented by End User:
- Food and Beverage Industries
- Restaurants
- Pharmaceutical Industries
- Chemical Industries
- Cosmetic Industries
- Rubber Industries
- Plastics Industries
Industrial Chiller Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Johnson Controls International plc. (2026, October 27). Johnson Controls Reports Q4 and FY26 Results; Initiates FY27 Guidance. https://s21.q4cdn.com/502874060/files/doc_news/Johnson-Controls-Reports-Q4-and-FY26-Results-Initiates-FY27-Guidance-2026.pdf
- [2] Trane Technologies plc. (2026, October 21). Trane Technologies to Acquire Cancoil, Strengthening Supply Chain Resiliency and Thermal Management Expertise. https://investors.tranetechnologies.com/news-and-events/news-releases/news-release-details/2026/Trane-Technologies-to-Acquire-Cancoil-Strengthening-Supply-Chain-Resiliency-and-Thermal-Management-Expertise/default.aspx
- [3] Daikin Industries, Ltd. (2026, October 14). Daikin Applied Triples Modular Solutions Manufacturing Footprint to Meet Growing Customer Demand. https://www.daikin.com/press/2026/20261015_1
- [4] Daikin Industries, Ltd. (2026, May 21). Daikin inaugurates new heat pump production site in Poland. https://www.daikin.com/press/2026/20260522
- [5] Trane Technologies plc. (2026, September 30). Trane Technologies Demonstrates Industry-First 800-Volt Direct Current Chiller for Next-Generation AI Data Centers. https://investors.tranetechnologies.com/news-and-events/news-releases/news-release-details/2026/Trane-Technologies-Demonstrates-Industry-First-800-Volt-Direct-Current-Chiller-for-Next-Generation-AI-Data-Centers/default.aspx
- [6] U.S. Environmental Protection Agency. (2026, May 26). Technology Transitions Program. https://www.epa.gov/climate-hfcs-reduction/technology-transitions-program
- [7] Daikin Industries, Ltd. (2026, May 11). Daikin Holdings Singapore and Delta Electronics Sign MOU to Advance Next Generation Data Centre Cooling Solutions in Asia-Oceania Market. https://www.daikin.com/press/2026/20260511
- [8] Daikin Industries, Ltd. (2026, July 6). Daikin and NTT DATA Launch Joint Proof of Concept for AI-Driven Data Center Cooling Optimization. https://www.daikin.com/press/2026/20260706
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the industrial chiller market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which end user holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the industrial chiller market expected in 2026?
In 2026, the industrial chiller market is estimated by FMI at USD 5.8 billion, up from USD 5.3 billion in 2025, as data centres and process plants add cooling capacity.
What CAGR is projected for the industrial chiller market through 2036?
Between 2026 and 2036, industrial chillers are projected to grow at an 8.8% CAGR to USD 13.5 billion, since new plants and refrigerant rules keep replacement and expansion demand high.
Which product type holds a notable market share in 2026?
Screw chillers are expected to hold 29.5% of 2026 sales, given efficient part-load control, and scroll chillers follow at about 26.8%.
Which end user holds a notable market share in 2026?
Food and beverage industries are likely to lead with 31%, as processing and storage need constant cooling, and pharmaceutical industries hold about 17.6%.
Which country has a notable expansion outlook through 2036?
Indian chiller demand has the strongest FMI outlook, at a 10.6% CAGR, as food, drug and data centre capacity is built at the same time, with China second at 9.8%.
Who are the key companies in the industrial chiller market?
Daikin, Carrier, Trane Technologies, Johnson Controls-Hitachi and Mitsubishi Electric lead global HVAC, and Smardt, KKT Chillers, MTA, Friulair and HYDAC compete in process cooling on engineering for specific applications.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Screw Chillers
- Absorption Chillers
- Reciprocating Chillers
- Scroll Chillers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Food and Beverage Industries
- Restaurants
- Pharmaceutical Industries
- Chemical Industries
- Cosmetic Industries
- Rubber Industries
- Plastics Industries
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Trane Technologies
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Daikin Industries
- Carrier Corporation
- Johnson Controls-Hitachi Air Conditioning
- Smardt Chiller Group
- KKT Chillers
- Mitsubishi Electric Corporation
- MTA S.p.A.
- Friulair S.r.l.
- HYDAC International
- Reynold India
- Ingersoll-Rand Company
- Paul Mueller Company
- Mueller Streamline Co.
- PolyScience
- Sentry Equipment Corp
- Trane Technologies
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


