

- Market Size (2026)
- USD 72.9 Bn
- Forecast (2036)
- USD 102.8 Bn
- CAGR (2026 to 2036)
- 3.5%
How big is Industrial Oil Market in 2026?
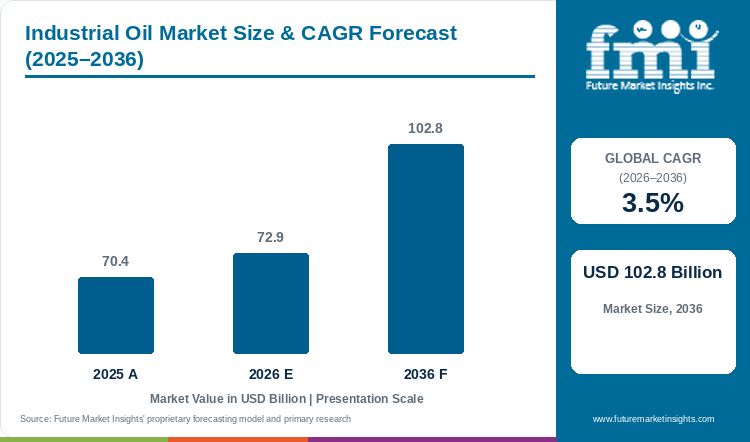
The industrial oil market is estimated at USD 70.4 billion in 2025 and is forecast to reach USD 72.9 billion in 2026. The market is expected to grow at a 3.5% CAGR and is projected to reach USD 102.8 billion by 2036.
Adoption of industrial oil across plants and wind farms is estimated to support sales of USD 70.4 billion in 2025, rising to an expected USD 72.9 billion in 2026. By 2036 the market is projected to reach USD 102.8 billion, expanding at a 3.5% CAGR across the forecast period. The Global Wind Energy Council reported a record 165 GW of new wind capacity for 2025, 40% more than in 2024.[1] Each new turbine adds a gearbox and a pitch system that need fresh oil for two decades.
American plants are likely to see industrial oil sales expand at a 3.2% CAGR, about half a point ahead of the 2.6% pace expected for the United Kingdom. American wind farms reached 161.2 GW of capacity after adding 6.9 GW in 2025.[1] Scheduled oil changes on more than 160 GW of turbines give American blenders steady orders. British plants work from a smaller heavy-industry base and grow mainly through replacement drains.
Of oil type sales in 2026, FMI analysts expect process oils to hold 31.2%. Tyre, rubber and ink makers blend process oil into each batch, so the oil leaves inside the product and never comes back for a drain. Blenders selling both product-bound and drain-and-fill oils will draw orders from more than one point of the industrial cycle.
Key Market Trends & Insights
- Cheap Group I and Group II base stocks give mineral oil an estimated 72.5% of type sales in 2026, against roughly 21.3% for synthetic and semi-synthetic grades.
- Tyre and rubber plants buy process oil as an ingredient, so the grade is likely to hold 31.2% of oil type sales in 2026, with hydraulic oils second near 22.4%. Naphthenic suppliers Process Oils and Ergon each added 45 cents per gallon to list prices from 13 March 2026.[2]
- Crude-based supply is estimated to provide 93.8% of source volume in 2026, leaving 6.2% to rapeseed, soybean, palm, sunflower and other plant oils.
- Manufacturing plants are projected to buy 34.6% of industrial oil in 2026, with energy generation next at an estimated 19.8%. Quaker Houghton, a maker of metalworking and process fluids, said new business across all segments raised sales volumes 7% in Q2 2026.[3]
Regional Highlights
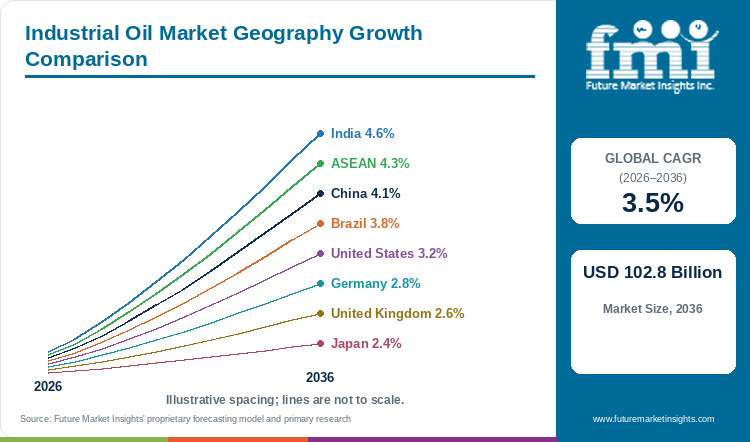
- India heads the country ranking at 4.6%, faster than the market average of 3.5%, per FMI's country model.
- ASEAN, China and Brazil also beat the global figure, at 3.8% to 4.3%. Mature plant bases keep the United States at 3.2% and Germany at 2.8%. The United Kingdom, at 2.6%, runs only a little ahead of Japan, last in the country ranking at 2.4%.
- The VDMA expects real machinery production in Germany to fall 2% in 2026, a fourth year of decline, and to rise 3% in 2027.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Industrial Oil Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 70.4 billion |
| Estimated Market Size in 2026 | USD 72.9 billion |
| Projected Market Size by 2036 | USD 102.8 billion |
| CAGR, 2026 to 2036 | 3.5% |
| Added Revenue, 2026 to 2036 | USD 29.9 billion |
| Market Expansion Multiple | 1.4x |
Industrial oil is bought on supply contracts that reprice when base oil costs move, so orders and prices react within weeks of a crude shock. Base oil producers announced increases in March 2026 after the Strait of Hormuz closed to tanker traffic, with ExxonMobil adding 24 cents per gallon to Group I, II and II+ grades from 20 March.[2] Customer pre-buying and supply gaps at rivals helped Fuchs raise sales 11% to EUR 2,003 million in the six months to June 2026.[5] Industrial grades sit inside a wider lubricant pool, and the lubricants market is forecast to expand at a CAGR of 4.5% over the same decade. In FMI's sizing, industrial oil sales are projected to gain USD 29.9 billion between the 2026 base and 2036, an increase of about 41%. Pre-buying is the main short-term risk, since Fuchs expects stock built in the first half to weigh on second-half volumes.[5]
Base Oil Supply, Price Pass-Through and New Blending Capacity
Gulf supply losses tightened base oil through the spring of 2026. Shell halted the Pearl GTL Group III plant in Qatar after attacks on 19 March 2026, and ADNOC shut part of the Ruwais complex, which houses a 600,000 tonne per year Group II and Group III plant.[2] Close to half of U.S. Group III imports come from Bahrain, the UAE and Qatar, and some lubricant makers put through price rises of 9% to 16%.[2] Fuchs said base oil availability remained severely limited in July 2026.[5] Blenders with refinery-linked supply will keep plants running, and independent blenders will ration grades to contract customers.
Oil companies are also adding blending and grease capacity near industrial buyers. Shell Indonesia started a grease plant with capacity of up to 12 kilotonnes inside the Marunda blending complex in September 2026, serving steel, smelting, mining and power generation.[6] Idemitsu Kosan signed a base oil supply and procurement agreement with Saudi Aramco in February 2026.[7] BP agreed in December 2025 to sell 65% of Castrol to Stonepeak at an enterprise value of USD 10.1 billion, with completion expected by the end of 2026.[8] Local plants and secured base oil will decide which suppliers keep industrial accounts through the next price spike.
Table 2: Base Oil, Capacity and Demand Indicators for the Industrial Oil Market (prices, capacity and growth), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Global wind installations, 2025 | 165 GW; up 40% | More gearboxes and pitch systems to fill. | [1] |
| ExxonMobil base oil posting, March 2026 | Up 24 cents per gallon | Base oil costs pass into oil prices. | [2] |
| Fuchs sales, H1 2026 | EUR 2,003 million; up 11% | Pre-buying raised first-half orders. | [5] |
| German machinery production outlook, 2026 | Down 2% in real terms; up 3% expected for 2027 | Machine fleets set hydraulic and gear oil orders. | [4] |
| Shell Indonesia grease plant, September 2026 | Up to 12 kilotonnes capacity | Local supply for mining and steel. | [6] |
| Castrol sale to Stonepeak, December 2025 | 65% stake; USD 10.1 billion enterprise value | Ownership change at a major brand. | [8] |
Analyst Perspective
“The March 2026 base oil shock separated blenders that own supply from blenders that buy on the spot market. Customers in steel, mining and power switched to whoever could deliver that spring, and I expect most of those accounts to stay with the new supplier for years.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the industrial oil market segmented?
The market is segmented into type, oil type, source, end use, and region. Mineral oils are expected to lead type sales with an estimated 72.5% share in 2026, and process oils lead oil type with 31.2%.
By type: mineral, synthetic and semi-synthetic, and bio-based.
By oil type: process oil, hydraulic oils, industry engine oils, gear oils, metal working fluids, turbine and circulating oils, refrigerating oils, and compressor oils.
By source: crude oil, soybean, rapeseed, sunflower, palm, and others.
By end use: energy generation, oil and gas, manufacturing, automotive, and heavy engineering equipment.
By region: plant and fleet operators in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do mineral oils lead industrial oil sales by type?
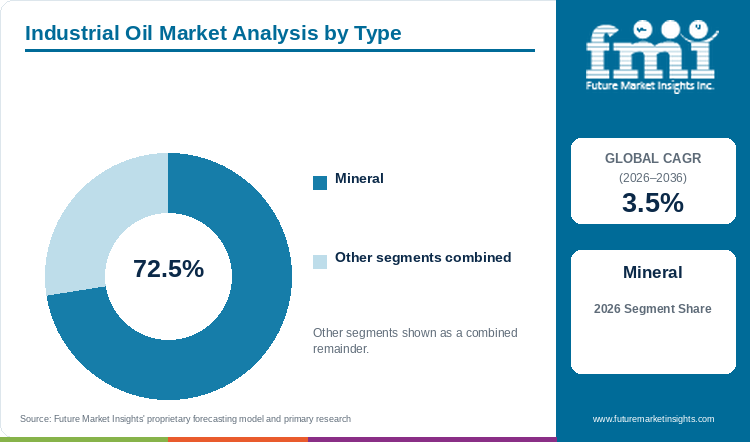
Mineral oils are expected to lead type sales with an estimated 72.5% share in 2026, ahead of synthetic and semi-synthetic oils at about 21.3% and bio-based oils at roughly 6.2%.
Table 3: Type Share for the Industrial Oil Market (percentage share), 2026
| Type | Estimated Share (2026) |
|---|---|
| Mineral | 72.5% |
| Synthetic and Semi-Synthetic | 21.3% |
| Bio-based | 6.2% |
| Total | 100.0% |
Table 4: Type Leadership and Market Growth for the Industrial Oil Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.5% |
| Leading Segment | Mineral |
Mineral oils are expected to lead with an estimated 72.5% share in 2026, because Group I and Group II base stocks cost far less per litre and suit most hydraulic, gear and process duties. ExxonMobil and Chevron listed rises of 24 to 40 cents per gallon on Group I and II base oils in March 2026, and buyers still kept mineral grades for bulk uses.[2] Synthetic and semi-synthetic oils, an estimated 21.3%, gain on long drain intervals in turbines and compressors, and the March shock put Group III supply most at risk, since close to half of U.S. Group III imports come from the Gulf.[2] Bio-based oils, near 6.2%, serve forestry, marine and food-plant equipment with spill risk, and the castor oil derivatives market is likely to expand at a 4.5% CAGR, a full point faster than industrial oil. Plant engineers will keep mineral oil for bulk sumps and pay for synthetics only on machines that lose money during a long drain.
- Paraffinic Group I and II stocks supply most mineral volume, with naphthenic grades for low-temperature duties.
- Motiva raised Group II 100N by 85 cents per gallon and Group II+ and III by USD 1.00 from 23 March 2026.[2]
Why do process oils lead industrial oil sales by oil type?
Process oils are likely to hold 31.2% of oil type sales in 2026, with hydraulic oils at an estimated 22.4% and metal working fluids at 11.8%.
Table 5: Oil Type Share for the Industrial Oil Market (percentage share), 2026
| Oil Type | Estimated Share (2026) |
|---|---|
| Process Oil | 31.2% |
| Hydraulic Oils | 22.4% |
| Metal Working Fluids | 11.8% |
| Industry Engine Oils | 10.1% |
| Gear Oils | 8.7% |
| Turbine and Circulating Oils | 6.3% |
| Compressor Oils | 5.6% |
| Refrigerating Oils | 3.9% |
| Total | 100.0% |
Tyre, rubber, adhesive and ink plants consume process oil as an ingredient, which puts process oils in the lead at a projected 31.2% share in 2026. Hydraulic oils, an estimated 22.4%, fill presses and mobile machines and are refilled between drains. Metal working fluids, near 11.8%, are diluted and recycled in machine shops, which cuts volume per part. Engine oils for stationary engines take about 10.1%, and gear oils about 8.7%. Turbine and circulating oils, around 6.3%, last for years between changes. Compressor oils, near 5.6%, and refrigerating oils, roughly 3.9%, serve smaller sumps. Rust protection in the same sumps links blenders to additive makers, and the corrosion inhibitors market is predicted to rise at a 4.1% CAGR as plant owners guard ageing machines. Tyre makers order process oil by the tanker, which keeps the segment ahead of every drain-and-fill grade.
- Process oil comes in naphthenic, paraffinic and aromatic extract grades.
- Calumet followed with a 25 cent per gallon naphthenic increase from 25 March 2026.[2]
Why does crude oil lead industrial oil sales by source?
Crude-based oil is estimated at 93.8% of source volume in 2026, and plant oils share the remaining 6.2%, led by rapeseed at about 2.2%.
Table 6: Source Share for the Industrial Oil Market (percentage share), 2026
| Source | Estimated Share (2026) |
|---|---|
| Crude Oil | 93.8% |
| Rapeseed | 2.2% |
| Soybean | 1.6% |
| Palm | 1.1% |
| Sunflower | 0.7% |
| Others | 0.6% |
| Total | 100.0% |
Nearly every mineral and synthetic base stock starts at a refinery, so crude oil is estimated to supply 93.8% of source volume in 2026. Rapeseed, an estimated 2.2%, gives Europe a home-grown base for biodegradable hydraulic oil. Soybean, near 1.6%, plays the same role in the Americas. Palm, at about 1.1%, and sunflower, near 0.7%, feed esters in Asia and Eastern Europe, and other plant sources take 0.6%. The bio-based share of 6.2% by type matches the plant-oil share by source. Refinery supply carried the March 2026 shock, when Asian suppliers trimmed base oil output as governments put fuels first.[2] Buyers needing biodegradable oil for forestry or marine work will pay the plant-oil premium, and every other buyer will stay with crude-based grades.
- Group I, Group II, Group III and gas-to-liquids base stocks all count as crude-based supply.
- Shell halted the Pearl GTL Group III plant in Qatar after attacks on 19 March 2026.[2]
Why does manufacturing lead industrial oil sales by end use?
Manufacturing is projected to buy an estimated 34.6% of industrial oil in 2026, ahead of energy generation at about 19.8% and automotive plants at 18.2%.
Table 7: End Use Share for the Industrial Oil Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Manufacturing | 34.6% |
| Energy Generation | 19.8% |
| Automotive | 18.2% |
| Oil and Gas | 15.1% |
| Heavy Engineering Equipment | 12.3% |
| Total | 100.0% |
Presses, moulders, machine tools and process lines run in every industrial country, so manufacturing will lead end use in 2026 with an estimated 34.6% share. Metalworking fluid maker Quaker Houghton said in July 2026 that underlying end-market activity was similar to prior-year levels.[3] Energy generation, near 19.8%, buys turbine, gear and transformer-adjacent circulating oils for power plants and wind farms. Automotive plants, at about 18.2%, use metal working fluids and hydraulic oil on stamping and machining lines. Oil and gas, an estimated 15.1%, buys compressor and engine oils for rigs and pipelines. Heavy engineering equipment, near 12.3%, follows construction and mining fleets. Plant buyers place framework contracts for all grades at one site, which keeps manufacturing in front.
- Manufacturing buyers include metal processing, plastics, paper, food and chemical plants.
- The VDMA reported a 5% real gain in order intake at German machine builders for January to July 2026.[4]
What are the drivers, restraints, and opportunities in the industrial oil market?
New wind farms, plants and machine fleets add sumps that need regular oil changes. Base oil shortages and price spikes squeeze independent blenders, and local blending and grease plants near industrial clusters give suppliers a delivery advantage.
- Driver: Each new turbine, press or excavator adds a sump that is filled and drained on schedule, so the installed machine base sets a floor under oil volume.
- Restraint: Base oil supply concentrated in a few refining regions leaves blenders exposed to sudden shortages, which forces price rises and rationing to contract customers.
- Opportunity: Industrial buyers value delivery security after supply shocks, which rewards suppliers that build blending and grease capacity close to plants and mines.
A Growing Machine Base Keeps Oil Drains Regular
Installed machines drive industrial oil volume. Wind installations reached a record 165 GW in 2025, and GWEC expects 969 GW of new capacity from 2026 to 2030.[1] Non-euro orders at German machine builders were 14% higher in the seven months to July 2026, the VDMA reported.[4] Every added turbine and production line brings a new schedule of gear, hydraulic and circulating oil changes.
Base Oil Shortages Squeeze Independent Blenders
Producers of industrial oil face a base oil supply that can tighten within days, and FMI analysts expect that exposure to recur through 2036. The Strait of Hormuz was closed to tanker traffic in March 2026, and suppliers withdrew spot offers and placed customers on allocation.[2] Fuchs warned that rising raw material prices would pressure margins over July to December 2026.[5] Independent blenders without refinery supply will pay the highest spot prices and lose volume to integrated suppliers.
Local Blending and Grease Plants Secure Industrial Accounts
Demand for locally blended industrial oil is rising around large industrial clusters. Shell Indonesia said the Marunda grease plant brings Shell products and expertise closer to customers in mining, steel and power generation.[6] Fuchs assumed full ownership of the former Turkish joint venture in late April 2026.[5] Suppliers with a local plant will deliver within days during a shortage, and industrial buyers will reward that with multi-year contracts.
Which country CAGRs are profiled in the industrial oil market?
Table 8: Country CAGR Comparison for the Industrial Oil Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 4.6% |
| ASEAN | 4.3% |
| China | 4.1% |
| Brazil | 3.8% |
| United States | 3.2% |
| Germany | 2.8% |
| United Kingdom | 2.6% |
| Japan | 2.4% |
How do country-level CAGRs compare in the industrial oil market?
China installed 120.5 GW of wind capacity in 2025, out of a record 165 GW added globally, GWEC reported.[1] Four profiled markets build new sumps faster than the 3.5% global CAGR in FMI's country table, led by India at 4.6% and ASEAN at 4.3%. China, at 4.1%, and Brazil, at 3.8%, follow on wind farms, smelters and mines. The United States and Germany, at 3.2% and 2.8%, mostly refill machines already running, and the United Kingdom, at 2.6%, runs only slightly faster than Japan at 2.4%.
- India commissioned 6.3 GW of new wind capacity during 2025.
- Shell opened a 12 kilotonne grease plant in Indonesia in September 2026.
- China installed 120.5 GW of the 165 GW of wind capacity added globally in 2025.
- Brazil closed 2025 with 36.0 GW of installed wind capacity.
- Quaker Houghton grew Americas net sales 7% in the June quarter of 2026.
- German machinery production is expected to fall 2% in real terms in 2026.
- British demand comes mainly from replacement drains in existing plants.
- Japanese buyers source base oil through Idemitsu Kosan and the Saudi Aramco agreement.
Full report country CAGRs cover: eight country tables (India, ASEAN, China, Brazil, the United States, Germany, the United Kingdom and Japan) set inside five of the seven regions, with Eastern Europe and Middle East and Africa given regional tables only.
Country-wise Analysis
India Industrial Oil Market Outlook (2026 to 2036)
New wind farms, steel mills and cement kilns give India the strongest profiled outlook, with industrial oil sales projected to rise at a 4.6% CAGR, faster than the market average of 3.5%. Indian wind farms added 6.3 GW in 2025 and reached 54.5 GW of capacity.[1] Castrol, which BP is selling to Stonepeak, holds minority interests in India of 49%.[8] Each of those sites adds gear and hydraulic oil volume that returns at every drain.
Key takeaway: New turbines and mills give India the fastest profiled CAGR, at 4.6%.
ASEAN Industrial Oil Market Outlook (2026 to 2036)
Shell Indonesia started a grease plant with up to 12 kilotonnes of capacity in September 2026, and Indonesia's industry minister said the plant should strengthen the country's manufacturing base.[6] Smelter and mine projects across Indonesia and Vietnam support a projected 4.3% CAGR for ASEAN, and new pulp mills will add further gear oil and grease orders as each mill opens.
Key takeaway: Local blending and grease capacity is following new smelters and mines across ASEAN.
China Industrial Oil Market Outlook (2026 to 2036)
Wind and factory additions are expected to carry China at a 4.1% CAGR per FMI's country model, a little above the global figure for the largest profiled market. China added 120.5 GW of wind capacity in 2025 and reached 640.5 GW, and GWEC expects about 63% of 2026 installations to be Chinese.[1] Sinopec and PetroChina supply most domestic base oil, so local refiners will take most of the new turbine and plant volume.
Key takeaway: China stays near the top of the profiled list on volume as wind and factory additions continue.
Brazil Industrial Oil Market Outlook (2026 to 2036)
Brazil added 2.3 GW of wind turbines in 2025, each with a gearbox to fill.[1] Mining and agribusiness fleets add hydraulic and gear oil buying across the interior, supporting a forecast 3.8% CAGR.
Key takeaway: Wind farms and mining fleets carry growth in Brazil.
United States Industrial Oil Market Outlook (2026 to 2036)
Demand for industrial oil in the United States is likely to increase at a 3.2% CAGR, just 0.3 points below the global figure. Americas net sales at Quaker Houghton rose 7% to USD 236.5 million in April to June 2026, against significant raw material inflation.[3] Close to half of U.S. Group III base oil imports come from the Persian Gulf, so American blenders felt the March 2026 shock directly.[2] Higher plant run rates will raise drain frequency, and base oil security will decide supplier choice.
Key takeaway: Plant run rates support American volume, and Gulf supply risk shapes supplier choice.
Germany Industrial Oil Market Outlook (2026 to 2036)
German machine builders produced 4.1% less in real terms in the first seven months of 2026 than a year earlier, the VDMA reported.[4] FMI places Germany at a 2.8% CAGR, 0.7 points below the global figure. In H1 2026, Mannheim-based Fuchs grew EMEA sales by 11% to EUR 1,156 million.[5] Machine shops and metal plants running at lower rates will buy less hydraulic and metal working oil until orders turn into output.
Key takeaway: Weak machinery output holds Germany below the global rate.
United Kingdom Industrial Oil Market Outlook (2026 to 2036)
Replacement drains in British food, aerospace and process plants underpin a projected 2.6% CAGR for the United Kingdom. Make UK expects British manufacturing output growth of 1.2% for 2026, slowing to 0.3% for 2027, with Brent crude averaging USD 88.02 per barrel in 2026.[9] Offshore wind service work adds gear oil orders on top.
Key takeaway: Replacement drains and offshore wind service set the British outlook.
Japan Industrial Oil Market Outlook (2026 to 2036)
Idemitsu Kosan signed a base oil agreement with Saudi Aramco in February 2026 and expects demand for higher-value lubricants to keep rising as industries focus on energy efficiency.[7] Japan, last in the country ranking at a projected 2.4% CAGR, has a mature plant base shifting toward longer-life synthetic grades that need fewer drains.
Key takeaway: Longer drain intervals keep volume growth in Japan the slowest of the profiled group.
Who are the notable companies in the industrial oil market?
ExxonMobil, Shell, TotalEnergies, Chevron, Castrol, Fuchs, Idemitsu Kosan, SK Enmove, Sinopec, Phillips 66 and PetroChina are the profiled companies.
FMI profiles eleven companies, from integrated oil majors and Asian refiners to two lubricant specialists. Fuchs raised the 2026 EBIT outlook to EUR 460 million to EUR 480 million after half-year sales of EUR 2,003 million.[5] ExxonMobil, Chevron and SK Enmove announced base oil price increases in March 2026.[2] Shell Indonesia opened a grease plant in September 2026.[6] BP agreed to sell 65% of Castrol to Stonepeak in December 2025.[8]
- Integrated oil majors: ExxonMobil, Shell, TotalEnergies, Chevron and Phillips 66.
- Asian refiners: Sinopec, PetroChina, Idemitsu Kosan and SK Enmove.
- Lubricant specialists: Fuchs and Castrol.
Competitive Benchmarking: Industrial Oil Market
Table 9: Competitive Benchmarking for the Industrial Oil Market (qualitative documentation ratings), 2026
| Company | Base Oil Integration | Industrial Range | Regional Plants | Recency |
|---|---|---|---|---|
| ExxonMobil | High | High | High | High |
| Shell | High | High | High | High |
| Fuchs | Low | High | Medium | High |
| Castrol | Low | Medium | Medium | Medium |
| Idemitsu Kosan | High | Medium | Medium | Medium |
Grades run from High to Low on the depth of dated company and trade press detail and carry no market-share meaning.
Key Developments in the Industrial Oil Market
- On 17 September 2026, the VDMA cut the 2026 German machinery production forecast to a 2% real decline.[4]
- In September 2026, Shell Indonesia started production at a grease plant of up to 12 kilotonnes capacity.[6]
- In September 2026, Make UK forecast British manufacturing output growth of 1.2% for 2026.[9]
- On 31 July 2026, Fuchs announced an 11% rise in January to June sales, to EUR 2,003 million.[5]
- On 30 July 2026, Quaker Houghton put June-quarter net sales at USD 532.6 million, 10% above the prior-year quarter.[3]
- On 20 April 2026, the Global Wind Energy Council counted a record 165 GW of turbines installed during 2025.[1]
- In March 2026, ExxonMobil, Motiva, Chevron and SK Enmove raised base oil postings after Gulf supply losses.[2]
- In February 2026, Idemitsu Kosan signed a base oil agreement with Saudi Aramco.[7]
- On 24 December 2025, BP agreed to sell 65% of Castrol to Stonepeak.[8]
Key Players in the Industrial Oil Market
Integrated Oil Majors
- ExxonMobil
- Shell
- TotalEnergies
- Chevron
- Phillips 66
Asian Refiners
- Sinopec
- PetroChina
- Idemitsu Kosan
- SK Enmove
Lubricant Specialists
- Fuchs
- Castrol
Industrial Oil Market - Report Scope
Table 10: Report Scope for the Industrial Oil Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Type; oil type; source; end use; region |
| Quantitative units | USD billion |
| Market definition | Mineral, synthetic, semi-synthetic and bio-based oils used in industrial machines and processes, including process, hydraulic, engine, gear, metal working, turbine, refrigerating and compressor oils. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | ExxonMobil, Shell, TotalEnergies, Chevron, Castrol, Fuchs, Idemitsu Kosan, SK Enmove, Sinopec, Phillips 66, PetroChina |
| Forecast period | 2026 to 2036 |
Industrial Oil Market - Research Methodology
Table 11: Research Methodology for the Industrial Oil Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Lubricant and fluid maker results, base oil price reports, machinery and manufacturing trade body forecasts, wind industry data and trade press from May 2025 onward. |
| Desk Research | Desk research covers base oil supply, price postings, plant openings, industrial output and wind installations. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 70.4 billion and the 3.5% CAGR for 2026 to 2036. |
| Data Validation | Prices, capacities and output figures were matched to the company, agency or trade publication that reported them. |
Industrial Oil Market by Segments
Industrial Oil Market segmented by Type:
- Mineral
- Synthetic and Semi-Synthetic
- Bio-based
Industrial Oil Market segmented by Oil Type:
- Process Oil
- Hydraulic Oils
- Industry Engine Oils
- Gear Oils
- Metal Working Fluids
- Turbine and Circulating Oils
- Refrigerating Oils
- Compressor Oils
Industrial Oil Market segmented by Source:
- Crude Oil
- Soybean
- Rapeseed
- Sunflower
- Palm
- Others
Industrial Oil Market segmented by End Use:
- Energy Generation
- Oil and Gas
- Manufacturing
- Automotive
- Heavy Engineering Equipment
Industrial Oil Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Global Wind Energy Council. (2026, April 20). Global wind installations rise a record 40% as industry charts way out of energy crisis. https://www.gwec.net/news/global-wind-installations-rise-record-40-as-industry-charts-way-out-of-energy-crisis
- [2] Lubes'N'Greases. (2026, March 25). Weekly Americas Base Oil Price Report. https://www.lubesngreases.com/bor-americas/weekly-americas-base-oil-price-report-65/
- [3] Quaker Houghton. (2026, July 30). Quaker Houghton Announces Second Quarter 2026 Results. https://investors.quakerhoughton.com/node/22971
- [4] produktion.de. (2026, September 18). Maschinenproduktion: VDMA senkt Prognose für 2026. https://www.produktion.de/wirtschaft/maschinenproduktion-vdma-senkt-prognose-fuer-2026/2738100
- [5] FUCHS SE. (2026, July 31). FUCHS reports strong first half of 2026. https://www.fuchs.com/group/press/press-releases/company-business-finances/news-detail/view/10377-FUCHS-reports-strong-first-half-of-2026/
- [6] Indian Chemical News. (2026, September 16). Shell starts production at new grease manufacturing plant in Indonesia. https://www.indianchemicalnews.com/petro-chemical/shell-starts-production-at-new-grease-manufacturing-plant-in-indonesia-31907
- [7] Lubes'N'Greases. (2026, February 25). Idemitsu Inks Base Oil Alliance With Saudi Aramco. https://www.lubesngreases.com/lubereport-americas/11_08/idemitsu-base-oil-alliance-with-saudi-aramco/
- [8] BP p.l.c. (2025, December 24). bp agrees sale of 65% stake in Castrol to Stonepeak (Form 6-K). https://www.sec.gov/Archives/edgar/data/313807/000165495425014315/a8066m.htm
- [9] Make UK and BDO. (2026, September). Manufacturing Outlook 2026 Q3. https://www.makeuk.org/docs/manufacturing-outlook-2026-q3pdf/download
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the industrial oil market during 2026?
- What market size is projected by 2036?
- Which type holds notable share?
- Which oil type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the industrial oil market expected in 2026?
FMI puts industrial oil sales at USD 72.9 billion for 2026, up from USD 70.4 billion in 2025. Sales are projected to reach USD 102.8 billion by 2036.
What CAGR is projected for the industrial oil market through 2036?
Growth from 2026 to 2036 is expected at a 3.5% CAGR. New turbines, presses and process lines, each with a sump to fill and drain, carry that growth.
Which type holds a notable market share in 2026?
Bulk sumps keep mineral oils in front, at an estimated 72.5% share in 2026. Synthetic and semi-synthetic oils follow at an estimated 21.3%.
Which oil type holds a notable market share in 2026?
Oil type sales are likely to be led by process oils at 31.2% in 2026. Hydraulic oils come next at an estimated 22.4%.
Which country has a notable expansion outlook through 2036?
Quickest of the eight profiled countries is India, at a 4.6% CAGR in the FMI outlook. ASEAN follows at 4.3%.
Who are the key companies in the industrial oil market?
Key suppliers include ExxonMobil, Shell, TotalEnergies, Chevron and Phillips 66 among the oil majors. Sinopec, PetroChina, Idemitsu Kosan, SK Enmove, Fuchs and Castrol complete the profiled group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Mineral
- Synthetic and Semi-Synthetic
- Bio-based
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Oil Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Oil Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Oil Type, 2026 to 2036
- Process Oil
- Hydraulic Oils
- Industry Engine Oils
- Gear Oils
- Metal Working Fluids
- Turbine and Circulating Oils
- Refrigerating Oils
- Compressor Oils
- Y-o-Y Growth Trend Analysis By Oil Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Oil Type, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Crude Oil
- Soybean
- Rapeseed
- Sunflower
- Palm
- Others
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Energy Generation
- Oil and Gas
- Manufacturing
- Automotive
- Heavy Engineering Equipment
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Type
- By Oil Type
- By Source
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Oil Type
- By Source
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Oil Type
- By Source
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Oil Type
- By Source
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ExxonMobil
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Shell
- Fuchs
- Castrol
- Idemitsu Kosan
- TotalEnergies
- Chevron
- Phillips 66
- Sinopec
- PetroChina
- SK Enmove
- ExxonMobil
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


