

- Market Size (2026)
- USD 89.4 Bn
- Forecast (2036)
- USD 191.3 Bn
- CAGR (2026 to 2036)
- 7.9%
How big is Industrial Oxygen Market in 2026?
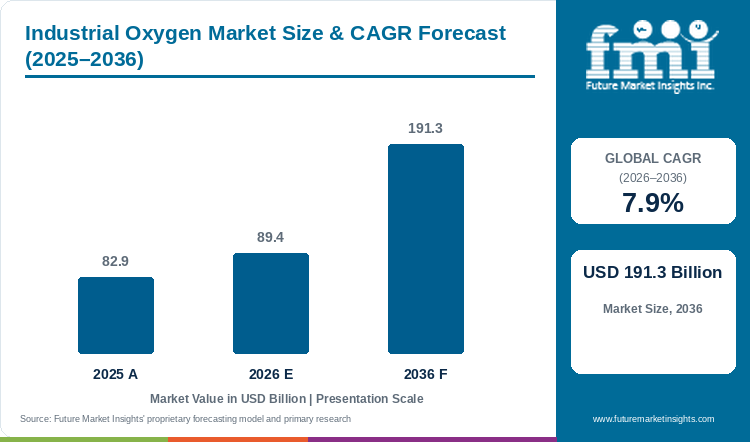
The industrial oxygen market is estimated at USD 82.9 billion in 2025 and is projected to reach USD 89.4 billion in 2026. Sales of industrial oxygen are expected to grow at a CAGR of 7.9% and reach USD 191.3 billion by 2036.
Industrial oxygen market share is concentrated in chemical plants and hospitals, and sales of industrial oxygen are estimated at USD 82.9 billion in 2025. In FMI's outlook, the industrial oxygen market will grow at a 7.9% CAGR through 2036, rising from USD 89.4 billion in 2026 to USD 191.3 billion. Gas producers are building air separation units beside the chemical, steel and chip plants that buy the gas. Air Liquide counted an investment backlog of EUR 6.0 billion across over 70 projects in July 2026, balanced between large industries and electronics.[1] Each unit will tie one plant to one supplier for years, moving more oxygen by pipeline at contracted prices.
A heat map of buyers puts chemical processing, at 35% share in 2026, and medical and healthcare, at 28%, in the hot zone, as both draw oxygen around the clock. Air Liquide reported 4.2% comparable growth in Healthcare sales for the first half of 2026, with home healthcare patient numbers rising in Europe.[1] Metallurgy and metal fabrication, an estimated 17.5%, runs warm and follows furnace campaigns. Automotive and aerospace shops, near 6.2%, stay cool, as cutting and welding lines buy cylinders in small lots. Suppliers will site new storage tanks beside hospital clusters and chemical parks first, serving cool buyers from shared cylinder depots.
Key Market Trends & Insights
- Liquefied oxygen, trucked from central plants to hospital tanks and merchant users, is expected to lead product type sales with 57% share in 2026, and compressed oxygen gas will hold 43%. Air Liquide grew Industrial Merchant sales 3.2% in the first half of 2026 on a 4.2% price effect.[1]
- Within end use, chemical processing is projected to keep the largest portion at 35% in 2026, as oxidation and gasification units run on pipeline oxygen. Hospitals and home care providers follow at 28%.
Regional Highlights
- Coal gasification and steel projects are adding cryogenic plants in India, which is projected to grow fastest at 8.8% in FMI's estimate, against a 7.9% global CAGR.
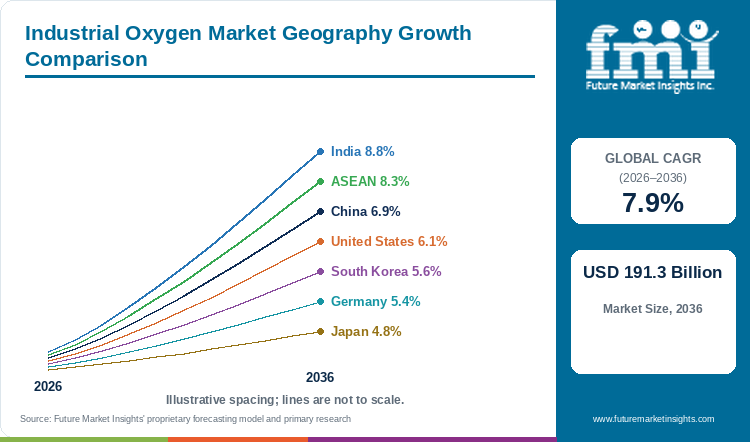
- ASEAN follows at 8.3% on new merchant liquid plants in Malaysia. Among the larger markets, China leads on 6.9%, with the United States next on 6.1%. Rates of 5.6% in South Korea and 5.4% in Germany are close together, and Japan comes last on 4.8%.
- Crude steel output in India rose 4.6% to 14.8 million tonnes in August 2026, worldsteel data show.[2]
Market Size & Forecast
Table 1: Market Size and Forecast for the Industrial Oxygen Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 82.9 billion |
| Estimated Market Size in 2026 | USD 89.4 billion |
| Projected Market Size by 2036 | USD 191.3 billion |
| CAGR, 2026 to 2036 | 7.9% |
| Added Revenue, 2026 to 2036 | USD 101.9 billion |
| Market Expansion Multiple | 2.1x |
Demand for industrial oxygen reaches buyers through three routes, and each route runs to a different clock. Pipeline and on-site volume starts the day a new air separation unit is commissioned, bulk liquid follows hospital and merchant tank fills, and cylinder volume follows workshop activity. Linde reported second-quarter 2026 sales of USD 9,289 million, up 9%, with volumes up 2% mainly in electronics, manufacturing and chemicals and energy.[3] For the June quarter, Air Products put sales at USD 3,161.0 million on 3% higher volumes.[4] Stainless mills blow oxygen through argon oxygen decarburisation converters, and the stainless steel market is forecast to expand at a 5.4% CAGR, so mill orders will add steady tonnage. FMI estimates an added USD 101.9 billion of industrial oxygen sales by 2036, leaving the industrial oxygen market at 2.1 times the 2026 figure. Lower manufacturing volumes in Linde's EMEA region are the main near-term risk for merchant sales.[3]
On-Site Contracts, Chip Fabs and Merchant Liquid
Chip plants are the quickest-growing buyers at Air Liquide, as Electronics sales rose 6.2% in the first half of 2026, ahead of every other business line. Electronics investment decisions above EUR 1 billion were approved in the same half, including EUR 200 million for two units in Hiroshima.[1] A new long-term electronics supply contract in the United States brought the sale of gas backlog at Linde to USD 8.1 billion.[3] Chip makers buy wet chemicals and specialty gases alongside bulk gas, and the semiconductor process chemicals market is forecast to grow at an 11.8% CAGR, which keeps new fabs ordering cold boxes. Fab units produce nitrogen first, and the oxygen from the same cold box will go into local merchant tanks.
Merchant liquid is growing through new plants in Southeast Asia. Air Products agreed to build an LNG-based air separation unit at the Pengerang terminal in Johor for a PETRONAS Gas-led joint venture, producing over 600 tonnes of liquid oxygen, nitrogen and argon a day from early 2027.[5] NovaAir, the Malaysian subsidiary of Yingde Gases, commissioned a 300-tonnes-per-day liquid plant in Greater Kuala Lumpur in August 2026.[6] Two new liquid sources in one country will give Malaysian electronics plants and hospitals more suppliers to bid against each other.
Table 2: Producer, Steel and Plant Indicators for the Industrial Oxygen Market (sales, backlog and capacity), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Linde sales, Q2 2026 | USD 9,289 million; up 9% | Scale of contracted and merchant gas | [3] |
| Linde sale of gas backlog, Q2 2026 | USD 8.1 billion | On-site volume still to start | [3] |
| Air Liquide investment backlog, H1 2026 | EUR 6.0 billion; over 70 projects | Plants due to begin supply | [1] |
| Air Liquide Healthcare sales, H1 2026 | EUR 2,244 million; up 4.2% comparable | Medical oxygen demand | [1] |
| Air Products sales, fiscal Q3 2026 | USD 3,161.0 million; volumes up 3% | Volume trend by region | [4] |
| Global crude steel output, August 2026 | 144.2 million tonnes; down 1.2% | Oxygen use in steelmaking | [2] |
| Air Products Johor unit | Over 600 tonnes a day from early 2027 | New merchant liquid in ASEAN | [5] |
Analyst Perspective
“I expect hospitals and chip plants to reward oxygen suppliers most over the next decade, as both pay for reliability and sign long terms. My advice to producers is to place liquid storage close to hospital clusters and pair that storage with on-site units at new fabs, as that mix will give the steadiest margins in industrial oxygen.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the industrial oxygen market segmented?
The market is segmented into product type, end use, and region. Liquefied oxygen will lead product type at 57% in 2026, and chemical processing is likely to lead end use at 35%.
By product type: compressed oxygen gas and liquefied oxygen.
By end use: chemical processing, medical and healthcare, metallurgy and metal fabrication, energy, automotive and aerospace, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does liquefied oxygen lead industrial oxygen sales by product type?
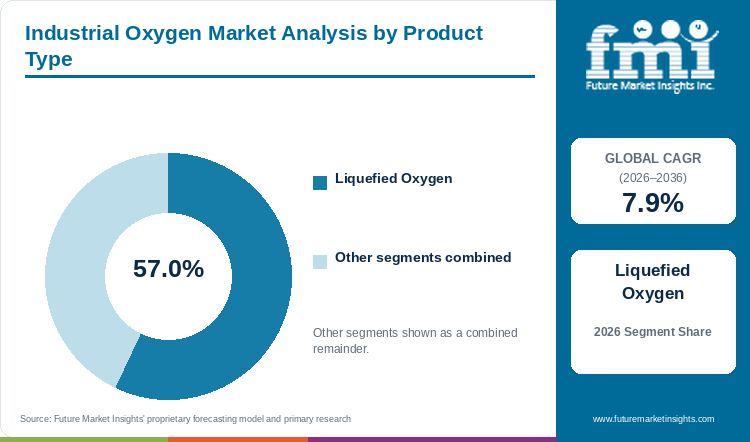
In 2026, liquefied oxygen is estimated to hold the product type lead at 57%, against 43% for compressed oxygen gas.
Table 3: Product Type Share for the Industrial Oxygen Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Liquefied Oxygen | 57% |
| Compressed Oxygen Gas | 43% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Industrial Oxygen Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.9% |
| Leading Segment | Liquefied Oxygen |
A single tanker delivery of liquid replaces a large stock of cylinders, so hospitals, food plants and mid-sized mills keep a vacuum-insulated tank on site and draw gas through a vaporiser. Liquefied oxygen will lead product type with 57% share in 2026 on the strength of that bulk model. Compressed oxygen gas, at 43%, stays the choice for welding shops, clinics and remote sites using too little gas to justify a tank, and for buyers needing portable supply. Price is moving in favour of producers on both formats, as Air Liquide reported a 4.2% price effect in Industrial Merchant over the first half of 2026.[1] Buyers growing past a few cylinders a day will switch to bulk liquid, and cylinder sales will hold in workshops and home care.
- Bulk tanks at hospitals, food plants and glass furnaces make up the core of liquid oxygen deliveries.
- NovaAir commissioned a 300-tonnes-per-day liquid air separation unit in Greater Kuala Lumpur in August 2026, Bernama reported.[6]
Why does chemical processing lead industrial oxygen sales by end use?
Chemical processing is projected to lead end use with 35% share in 2026, ahead of medical and healthcare at 28% and metallurgy and metal fabrication at an estimated 17.5%.
Table 5: End Use Share for the Industrial Oxygen Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Chemical Processing | 35% |
| Medical and Healthcare | 28% |
| Metallurgy and Metal Fabrication | 17.5% |
| Energy | 8.4% |
| Automotive and Aerospace | 6.2% |
| Others | 4.9% |
| Total | 100.0% |
Ethylene oxide, titanium dioxide and gasification plants consume oxygen by the tonne every hour, so chemical processing is projected to lead end use with 35% share in 2026. Air Liquide committed over USD 200 million to a new partial oxidation unit at the Oxea site in Bay City, Texas, due to start in 2029.[1] Medical and healthcare, at 28%, buys smaller volumes per site, spread over many hospitals and home patients, and the oxygen therapy equipment market is likely to rise at a 6.9% CAGR as concentrators and home cylinders reach more patients. Metallurgy and metal fabrication, an estimated 17.5%, follows furnace campaigns, and global crude steel output fell 1.2% in August 2026.[2] Energy, near 8.4%, covers oxy-fuel combustion and gasification for power, a niche outside a few large projects. Automotive and aerospace users, an estimated 6.2%, cut and weld with cylinder oxygen, and pulp, water treatment and food processing make up the remaining 4.9%. Chemical complexes will keep the largest contracts, as one plant can absorb the full output of a dedicated unit.
- Ethylene oxide, gasification, titanium dioxide and refinery units draw most chemical oxygen.
- Ellenbarrie Industrial Gases secured a Rs 481 crore BHEL contract for a 1,200 TPD cryogenic unit at a coal-to-ammonium nitrate project in Odisha, Indian Chemical News reported on 29 September 2026.[7]
What are the drivers, restraints, and opportunities in the industrial oxygen market?
Long supply contracts with chemical plants and hospitals keep demand for industrial oxygen steady. Power costs at air separation plants and weak European manufacturing squeeze margins, and new chip fabs and gasification projects open fresh volume.
- Driver: Chemical and gasification units run around the clock on contracted oxygen, so every new project adds a fixed base of demand for industrial oxygen.
- Restraint: Electricity is the main cost of separating air, and producers on fixed-price contracts carry the gap when power prices rise faster than contract escalators.
- Opportunity: Chip fabs and home respiratory care both pay for supply security, which rewards producers able to build on-site units and run patient services.
Contracted Volume From Chemical and Steel Plants
Adoption of on-site oxygen follows the capital plans of large chemical and steel buyers, since a dedicated unit is built only against a signed offtake. Air Liquide agreed to invest over USD 350 million in an air separation unit for the Hyundai-Posco low-carbon steel plant in Louisiana.[1] Ellenbarrie will deliver a 1,200 TPD unit for a coal gasification project in Odisha over eight quarters.[7] Each signed offtake converts into oxygen volume in the year the unit starts, which gives producers visibility well beyond 2030.
Power Costs and Soft European Industry
Key challenges in the industrial oxygen market include electricity costs and weak factory output in Europe. Air Products reported a 2% fall in European volumes in the June quarter, offset by energy pass-through and pricing.[4] Linde's EMEA volumes were lower, mainly in manufacturing.[3] FMI expects European merchant producers to rely on price and energy pass-through clauses until factory output recovers.
Chip Fabs and Home Care Open New Volume
Growth of the industrial oxygen market will come partly from buyer groups that were small a decade ago. Air Liquide approved EUR 200 million for two units serving AI chip production in Hiroshima and nearly EUR 200 million for a nitrogen unit for SK hynix in South Korea.[1] Air Products San Fu signed a long-term agreement to build four large air separation units for a semiconductor manufacturer in Taiwan.[4] Each fab unit also yields oxygen for merchant sale, opening a new supply corridor for merchant liquid in chip clusters.
Which country CAGRs are profiled in the industrial oxygen market?
Table 6: Country CAGR Comparison for the Industrial Oxygen Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 8.8% |
| ASEAN | 8.3% |
| China | 6.9% |
| United States | 6.1% |
| South Korea | 5.6% |
| Germany | 5.4% |
| Japan | 4.8% |
How do country-level CAGRs compare in the industrial oxygen market?
Coal gasification and steel projects in Odisha are adding cryogenic plants, and Ellenbarrie's 1,200 TPD unit for Jharsuguda is due for commissioning in FY29.[7] FMI places India first at 8.8%, 0.9 points over the global 7.9%. ASEAN comes next at 8.3% as new liquid plants open in Malaysia. China, at 6.9%, faces lower steel output, and the United States, at 6.1%, grows on chip and chemical contracts. South Korea and Germany are close together at 5.6% and 5.4%. Flat steel output leaves Japan at 4.8%, the slowest pace among the seven.
- Gasification and steel projects in eastern states are adding air separation capacity in India.
- Merchant liquid plants in Johor and Greater Kuala Lumpur widen supply across ASEAN.
- Lower crude steel output slows oxygen orders from mills in China.
- Chip fabs and Gulf Coast chemical pipelines carry growth in the United States.
- Memory fab expansions add on-site gas plants in South Korea.
- Copper recycling and steel furnaces keep oxygen orders steady in Germany.
- AI chip plants are the main new oxygen buyers in Japan, with steel flat.
Full report country CAGRs cover: India and ASEAN above the global rate on new gasification and merchant plants, China and the United States at the head of the mature group, South Korea, Germany and Japan under six percent, and each remaining standard country grouped by region.
Country-wise Analysis
India Industrial Oxygen Market Outlook (2026 to 2036)
Odisha is the focus of new oxygen capacity in India. Ellenbarrie Industrial Gases secured a Rs 481 crore turnkey contract from BHEL for a 1,200 TPD cryogenic unit at a coal-to-ammonium nitrate project in Jharsuguda district, with commissioning expected in FY29.[7] Crude steel output in India rose 4.6% in August 2026 to 14.8 million tonnes.[2] In FMI's estimate, India will grow at an 8.8% CAGR, the top profiled rate.
Key takeaway: Gasification and steel orders put India at the front of new oxygen capacity.
ASEAN Industrial Oxygen Market Outlook (2026 to 2036)
Malaysia is adding two new sources of merchant liquid. Air Products will run an LNG-based unit at Pengerang from early 2027, using cold energy from regasification, for electronics, petrochemical, aerospace and manufacturing customers in Southern and Central Malaysia.[5] NovaAir commissioned a 300 tpd plant in August 2026.[6] Across ASEAN, demand for industrial oxygen will grow at an 8.3% CAGR, with electronics and petrochemical plants buying more liquid.
Key takeaway: New liquid capacity in Malaysia drives growth across ASEAN.
China Industrial Oxygen Market Outlook (2026 to 2036)
Steel mills are the heaviest oxygen users in China, and crude steel output there fell 3.7% to 74.6 million tonnes in August 2026.[2] Chemical parks and chip plants keep adding on-site units, so FMI estimates a 6.9% CAGR for China, below the 7.9% CAGR expected for the industrial oxygen market.
Key takeaway: Chemical and chip projects offset weaker steel in China.
United States Industrial Oxygen Market Outlook (2026 to 2036)
Gulf Coast pipelines and new fabs drive the United States. Air Products reported a 7% volume rise in the Americas in the June quarter, helped by HyCO volumes and a new on-site asset.[4] Large Industries sales at Air Liquide grew 7% in the Americas in the first half of 2026 on unit start-ups and pipeline demand.[1] A 6.1% CAGR is expected for the United States over the decade.
Key takeaway: Pipeline and fab contracts keep the United States at the head of the mature group.
South Korea Industrial Oxygen Market Outlook (2026 to 2036)
Air Liquide completed the acquisition of DIG Airgas for about EUR 3 billion in mid-January 2026, roughly doubling the group's workforce in South Korea.[1] Crude steel output in South Korea rose 2.6% in August 2026.[2] Memory fab growth and the large steelworks are expected to hold South Korea at a 5.6% CAGR.
Key takeaway: A bigger producer base and memory fabs support South Korea.
Germany Industrial Oxygen Market Outlook (2026 to 2036)
Messer opened an air separation plant at the Aurubis recycling site in Lünen that produces up to 210 tons of oxygen a day for copper production furnaces, Indian Chemical News reported in February 2026.[8] German crude steel output reached 2.6 million tonnes in August 2026, up 1.7%.[2] A 5.4% CAGR is forecast for Germany, as metal recycling and steel projects add on-site units against weak general manufacturing.
Key takeaway: Metal recycling gives Germany new on-site oxygen demand.
Japan Industrial Oxygen Market Outlook (2026 to 2036)
Japan closes the country table on 4.8%. Steel output in Japan rose only 0.4% in August 2026.[2] New AI chip plants in Hiroshima, backed by a EUR 200 million Air Liquide investment in two units, give oxygen producers a growth pocket outside steel.[1]
Key takeaway: Chip plants offset flat steel in Japan.
Who are the notable companies in the industrial oxygen market?
Linde, Air Liquide, Air Products, Matheson Tri-Gas, Messer, SOL, Air Water, Gulf Cryo and Ellenbarrie Industrial Gases are the profiled companies.
Oxygen buyers choose from three global producers with on-site, bulk and cylinder networks, a group of regional producers and Indian plant builders. Linde reported APAC sales of USD 1,870 million in the June quarter, up 13% on 6% higher volumes and project start-ups.[3] Gas & Services revenue at Air Liquide was EUR 13,408 million for the first half of 2026.[1] New on-site assets and better helium volumes raised Air Products sales in Asia 9% to USD 886.0 million.[4] Oxygen is the largest single product for these producers, and the industrial gases market will grow at a 7.8% CAGR, close to the FMI view of 7.9% for industrial oxygen.
- Global producers: Linde, Air Liquide and Air Products.
- Regional and national producers: Matheson Tri-Gas, Messer, SOL, Air Water and Gulf Cryo.
- Indian supplier and plant builder: Ellenbarrie Industrial Gases.
Competitive Benchmarking: Industrial Oxygen Market
Table 7: Competitive Benchmarking for the Industrial Oxygen Market (qualitative documentation ratings), 2026
| Company | On-site and Pipeline | Bulk Liquid | Healthcare | Recency |
|---|---|---|---|---|
| Linde | High | High | Medium | High |
| Air Liquide | High | High | High | High |
| Air Products | High | Medium | Low | High |
| Messer | Medium | Medium | Low | Medium |
| Ellenbarrie Industrial Gases | Medium | Medium | Low | High |
Ratings summarise the dated 2026 evidence each company has released for every column and imply no ranking by sales.
Key Developments in the Industrial Oxygen Market
- On 13 October 2026, NovaAir said the 300 tpd liquid air separation unit near Kuala Lumpur had been commissioned in August.[6]
- 9 October 2026: Air Products agreed to build and operate an LNG-based air separation unit in Johor for a PETRONAS Gas-led joint venture.[5]
- On 29 September 2026, Ellenbarrie Industrial Gases secured a Rs 481 crore BHEL order for a 1,200 TPD cryogenic unit.[7]
- On 24 September 2026, worldsteel reported global crude steel output of 144.2 million tonnes for August 2026.[2]
- The 31 July 2026 results from Linde put the sale of gas backlog at USD 8.1 billion after a new US electronics contract.[3]
- On 30 July 2026, Air Products reported a long-term agreement in Taiwan for four large air separation units at a semiconductor expansion.[4]
- Electronics sales at Air Liquide grew 9.5% in the second quarter, the group said on 28 July 2026.[1]
- In February 2026, Messer commissioned an oxygen and nitrogen plant at the Aurubis site in Lünen.[8]
Key Players in the Industrial Oxygen Market
Global Producers
- Linde
- Air Liquide
- Air Products
Regional and National Producers
- Matheson Tri-Gas
- Messer
- SOL
- Air Water
- Gulf Cryo
Indian Supplier and Plant Builder
- Ellenbarrie Industrial Gases
Industrial Oxygen Market - Report Scope
Table 8: Report Scope for the Industrial Oxygen Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; end use; region |
| Quantitative units | USD billion |
| Market definition | Oxygen produced by air separation and sold as compressed gas in cylinders, as liquid in bulk tanks, or by pipeline and on-site plants, for chemical, medical, metal, energy, transport and other industrial uses. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Linde, Air Liquide, Air Products, Matheson Tri-Gas, Messer, SOL, Air Water, Gulf Cryo, Ellenbarrie Industrial Gases |
| Forecast period | 2026 to 2036 |
Industrial Oxygen Market - Research Methodology
Table 9: Research Methodology for the Industrial Oxygen Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Industrial gas producer results, steel output releases and trade press on air separation plants, dated February 2026 onward. |
| Desk Research | Desk research covers on-site contracts, merchant liquid, hospital oxygen, steel and chemical plant activity. |
| Market Sizing and Forecasting | The forecast builds from the USD 89.4 billion estimate for 2026 and a 7.9% CAGR to 2036. |
| Data Validation | Sales, backlog and capacity figures were matched to the company release or article carrying them. |
Industrial Oxygen Market by Segments
Industrial Oxygen Market segmented by Product Type:
- Compressed Oxygen Gas
- Liquefied Oxygen
Industrial Oxygen Market segmented by End Use:
- Chemical Processing
- Medical and Healthcare
- Metallurgy and Metal Fabrication
- Energy
- Automotive and Aerospace
- Others
Industrial Oxygen Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Air Liquide. (2026, July 28). H1 2026 results: acceleration in the second quarter, Air Liquide combines growth and continuous performance improvement. https://www.airliquide.com/sites/airliquide.com/files/2026-07/h1-2026-results-acceleration-second-quarter-air-liquide-combines-growth-continuous-performance_6a683bddd0a4b.pdf
- [2] World Steel Association. (2026, September 24). August 2026 crude steel production. https://worldsteel.org/media/press-releases/2026/august-2026-crude-steel-production/
- [3] Linde plc. (2026, July 31). Linde Reports Second-Quarter 2026 Results (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0001707925/000165495426007052/lin_ex991.htm
- [4] Air Products and Chemicals, Inc. (2026, July 30). Air Products Reports Fiscal Third Quarter 2026 Results (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000002969/000000296926000034/exhibit99130jun26.htm
- [5] Indian Chemical News. (2026, October 9). Air Products to build LNG-based air separation plant in Johor targeting early 2027 start. https://www.indianchemicalnews.com/gas/lite/air-products-to-build-lng-based-air-separation-plant-in-johor-targeting-early-2027-start-32209
- [6] Bernama. (2026, October 13). NovaAir deepens long-term investment footprint in Malaysia with inauguration of KUL air separation unit. https://bernama.com/en/press/news.php?id=2619688
- [7] Indian Chemical News. (2026, September 29). Ellenbarrie bags Rs. 481-crore BHEL contract for major Odisha air separation unit. https://www.indianchemicalnews.com/gas/ellenbarrie-bags-rs-481-crore-bhel-contract-for-major-odisha-air-separation-unit-32080
- [8] Indian Chemical News. (2026, February 25). Messer commissions air separation plant in Germany. https://www.indianchemicalnews.com/gas/lite/messer-commissions-air-separation-plant-in-germany-29477
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the industrial oxygen market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which end use holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the industrial oxygen market expected in 2026?
The industrial oxygen market is expected to reach USD 89.4 billion in 2026, up from USD 82.9 billion in 2025, on FMI's numbers. Sales of industrial oxygen are projected to reach USD 191.3 billion by 2036.
What CAGR is projected for the industrial oxygen market through 2036?
A 7.9% CAGR from 2026 to 2036 is projected for the industrial oxygen market. Long on-site contracts with chemical plants, chip fabs and hospitals carry that growth.
Which product type holds a notable market share in 2026?
Liquefied oxygen is expected to lead with 57% share in 2026. Compressed oxygen gas holds 43%.
Which end use holds a notable market share in 2026?
Chemical processing is projected to lead with 35% share. Medical and healthcare follows at 28%.
Which country has a notable expansion outlook through 2036?
India has the fastest FMI country forecast, an 8.8% CAGR. ASEAN follows at 8.3%.
Who are the key companies in the industrial oxygen market?
Linde, Air Liquide and Air Products are the global producers. Matheson Tri-Gas, Messer, SOL, Air Water, Gulf Cryo and Ellenbarrie Industrial Gases complete the profiled group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Compressed Oxygen Gas
- Liquefied Oxygen
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Chemical Processing
- Medical and Healthcare
- Metallurgy and Metal Fabrication
- Energy
- Automotive and Aerospace
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Linde
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Air Liquide
- Air Products
- Messer
- Ellenbarrie Industrial Gases
- Matheson Tri-Gas
- SOL
- Air Water
- Gulf Cryo
- Linde
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


