

- Market Size (2026)
- USD 51.5 Bn
- Forecast (2036)
- USD 79.2 Bn
- CAGR (2026 to 2036)
- 4.4%
How big is Low Density Polyethylene Market in 2026?
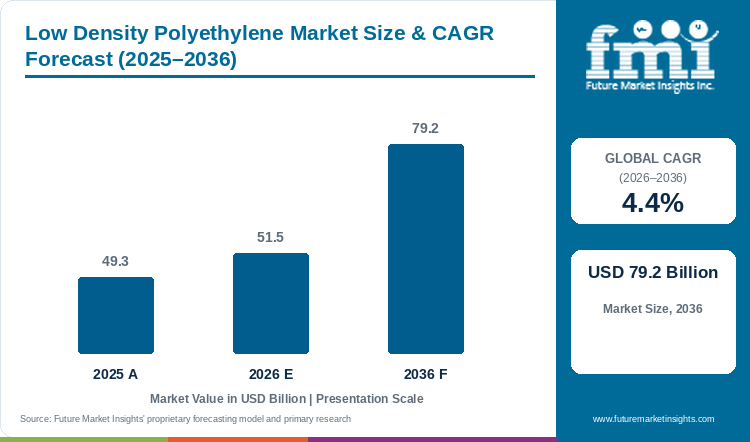
The low density polyethylene market is estimated at USD 49.3 billion in 2025 and is forecast to reach USD 51.5 billion in 2026. Demand for low density polyethylene is projected to grow at a CAGR of 4.4% and reach USD 79.2 billion by 2036.
Demand for low density polyethylene is growing with flexible packaging, as food brands and retailers move more products into sealed film packs. FMI estimates the low density polyethylene market at USD 49.3 billion in 2025 and expects USD 51.5 billion in 2026, rising to USD 79.2 billion by 2036 at a 4.4% CAGR. Against that path, resin prices moved sharply in 2026. For instance, Dow reported a 30% rise in local prices for Packaging and Specialty Plastics in the June 2026 quarter, with higher polyethylene prices in every region and the largest gains in flexible packaging, and volume fell 4%.[1] As a result, converters paid more per tonne and ordered closer to need, which kept resin stocks thin across the chain.
Film converters buy the most resin and buy most often, as film and sheets are likely to make up 67.6% of 2026 sales and food, shrink and agricultural film lines draw resin every day. By comparison, extrusion coaters, near 14.3%, place fewer but larger contracts for liquid cartons and paper cups. Injection moulders, about 10.8%, are the least committed buyers and switch to other polyethylene grades when prices move. For producers, therefore, large film accounts justify dedicated tubular capacity, and carton and cup coaters are building a second pull for autoclave coating grades.
Key Market Trends & Insights
- Tubular reactors are likely to supply 62.6% of 2026 sales by technology, with autoclave units at an estimated 37.4%, as new single-line capacity favours the tubular process.
- Film and sheets are expected to hold 67.6% of application sales in 2026 on food, shrink and agricultural film. Converters absorbed higher resin prices through the year. On pricing, Dow said polyethylene prices rose most in flexible packaging in the June 2026 quarter.[1] Price gains led by flexible packaging show film demand holding even at higher cost.
Regional Highlights
- India is forecast in FMI's outlook to grow at 6.5%, against a 4.4% global CAGR, on packaged food and retail film.
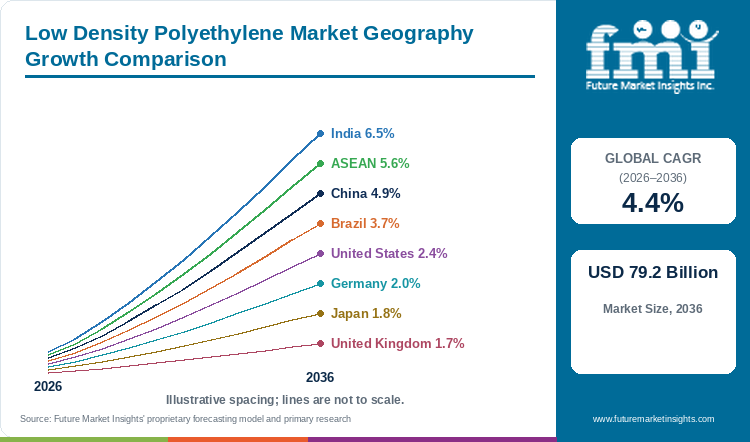
- ASEAN converters grow at 5.6% and Chinese film lines at 4.9%. Below these, Brazil (3.7%), the United States (2.4%) and Germany (2%) form the middle group. Japan (1.8%) and the United Kingdom (1.7%) grow slowest on mature packaging bases.
- Import pressure is the main weakness for regional producers in Latin America. Braskem said polyethylene sales in Brazil fell 9% in Q2 2026 against Q2 2025, as imports gained volume.[2] Lower local sales mean Brazilian converters are buying more imported resin, which caps producer pricing in the region.
Market Size & Forecast
Table 1: Market Size and Forecast for the Low Density Polyethylene Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 49.3 billion |
| Estimated Market Size in 2026 | USD 51.5 billion |
| Projected Market Size by 2036 | USD 79.2 billion |
| CAGR, 2026 to 2036 | 4.4% |
| Added Revenue, 2026 to 2036 | USD 27.7 billion |
| Market Expansion Multiple | 1.5x |
Sales of low density polyethylene swung with supply in 2026, as Gulf outages pushed buyers toward North American producers. For example, LyondellBasell ran North American olefins and polyolefins assets at about 90% in Q2 2026 to serve customers during the supply disruption.[3] Run rates that high show exporters in North America filling the gap left by Gulf supply. By comparison, all plastics together are projected to grow faster, as the plastic market carries a 6.5% CAGR led by engineering and recycled resins. FMI projects the low density polyethylene market to add roughly USD 27.7 billion over ten years, a 1.5x multiple on 2026. However, a slow return of Middle East supply, which LyondellBasell expects to extend into 2027, is the main pricing risk.[3] A longer outage would keep resin prices high and push converters toward thinner film.
Supply Disruption, Spreads and European Closures
Middle East supply losses widened polymer spreads in 2026. For instance, Braskem put the US polyethylene spread at USD 866 per tonne in Q2 2026, up 101% from Q1, and the Mexico spread at USD 1,425 per tonne.[2] Wider spreads raised producer margins in the Americas at the expense of converters. In the Gulf, SABIC reported a USD 100 million net loss for the quarter, linked to the regional conflict, and moved more polymer volume from eastern to western Saudi Arabia.[4] As a result, Asian converters faced the tightest supply, as Gulf exports were rerouted.
European capacity is shrinking at the same time. A case in point is LyondellBasell, which completed the sale of four European olefins and polyolefins assets in May 2026 and guided European operating rates to 70% for Q3.[3] A 70% rate leaves little spare European output for film converters. Likewise, Dow plans to shut the ethylene cracker at Böhlen in Germany in the fourth quarter of 2027.[5] Consequently, film converters in Europe will rely more on imported resin through 2036.
Table 2: Price, Supply and Policy Indicators for the Low Density Polyethylene Market (price, volume and capacity), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Dow Packaging and Specialty Plastics, Q2 2026 | Local price up 30%; volume down 4% | Polyethylene pricing | [1] |
| LyondellBasell North American O&P utilization, Q2 2026 | About 90% | US supply response | [3] |
| Braskem US polyethylene spread, Q2 2026 | USD 866 per tonne; up 101% from Q1 | Margin for resin producers | [2] |
| SABIC Q2 2026 result | USD 100 million net loss | Gulf export disruption | [4] |
| Dow Böhlen cracker | Shutdown expected in 4Q27 | European ethylene supply | [5] |
| EU packaging regulation | Generally applicable from 12 August 2026 | Recyclable film design | [6] |
Analyst Perspective
“Low density polyethylene will keep the lead in clear and sealable film for food and medical packs, and I see film recyclability rules in Europe rewarding mono-material polyethylene structures. Producers with tubular capacity close to film converters and a credible low-carbon grade will hold the best contracts. Autoclave lines will stay valuable for extrusion coating and specialty copolymers, and few new autoclave plants are being built.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the low density polyethylene market segmented?
The market is segmented into technology, application, and region. Tubular reactors are likely to lead technology with 62.6% in 2026, and film and sheets are expected to lead application with 67.6%.
By technology: tubular, and autoclave.
By application: film and sheets, extrusion coating, injection moulding, and others.
By region: resin producers, compounders and converters in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does tubular technology lead low density polyethylene sales?
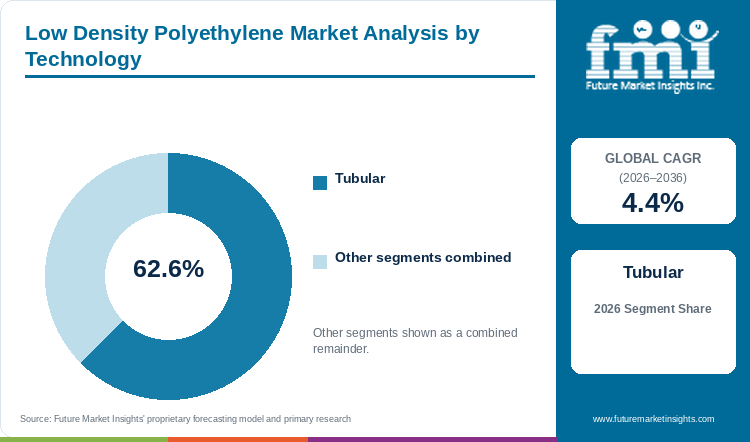
Tubular reactors are likely to lead technology with 62.6% share in 2026, against an estimated 37.4% for autoclave reactors.
Table 3: Technology Share for the Low Density Polyethylene Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| Tubular | 62.6% |
| Autoclave | 37.4% |
| Total | 100.0% |
Table 4: Technology Leadership and Market Growth for the Low Density Polyethylene Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.4% |
| Leading Segment | Tubular |
Tubular reactors run single lines of several hundred thousand tonnes and give the low cost per tonne and clarity that film converters want, so tubular technology is projected to lead with 62.6% in 2026. By contrast, autoclave reactors, about 37.4%, produce a broader molecular weight spread that suits extrusion coating and vinyl acetate copolymers, and few new autoclave lines are under construction. At the same time, linear grades compete for the same film lines, and strength and down-gauging give the linear low density polyethylene market an expected 6% CAGR. Blends of both resins keep tubular output in demand for clarity and sealing. Short-term volumes are less steady than the long-run shift. Even so, Dow reported lower polyethylene volume in Asia Pacific in Q2 2026, tied to the Middle East conflict.[1] Lost Asian volume in 2026 reflects supply routing more than weaker film demand, so film-grade sales should recover once Gulf exports return. Over the forecast period, tubular lines will gain share as older autoclave units close in Europe.
- Large single-train tubular plants in the United States, the Middle East and Asia make most film-grade resin.
- Higher-value medical grades are a growing use of the purest resin. Braskem presented Medcol V7040, a low density polyethylene grade for blow-fill-seal pharmaceutical packs, at interpack 2026.[7] Pharmaceutical packs pay a premium for clean, consistent resin, which rewards producers with tight reactor control.
Why do film and sheets lead low density polyethylene sales by application?
Film and sheets are expected to lead application with 67.6% share in 2026, ahead of extrusion coating at about 14.3% and injection moulding at an estimated 10.8%.
Table 5: Application Share for the Low Density Polyethylene Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Film and Sheets | 67.6% |
| Extrusion Coating | 14.3% |
| Injection Moulding | 10.8% |
| Others | 7.3% |
| Total | 100.0% |
Bread bags, shrink sleeves, frozen food packs and greenhouse covers all need soft, clear and sealable film, so film and sheets will lead with 67.6% in 2026. Among end uses, packaged food remains the largest outlet, with 5.3% CAGR growth forecast for the food packaging market. At a likely 4.6% CAGR, the flexible plastic packaging market is the main volume outlet for film-grade resin. Next, extrusion coating, about 14.3%, puts a thin sealing layer on liquid cartons and paper cups. Injection moulding holds an estimated 10.8% for caps, lids and housewares, and others, near 7.3%, include wire and cable insulation and blow-moulded containers. Brand owners are also redesigning film around carbon targets. On the brand side, Dow and Amcor agreed in September 2026 to work on low carbon polyethylene packaging for brands and retailers.[8] Film will therefore keep the lead as brands redesign packs around mono-material polyethylene.
- Food packaging, shrink and stretch film, carrier bags and agricultural film form the film and sheets group.
- Recyclability rules in Europe now favour simpler film structures. The EU packaging regulation became generally applicable on 12 August 2026, with an aim for all packaging to be recyclable in an economically viable way by 2030.[6] Mono-material polyethylene packs meet that aim more easily than mixed laminates, which supports film-grade demand in Europe.
What are the drivers, restraints, and opportunities in the low density polyethylene market?
Food and retail packaging keep film converters buying resin. Volatile ethylene supply and European plant closures raise price risk, and low-carbon and bio-based grades open premium contracts with brand owners.
- Driver: Packaged food, chilled distribution and online retail all need sealable, puncture-resistant film, and each new pack format adds steady resin orders.
- Restraint: Ethylene supply outages and cracker closures move resin prices quickly, so converters cut inventories and delay new film projects.
- Opportunity: Brand owners setting carbon targets want lower-footprint and bio-based polyethylene, which supports premium film and medical grades.
Packaging Formats Keep Film Lines Busy
Adoption of flexible packs keeps film converters buying resin through price cycles. Evidence of this comes from Dow, which said flexible packaging showed the strongest polyethylene price gains in Q2 2026, a sign of firm demand from converters.[1] In turn, converters will keep low density polyethylene in sealing and clarity layers even as linear grades take more of the structure.
Supply Outages and Closures Raise Price Risk
Producers of low density polyethylene face swings in feedstock and freight. For instance, LyondellBasell said recovery of conflict-affected supply is likely to extend into 2027, with near-term price uncertainty affecting normal buying patterns.[3] In FMI's estimate, converters in Europe and Asia carry the most exposure. In response, buyers will add second suppliers and shorter price review periods.
Low-Carbon and Bio-Based Grades Open Premium Contracts
Demand for lower-footprint resin is growing among brand owners. For example, Braskem sold 39 kt of green polyethylene in Q2 2026, 49% more than in Q1.[2] Growth at that pace in a niche grade shows brand owners paying for bio-based content. Alongside this, the Dow and Amcor collaboration uses the Carbon Footprint Ledger to give customers assured product carbon footprints.[8] As a result, producers with certified low-carbon grades will secure multi-year supply with consumer goods companies.
Which country CAGRs are profiled in the low density polyethylene market?
Table 6: Country CAGR Comparison for the Low Density Polyethylene Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 6.5% |
| ASEAN | 5.6% |
| China | 4.9% |
| Brazil | 3.7% |
| United States | 2.4% |
| Germany | 2% |
| Japan | 1.8% |
| United Kingdom | 1.7% |
How do country-level CAGRs compare in the low density polyethylene market?
Country growth splits between import-fed emerging markets and mature producing countries. Braskem's Brazilian polyethylene sales fell 9% year on year in Q2 2026 as imported resin gained share, and FMI projects Brazil at 3.7%.[2] Import competition of that kind holds back local producers even as Brazilian film demand grows. At the top, packaged food and organised retail add film demand fastest in India, at 6.5%. ASEAN follows at 5.6% on export packaging and consumer goods plants, and China grows at 4.9% from a large converter base. Further back, growth in the United States is limited to 2.4% by mature film demand, under the overall 4.4% CAGR for low density polyethylene, despite low-cost ethane. Germany (2%) and Japan (1.8%) grow more slowly still, held back by cracker closures and flat pack volume. Finally, the United Kingdom grows slowest, at 1.7%, with imported resin and a mature pack market.
- Indian food brands are moving staples, dairy and snacks into sealed film packs as organised retail spreads to smaller cities, raising demand for clear sealing layers. Domestic producers and Gulf exporters compete for these converter accounts.
- Export-oriented converters in Thailand, Vietnam, Indonesia and Malaysia buy mostly Gulf resin, so ASEAN demand grows with consumer goods exports and stays exposed to Gulf supply routes.
- New domestic crackers are cutting Chinese reliance on imported resin, leaving less room for exporters selling into the large Chinese converter base.
- Imported resin is taking share from local supply in Brazil and holding down producer run rates. Converters gain from cheaper resin, and local producers face thinner margins.
- Low-cost ethane gives US crackers an export edge, though film demand at home is mature. US producers therefore grow mainly by selling into Latin America, Europe and Asia.
- Cracker closures and EU recyclability rules are moving German demand toward imported resin and mono-material film. For converters, recycled-content grades become a condition of new packaging contracts.
- With a mature packaging base and older crackers being consolidated, Japanese converters focus on high-barrier food and medical film, a smaller but higher-value outlet.
- Most UK film resin arrives from Europe and the Gulf, and the plastic packaging tax pushes recycled content into film, which squeezes demand for virgin grades.
Full report country CAGRs cover: all standard countries, with eight named rates, India and ASEAN marking the upper bound, the United Kingdom the lower, and the other standard countries reported by region.
Country-wise Analysis
India Low Density Polyethylene Market Outlook (2026 to 2036)
Packaged staples, dairy and snack brands are moving more products into sealed film packs, and organised retail chains are adding stores in smaller cities. To meet that demand, domestic producers and Gulf exporters both supply Indian converters. On that basis, India's forecast CAGR is 6.5%.
Key takeaway: Sealed food packs set the Indian pace.
ASEAN Low Density Polyethylene Market Outlook (2026 to 2036)
Converters in Thailand, Vietnam, Indonesia and Malaysia supply film to food processors and export brands, and much of the resin comes from Gulf producers. On the supply side, SABIC more than doubled polymer volumes moved from eastern to western Saudi Arabia in Q2 2026 to keep customers supplied.[4] With that supply in place, FMI analysis shows 5.6% for ASEAN.
Key takeaway: Gulf resin feeds ASEAN export packs.
China Low Density Polyethylene Market Outlook (2026 to 2036)
China has the largest film converter base in Asia, and new domestic crackers reduce reliance on imports. At the same time, Dow reported lower polyethylene volume in Asia Pacific in Q2 2026, tied to the Middle East conflict.[1] Lower Asian volume at a global producer leaves more of the Chinese market to domestic crackers. Accordingly, China is expected at 4.9%.
Key takeaway: New crackers support Chinese converters.
Brazil Low Density Polyethylene Market Outlook (2026 to 2036)
Brazilian producers are losing volume to imports. Braskem ran Brazilian crackers at 70% in Q2 2026, and overall resin sales fell 8% against Q2 2025 as imports grew.[2] Lower run rates hold back local supply, so converters lean on imported grades. Even so, food packaging and agricultural film keep demand for low density polyethylene in Brazil growing at a 3.7% CAGR.
Key takeaway: Imports squeeze Brazilian producers.
United States Low Density Polyethylene Market Outlook (2026 to 2036)
US producers are running hard to serve export demand. LyondellBasell guided North American olefins and polyolefins operating rates to 85% for Q3 2026, after about 90% in Q2.[3] Rates at that level show North American plants serving buyers cut off from Gulf resin. In addition, Dow and Amcor are working with brands on low carbon polyethylene packaging.[8] Low-carbon packaging gives US producers a premium outlet at home. With film demand mature, a 2.4% CAGR is projected for the United States.
Key takeaway: Mature film demand caps US growth.
Germany Low Density Polyethylene Market Outlook (2026 to 2036)
German resin supply is shrinking. Dow plans to close the Böhlen ethylene cracker in the fourth quarter of 2027, citing difficult market dynamics in Europe.[5] Closure of a domestic cracker moves German converters toward imported resin. German converters also face EU packaging rules that apply from 12 August 2026.[6] Recyclability targets favour mono-material film, which keeps low density polyethylene in use as the sealing layer. Consequently, Germany's projected CAGR is 2%.
Key takeaway: Closures and recyclability rules slow Germany.
Japan Low Density Polyethylene Market Outlook (2026 to 2036)
Japanese resin makers are consolidating older crackers, and converters focus on high-barrier food and medical film. In addition, population decline limits growth in packaged volume. FMI therefore expects only 1.8% annual growth in Japan.
Key takeaway: Consolidation slows Japan.
United Kingdom Low Density Polyethylene Market Outlook (2026 to 2036)
British converters import most resin from continental Europe and the Middle East, and the plastic packaging tax pushes recycled content into film. Under that pressure, growth in the UK is forecast at 1.7%.
Key takeaway: Imports and tax rules slow the UK.
Who are the notable companies in the low density polyethylene market?
LyondellBasell, ExxonMobil, Dow, SABIC, Qatar Petrochemical Company (QAPCO), BASF-YPC, LG Chem, Formosa Plastics and Braskem are the profiled companies.
In FMI analysis, integrated producers in North America, the Gulf, Asia and Latin America make up the field, with feedstock cost and port access separating them. Among them, Dow put Packaging and Specialty Plastics net sales at USD 6.4 billion for Q2 2026, up 27%.[1] Price-led growth of that size shows how much film demand absorbed in 2026. Next, LyondellBasell reported Q2 2026 sales of USD 9,177 million.[3] Scale of that kind supports exports from North America to resin-short regions. By comparison, SABIC reported revenue of USD 6.62 billion for the same quarter, down 5%.[4] Lower sales at SABIC reflect the supply losses in the Gulf. ExxonMobil, Qatar Petrochemical Company (QAPCO), BASF-YPC, LG Chem, Formosa Plastics and Braskem complete the field.
- US and European integrated producers: LyondellBasell, ExxonMobil and Dow.
- Gulf producers: SABIC and Qatar Petrochemical Company (QAPCO).
- Asian producers: BASF-YPC, LG Chem and Formosa Plastics.
- Latin American producers: Braskem.
Competitive Benchmarking: Low Density Polyethylene Market
Table 7: Competitive Benchmarking for the Low Density Polyethylene Market (qualitative ratings), 2026
| Company | Film Grades | Low-Carbon PE | Capacity Changes | Recent Activity |
|---|---|---|---|---|
| Dow | High | High | High | High |
| LyondellBasell | High | Low | High | High |
| SABIC | Medium | Low | Medium | High |
| Braskem | Medium | High | Medium | High |
| ExxonMobil | High | Low | Low | Low |
Ratings compare the companies on film grades, low-carbon PE, capacity changes and recent activity.
Key Developments in the Low Density Polyethylene Market
- Dow and Amcor announced a collaboration on low carbon polyethylene packaging on 17 September 2026, giving brand owners a route to lower-footprint film.[8]
- On 12 August 2026, the EU Packaging and Packaging Waste Regulation became generally applicable, which favours recyclable mono-material polyethylene packs.[6]
- LyondellBasell confirmed on 31 July 2026 that four European olefins and polyolefins sites changed hands in May; European converters now buy from fewer long-standing producers.[3]
- The regional conflict pushed SABIC to a USD 100 million second-quarter loss, according to a 30 July 2026 report, tightening polymer exports to Asia.[4]
- In the sales report of 30 July 2026, Braskem reported Brazilian polyethylene sales 9% below the year-earlier quarter, a sign of import pressure on local producers.[2]
- Higher polyethylene prices drove a 27% gain in Dow Packaging and Specialty Plastics sales, to USD 6.4 billion, in results of 23 July 2026; for converters this means higher resin costs.[1]
- Ahead of interpack, Braskem announced the Medcol V7040 low density polyethylene grade for blow-fill-seal packs on 28 April 2026, widening the medical outlet for the resin.[7]
- Dow announced plans on 7 July 2025 to shut the Böhlen ethylene cracker in Germany by 4Q27, which will reduce domestic ethylene supply for German resin.[5]
Key Players in the Low Density Polyethylene Market
US and European Integrated Producers
- LyondellBasell
- ExxonMobil
- Dow
Gulf Producers
- SABIC
- Qatar Petrochemical Company (QAPCO)
Asian Producers
- BASF-YPC
- LG Chem
- Formosa Plastics
Latin American Producers
- Braskem
Low Density Polyethylene Market - Report Scope
Table 8: Report Scope for the Low Density Polyethylene Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Technology; application; region |
| Quantitative units | USD billion |
| Market definition | Branched polyethylene resin with density of roughly 0.910 to 0.940 g/cm3, made by high-pressure free-radical polymerisation in tubular or autoclave reactors and sold for film, sheet, extrusion coating, injection moulding and other uses. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | LyondellBasell, ExxonMobil, Dow, SABIC, Qatar Petrochemical Company (QAPCO), BASF-YPC, LG Chem, Formosa Plastics, Braskem |
| Forecast period | 2026 to 2036 |
Low Density Polyethylene Market - Research Methodology
Table 9: Research Methodology for the Low Density Polyethylene Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers polyethylene prices, spreads, operating rates, plant closures, low-carbon grades and packaging rules. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 51.5 billion and the 4.4% CAGR for 2026 to 2036. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Low Density Polyethylene Market by Segments
Low Density Polyethylene Market segmented by Technology:
- Tubular
- Autoclave
Low Density Polyethylene Market segmented by Application:
- Film and Sheets
- Extrusion Coating
- Injection Moulding
- Others
Low Density Polyethylene Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Dow Inc. (2026, July 23). Dow reports second quarter 2026 results. https://investors.dow.com/en/news/news-details/2026/Dow-reports-second-quarter-2026-results/default.aspx
- [2] Braskem S.A. (2026, July 30). 2Q26 Production and Sales Report. https://www.latibex.com/docs/Documentos/esp/hechosrelev/2026/20260731_2Q26%20Production%20and%20Sales%20Report.pdf
- [3] LyondellBasell Industries N.V. (2026, July 31). LyondellBasell reports second quarter 2026 earnings (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0001489393/000148939326000057/a2026q2ex991_pressrelease.htm
- [4] Sen, I. (2026, July 30). Sabic posts $100m loss in Q2 2026 due to regional conflict. MEED. https://www.meed.com/sabic-posts-100m-loss-in-q2-2026-due-to-regional-conflict
- [5] Dow. (2025, July 7). Dow will shut down three upstream European assets in response to structural challenges in the region. https://corporate.dow.com/en-us/news/press-releases/dow-will-shut-down-three-upstream-european-assets-in-response-to.html
- [6] FreshPlaza. (2026, August 12). EU packaging regulation starts applying from August 12. https://www.freshplaza.com/europe/article/9862358/eu-packaging-regulation-starts-applying-from-august-12/
- [7] Braskem. (2026, April 28). Braskem to Showcase Sustainable Packaging Solutions at interpack 2026. Business Wire. https://www.businesswire.com/news/home/20260428736579/en/Braskem-to-Showcase-Sustainable-Packaging-Solutions-at-interpack-2026
- [8] Dow. (2026, September 17). Dow and Amcor launch strategic collaboration to accelerate adoption of low-carbon packaging solutions. https://corporate.dow.com/en-us/news/press-releases/dow-and-amcor-launch-strategic-collaboration-to-accelerate-adoption-of-low-carbon-packaging-solutions.html
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the low density polyethylene market during 2026?
- What market size is projected by 2036?
- Which technology holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the low density polyethylene market expected in 2026?
The low density polyethylene market is forecast at USD 51.5 billion in 2026, up from an estimated USD 49.3 billion in 2025. FMI expects sales of low density polyethylene to reach USD 79.2 billion by 2036.
What CAGR is projected for the low density polyethylene market through 2036?
Demand for low density polyethylene is projected to grow at a 4.4% CAGR through 2036. Food packaging film, extrusion coating and medical packs carry that growth.
Which technology holds a notable market share in 2026?
Tubular technology is likely to lead with 62.6% share in 2026. Autoclave reactors hold an estimated 37.4%.
Which application holds a notable market share in 2026?
Film and sheets are expected to lead with 67.6% share in 2026. Extrusion coating follows at an estimated 14.3%.
Which country has a notable expansion outlook through 2036?
FMI projects India to grow fastest, at 6.5%. ASEAN follows at 5.6%.
Who are the key companies in the low density polyethylene market?
LyondellBasell, ExxonMobil and Dow lead the US and European producers, and SABIC and Qatar Petrochemical Company (QAPCO) lead the Gulf group. BASF-YPC, LG Chem, Formosa Plastics and Braskem complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Tubular
- Autoclave
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Film and Sheets
- Extrusion Coating
- Injection Moulding
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Technology
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Technology
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Dow
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- LyondellBasell
- SABIC
- Braskem
- ExxonMobil
- Qatar Petrochemical Company (QAPCO)
- BASF-YPC
- LG Chem
- Formosa Plastics
- Dow
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


