
- Market Size (2026)
- USD 22.8 Bn
- Forecast (2036)
- USD 49.0 Bn
- CAGR (2026 to 2036)
- 8.0%
How big is Automotive SoC Market in 2026?
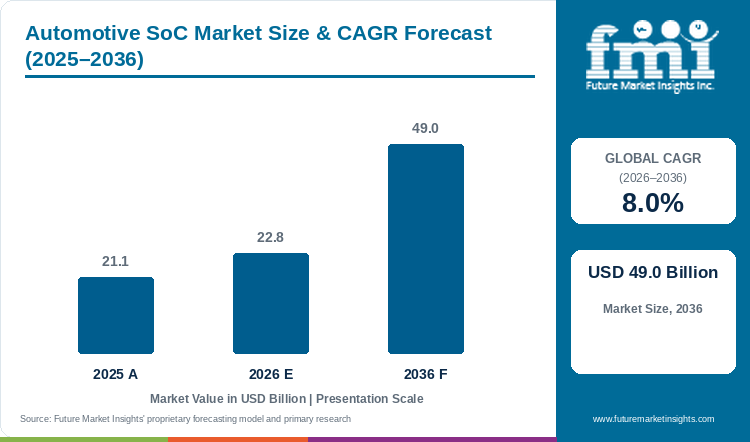
Demand is projected to expand at 7.95% CAGR from 2026 to 2036. Market value rises from USD 21.12 billion in 2025 to USD 22.8 billion in 2026 and USD 49 billion by 2036.
An automotive system-on-chip becomes commercially valuable when the vehicle manufacturer can integrate its computing functions into a dependable production platform, with software support and power consumption considered alongside processing speed. Infotainment provides an established purchasing base, while driver assistance and central computing create additional requirements for simultaneous workloads and reliable interfaces. Fraunhofer’s CeCaS work brings attention to the packaging implications of modular chiplets, including material behaviour and thermal-expansion differences. [1] These considerations affect qualification schedules because the assembled package must perform consistently within the intended vehicle environment. Research on multi-chiplet perception processing also illustrates the importance of evaluating an architecture against its actual workload. [2] Through the forecast period, suppliers that combine usable software, application evidence and repeatable manufacturing support should be better placed to convert engineering interest into vehicle programme revenue.
Key Market Trends & Insights
- Qualification support creates a specific supplier-development requirement.
- Packaging weaknesses can hold back an otherwise attractive design.
- Comparable application evidence can improve the route to nomination.
Regional Highlights
- China’s automotive-chip agenda includes intelligent-driving domain-controller computing and information security, alongside attention to performance and energy consumption (FMI outlook: 9.2% CAGR, 2026 to 2036).
- South Korea’s March 2026 support programme included functional-safety evaluation and improvement assistance for SoC, ADAS and ECU suppliers serving automotive supply chains (FMI outlook: 8.5% CAGR, 2026 to 2036).
- American automotive computing demand combines platform design with the integration work needed to apply advanced processors to a vehicle programme (FMI outlook: 8.1% CAGR, 2026 to 2036).
Market Size & Forecast
Table 1: Market Size and Forecast for Automotive SoC Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 21.12 billion |
| 2026 market value | USD 22.8 billion |
| 2036 market value | USD 49 billion |
| CAGR 2026 to 2036 | 7.95% |
| Revenue increase 2026 to 2036 | USD 26.2 billion |
| Market expansion 2026 to 2036 | 2.15 times |
The market covers automotive system-on-chip processors used in ADAS, central computing, infotainment and gateways. Standalone power semiconductors and general semiconductor-fabrication capacity are outside the scope.
Vehicle architectures coordinate computing with information from energy-management functions, making processor interfaces relevant to the systems covered in the Battery Management System Market. Suppliers need to understand how those signals enter the wider vehicle platform when software and hardware responsibilities are allocated.
From chiplet experiment to production nomination
Central automotive computing combines several technical responsibilities within one vehicle programme. Workload testing helps engineers assess processing arrangements, while package behaviour influences qualification and repeatable assembly. Public supplier-development programmes and standards work add institutional context to these decisions, with commercial value realised when the complete design can be integrated and maintained within the manufacturer's production architecture. [1][2][3][4]
Table 2: Industry evidence relevant to the automotive soc market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Chiplet packaging | Fraunhofer describes interface, material and thermal-expansion considerations within CeCaS automotive-chiplet work. | Package behaviour influences integration and qualification planning. | [1] |
| Perception workloads | DATE 2025 researchers evaluated multi-chiplet neural-processing arrangements through simulation. | Architecture comparisons should reflect the perception tasks assigned to the processor. | [2] |
| Supplier development | South Korea opened functional-safety evaluation and improvement support to automotive-semiconductor suppliers in 2026. | Evaluation capability supports suppliers preparing vehicle-programme submissions. | [3] |
Analyst Perspective
"An automotive processor wins a lasting place in a vehicle programme when its software and package can survive the transition from design to production. Manufacturers need evidence for the workloads they intend to run, followed by clear support for revisions across related vehicle models."
- Sudip Saha, Co-founder, Future Market Insights
How is the Automotive SoC Market segmented?
The market is segmented by Application, Vehicle Type, and Region.
Application segmentation distinguishes infotainment processing from ADAS workloads and other vehicle functions, while the vehicle-type breakdown separates passenger-car platforms from commercial vehicles. The purchasing implications differ because a cockpit’s display and connectivity requirements do not reproduce the sensing, scheduling and safety demands of driver assistance. Vehicle type adds the production scale, duty cycle and support requirements against which that computing architecture is selected.
Why do infotainment systems remain the largest application?
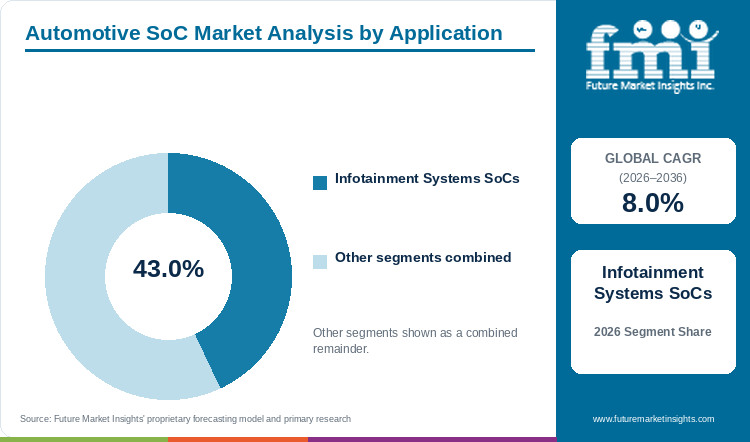
Table 3: Application Share for Automotive SoC Market (percentage share), 2026
| Application | Estimated share (2026) |
|---|---|
| Infotainment Systems SoCs | 43.0% |
| Other application segments | 57.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Automotive SoC Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.95% |
| Profiled application segment | Infotainment Systems SoCs |
Infotainment integrates navigation, media, connectivity and the driver’s interaction with the vehicle, making it an established computing purchase across a broad range of passenger-car programmes. Its estimated 43.0% application share in 2026 reflects this wider fitment base, while more demanding driver-assistance functions require additional processing and validation. A cockpit processor must support the display arrangement, operating software and communication interfaces selected for the vehicle, with acceptable heat and power use during simultaneous tasks. Purchasing therefore extends beyond the chip’s advertised computing capability to the work needed to maintain a stable user experience. Suppliers with compatible software and a clear route for subsequent updates can reduce integration effort across related vehicle models.
The Infotainment Systems SoCs segment is projected to account for 43.0% of application demand in 2026.
- Infotainment Systems SoCs: 43.0% of application demand (2026 estimate).
- A shared cockpit platform can support related vehicle models when display, software and communication requirements remain compatible.
What supports passenger cars within vehicle-type demand?
Table 5: Vehicle Type Share for Automotive SoC Market (percentage share), 2026
| Vehicle Type | Estimated share (2026) |
|---|---|
| Passenger Cars | 64.0% |
| Other vehicle type segments | 36.0% |
| Total | 100.0% |
Passenger cars bring together cockpit entertainment, navigation, connectivity and driver-assistance functions in a single purchasing programme, creating several opportunities for automotive SoC content. The segment is estimated to hold 64.0% of vehicle-type demand in 2026, supported by the combination of production scale and differentiation through electronic features. A manufacturer may reuse a computing architecture across multiple models while varying displays, software functions and equipment levels, which makes platform compatibility commercially useful. The programme still needs reliable power management and a supplier able to support later software revisions. Central computing changes the allocation of workloads within the vehicle, giving passenger-car developers a reason to assess package behaviour and software continuity together when selecting the next hardware platform.
The Passenger Cars segment is projected to account for 64.0% of vehicle type demand in 2026.
- Passenger Cars: 64.0% of vehicle type demand (2026 estimate).
- Passenger-car platform reuse increases the value of compatible software and dependable support across model variants.
- Cockpit processors must drive the selected screens at the required resolution and response, connecting their configuration with developments in the Flat Panel Display Market. The display arrangement helps define the graphics, power and software requirements of the complete cabin system.
What are the drivers, restraints, and opportunities in the Automotive SoC Market?
A supplier's strongest commercial case connects useful computing capability with the work a vehicle manufacturer must complete before production. Packaging evidence, usable software and an understandable revision process can make a platform easier to adopt across related models. This creates room for differentiation through integration support and lifecycle continuity alongside the processor's advertised performance.
Driver
Vehicle manufacturers require processors that can support connected cockpit and driver-assistance functions within a manageable electronic architecture, creating demand for application-specific computing and software support. South Korea's 2026 evaluation-assistance programme includes SoC and ADAS suppliers, showing the practical attention given to functional-safety improvement in the supply chain. [3] A supplier can address that requirement by connecting its processing capability with the integration and qualification work needed for a vehicle programme.
Restraint
A more flexible computing architecture can still require substantial package qualification because material behaviour and assembly consistency affect the completed component. Fraunhofer's CeCaS discussion identifies thermal-expansion mismatch, stress and warpage as relevant issues. [1] These engineering requirements can extend the time and resources needed to introduce a new design, particularly when the vehicle manufacturer must assess how later component revisions affect the established platform.
Opportunity
Suppliers can develop business by making their architectures easier to evaluate, integrate and maintain across related vehicle programmes. Perception-processing research illustrates the value of relating computing results to an actual workload. [2] A clear account of software interfaces, power requirements and package evidence can help manufacturers compare the complete implementation task, while dependable support makes an awarded design more useful through production and subsequent platform updates.
Connected-car applications rely on communication links for selected data and service functions, giving the Telecommunications Services Market a role in the wider deployment environment. Vehicle developers need to consider how an application behaves when the available connection changes.
Which country CAGRs are profiled in the Automotive SoC Market?
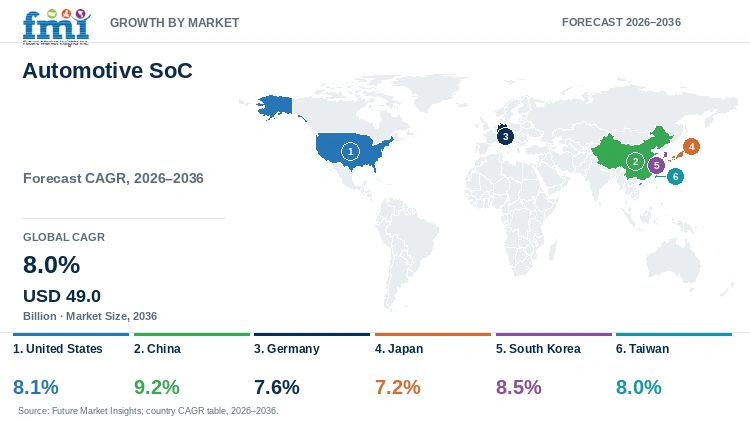
Table 6: Country CAGR Comparison for Automotive SoC Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| United States | 8.1% |
| China | 9.2% |
| Germany | 7.6% |
| Japan | 7.2% |
| South Korea | 8.5% |
| Taiwan | 8.0% |
Country-wise Analysis
United States Automotive SoC Market Outlook (2026 to 2036)
American automotive computing demand combines platform design with the integration work needed to apply advanced processors to a vehicle programme. A DATE 2025 study evaluated multi-chiplet neural processing for autonomous-driving perception, making workload selection a useful part of the country’s technical discussion. [2] For a vehicle integrator, the purchasing question concerns whether the proposed arrangement can sustain the required perception tasks within its power and scheduling constraints, while remaining compatible with the software environment. Suppliers' commercial prospects depend on converting that engineering capability into supported designs that vehicle manufacturers can qualify and maintain over successive production years.
China Automotive SoC Market Outlook (2026 to 2036)
China’s automotive-chip agenda includes intelligent-driving domain-controller computing and information security, alongside attention to performance and energy consumption. The 2025 standards-development priorities provide a concrete technical setting for local supplier preparation. [4] Manufacturers assessing these processors must relate computing capacity to the intended vehicle architecture, particularly where cockpit and assistance functions share resources. Procurement is likely to reward suppliers that can demonstrate stable interfaces, manageable power consumption and a practical software integration route. The resulting commercial opportunity extends from initial design work into continuing support when vehicle software and hardware configurations change.
Germany Automotive SoC Market Outlook (2026 to 2036)
Packaging is a material part of Germany’s central-computing opportunity because modular components must still behave as a dependable automotive assembly. Fraunhofer’s CeCaS discussion describes replaceable computing, memory and AI elements alongside thermal-expansion differences that can create stress and warpage. [1] This gives programme engineers a specific reason to assess materials and assembly control before committing to a flexible chiplet architecture. Suppliers that document package behaviour across relevant operating conditions can make component upgrades easier to evaluate, while clear responsibility for requalification helps manufacturers plan the cost and timing of later platform revisions.
Japan Automotive SoC Market Outlook (2026 to 2036)
Japan’s vehicle programmes give automotive computing suppliers a long product-support task because processor selection must remain compatible with the manufacturer’s electronic architecture and production schedule. Cockpit upgrades create demand for graphics and connectivity, while assistance functions place greater emphasis on coordinated sensing and predictable processing. Buyers comparing a consolidated computing unit with several established controllers will consider software reuse, heat management and the engineering work needed to qualify a change. Suppliers can strengthen their position through clear interfaces and lifecycle support that allow the vehicle developer to introduce additional functions without repeatedly rebuilding its complete computing arrangement.
South Korea Automotive SoC Market Outlook (2026 to 2036)
South Korea’s March 2026 support programme included functional-safety evaluation and improvement assistance for SoC, ADAS and ECU suppliers serving automotive supply chains. [3] The programme draws attention to the documented engineering work required for a fabless supplier to meet the expectations of vehicle manufacturers and their component partners. Suppliers need to connect that capability with evidence that their design can operate within the selected architecture and remain supportable during production. Evaluation assistance can help identify the improvements required, while commercial differentiation rests on completed qualification work, usable software and a reliable response when the customer’s integration requirements evolve.
Taiwan Automotive SoC Market Outlook (2026 to 2036)
Taiwan-linked automotive SoC supply arrangements place design, fabrication and package integration within a closely connected purchasing decision. A vehicle developer needs to know which organisation controls the package specification and how a change in computing or memory components will be assessed before production use. In chiplet-based arrangements, assembly consistency and thermal behaviour can affect the value of a modular design, so acceptance evidence should concern the completed package. Clear coordination between the processor vendor and its manufacturing partners also helps a customer manage revision schedules and maintain a dependable component supply over the vehicle programme’s life.
Who are the notable companies in the Automotive SoC Market?
Qualcomm Technologies; NVIDIA; Renesas Electronics; NXP Semiconductors; Texas Instruments
Automotive SoC suppliers compete for a place within a vehicle architecture that must remain workable through development and production. Qualcomm Technologies and NVIDIA address automotive computing platforms, while Renesas Electronics, NXP Semiconductors and Texas Instruments bring processor and integration capabilities to vehicle programmes. Selection depends on the proposed workload, available software and the support needed to qualify the complete system.
Competitive Benchmarking: Automotive SoC Market
Table 7: Competitive positioning for the automotive soc market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Qualcomm Technologies | Automotive processing platforms | Workload integration and programme support |
| NVIDIA | Automotive compute | Perception software and compute architecture |
| Renesas Electronics | Automotive SoCs | Integration and qualification documentation |
| NXP Semiconductors | Vehicle processing | Gateway and platform compatibility |
| Texas Instruments | Automotive processors | Application fit and lifecycle support |
Key Developments in the Automotive SoC Market
- Industry ministry / Korea Automotive Technology Institute (2026-03-04): The call includes SoC, ADAS and ECU suppliers in ISO 26262 functional-safety evaluation and improvement support. [3]
- Fraunhofer IZM (2025-11-20): CeCaS, a central-car-server research project running December 2022-November 2025, had EUR 46.2 million in programme funding. [1]
Key Players in the Automotive SoC Market
Automotive processing platforms
- Qualcomm Technologies
Automotive compute
- NVIDIA
Automotive SoCs
- Renesas Electronics
Vehicle processing
- NXP Semiconductors
Automotive processors
- Texas Instruments
Automotive SoC Market Report Scope
Table 8: Report Scope for Automotive SoC Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | The market covers automotive system-on-chip processors used in ADAS, central computing, infotainment and gateways. Standalone power semiconductors and general semiconductor-fabrication capacity are outside the scope. |
| Quantitative units | USD billion |
| Historical reference year | 2025 |
| Forecast period | 2026 to 2036 |
| Market breakdown | Application; Vehicle Type; Region |
| Countries profiled | United States; China; Germany; Japan; South Korea; Taiwan |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Key companies profiled | Qualcomm Technologies; NVIDIA; Renesas Electronics; NXP Semiconductors; Texas Instruments |
Automotive SoC Market Research Methodology
Table 9: Research Methodology for Automotive SoC Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | The market covers automotive system-on-chip processors used in ADAS, central computing, infotainment and gateways. Standalone power semiconductors and general semiconductor-fabrication capacity are outside the scope. |
| Secondary research | Public institutional reports, regulator publications, technical literature and supplier documentation provide the operating context for the market. |
| Quantitative coverage | Market values are expressed in USD billion, with a 2025 base value, a 2026 estimate and a projection for 2036. |
| Segment and country assessment | Segment categories retain distinct demand measures, while each country profile is linked with its estimated CAGR for 2026 to 2036. |
| Company comparison | Representative participants are compared by the product or service offered, the customer application and the implementation requirements relevant to procurement. |
Automotive SoC Market by Segments
Automotive SoC Market segmented by Application:
- Infotainment Systems SoCs
- ADAS SoCs
- Others
Automotive SoC Market segmented by Vehicle Type:
- Passenger Cars
- Commercial Vehicles
Automotive SoC Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- Taiwan
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Fraunhofer IZM. 20 November 2025. Automotive-Chiplets
- [2] Institute of Transportation Studies, University of California, Irvine. March 2025. Performance Implications of Multi-Chiplet Neural Processing Units on Autonomous Driving Perception
- [3] Industry ministry / Korea Automotive Technology Institute. 4 March 2026. Automotive-semiconductor functional safety and reliability support programme
- [4] Beijing Economic-Technological Development Area. 19 February 2025. National innovation centre’s 2025 automotive-chip standards priorities
This Report Answers
- How large is the Automotive SoC Market in 2026?
- What is the growth outlook for the Automotive SoC Market through 2036?
- What is the 2026 share of Infotainment Systems SoCs?
- What is the 2026 share of Passenger Cars?
- Which profiled market has the highest projected growth?
- Who are the notable participants in the Automotive SoC Market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Infotainment Systems SoCs
- ADAS SoCs
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Commercial Vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- Taiwan
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Taiwan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Vehicle Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Qualcomm Technologies
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- NVIDIA
- Renesas Electronics
- NXP Semiconductors
- Texas Instruments
- Qualcomm Technologies
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Application
- Figure 6: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Vehicle Type
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Application
- Figure 23: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Vehicle Type
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Application
- Figure 30: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Application
- Figure 37: Western Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by Vehicle Type
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Application
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by Vehicle Type
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Application
- Figure 51: East Asia Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by Vehicle Type
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by Vehicle Type
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Automotive SoC Market in 2026?
The market is estimated at USD 22.8 billion in 2026, compared with USD 21.12 billion in 2025.
What is the growth outlook for the Automotive SoC Market through 2036?
The market is projected to reach USD 49 billion by 2036, representing a CAGR of 7.95% from 2026 to 2036.
What is the 2026 share of Infotainment Systems SoCs?
The Infotainment Systems SoCs segment is estimated to account for 43% of application demand in 2026. A shared cockpit platform can support related vehicle models when display, software and communication requirements remain compatible.
What is the 2026 share of Passenger Cars?
The Passenger Cars segment is estimated to account for 64% of vehicle type demand in 2026. Passenger-car platform reuse increases the value of compatible software and dependable support across model variants.
Which profiled market has the highest projected growth?
China has the highest projected rate among the markets profiled, at 9.2% CAGR from 2026 to 2036.
Who are the notable participants in the Automotive SoC Market?
Representative participants include Qualcomm Technologies, NVIDIA, Renesas Electronics, NXP Semiconductors, Texas Instruments.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
