

- Market Size (2026)
- USD 2.2 Bn
- Forecast (2036)
- USD 5.1 Bn
- CAGR (2026 to 2036)
- 8.9%
How big is Aerospace Titanium Market in 2026?
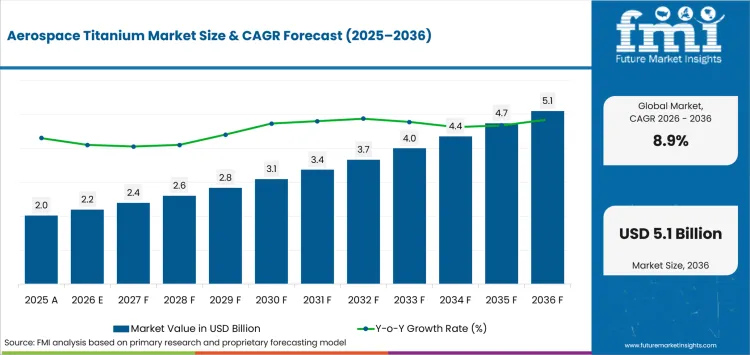
USD 2.2 billion in 2026 and USD 5.1 billion by 2036 at an 8.9% CAGR.
Demand for aerospace titanium is projected to increase valuation from USD 2.2 billion in 2026 to USD 5.1 billion by 2036 at 8.9% CAGR.Commercial aircraft output converts directly into recurring orders for qualified titanium sheet and plate plus billet and forgings across established aircraft programs. Airbus reported in June 2026 that its A320 Family network reached ten final assembly lines and was ramping toward 75 aircraft monthly. That build cadence requires mills and forges to reserve approved capacity well before final assembly schedules.
Country demand diverges according to local program exposure and the point where each aerospace base enters the titanium supply chain. The Aerospace Industries Association reported in June 2026 that USA aerospace and defense exports reached USD 172.7 billion during 2025. Export scale increases exposure to production schedules and qualified material availability even when titanium processing stays concentrated among approved producers. France and Japan face different constraints because one concentrates aircraft assembly while the other carries more upstream titanium capacity.
Key Takeaways
- Aircraft production ramps raise recurring titanium orders because qualified material enters rolling and forging schedules several tiers before final assembly.
- Based on product form, mill products are projected to account for 51.0% in 2026 due to broad use across qualified wrought routes.
- By alloy category, alpha-beta alloys are estimated to hold 62.5% in 2026 owing to Ti-6Al-4V use across several certified aerospace applications.
- Commercial aviation is set to lead the end-market with 55.6% share in 2026 due to recurring material call-offs across large aircraft programs.
- Long qualification cycles and concentrated titanium conversion capacity delay source switching even when aircraft programs require additional approved material.
- Some of the key players in this market include ATI Inc. (Allegheny Technologies), Howmet Aerospace Inc., Carpenter Technology Corporation, Kobe Steel, Ltd., Toho Titanium Co., Ltd., IperionX Limited, Norsk Titanium AS, and Tekna Holding ASA.
Analyst Perspective
“Evaluation should prioritize melt pedigree and qualification coverage during aircraft rate changes instead of quoted titanium capacity alone. Producers earn stronger economics by reserving approved conversion capacity and reducing buy-to-fly loss without reopening qualified material routes.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the aerospace titanium market segmented?
The market is segmented by product form, alloy category, end-market, sales channel and region.
The aerospace titanium market is segmented by product form, alloy category, end-market, sales channel and region. Product form covers mill products, powder and AM feedstock, forged products and cast products across procurement routes. Alloy category covers alpha-beta alloys, alpha and near-alpha alloys, beta or metastable beta alloys and commercially pure grades. End-market includes commercial aviation, military aviation, MRO or aftermarket and space and launch systems worldwide. Sales channels include direct to OEM, tier-1 aerospace suppliers, tier-2 and tier-3 component manufacturers and distributors or service centers.
Why do alpha-beta alloys lead the alloy category?
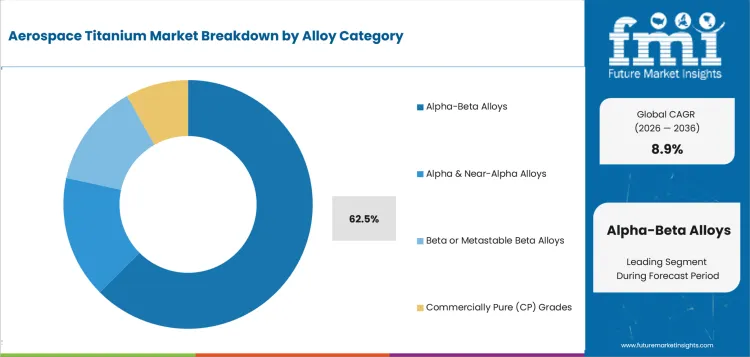
Alpha-beta alloys retain broad engineering acceptance because Ti-6Al-4V balances strength and manufacturability across structural and rotating component routes. Familiar chemistry also lets titanium powder programs adopt newer production methods without introducing an entirely different alloy family.
- Alpha-beta alloys are projected to hold 62.5% share in 2026 owing to established specifications across several aerospace component routes.
- Tekna reported a July 2025 order worth CAD 1.6 million for Ti-6Al-4V powder from a USA aerospace and defense Tier-1. The order places a familiar aerospace alloy directly into laser powder bed fusion production while supporting repeat purchases under established customer specifications.
What makes mill products central to the product form category?
Mill products remain the standard entry point for aerospace forging materials programs that machine or form titanium after material certification. Sheet and plate plus billet and bar let airframe and engine producers apply one approved metallurgy across several downstream part routes.
- By product form, mill products are estimated to hold 51.0% in 2026 owing to established wrought routes across qualified airframe and engine programs.
- ATI expanded that supply route in June 2025 by bringing its Pageland titanium alloy sheet facility online with aerospace qualifications underway. Long-term customer commitments cover much of planned capacity and tie new sheet output to recurring aerospace demand.
How does commercial aviation lead the end-market category?
Commercial aviation provides the largest recurring order base because narrowbody and widebody programs consume qualified titanium across airframes and aircraft engine blades. Backlog visibility lets approved mills reserve melting and conversion slots against multi-year delivery plans worldwide.
- In 2026, commercial aviation is expected to lead end-market demand with 55.6% share because sustained production schedules support recurring material call-offs.
- Boeing reported 171 commercial airplane deliveries during the second quarter of 2026 and a commercial backlog above 6,200 aircraft. That installed and future fleet also supports air transport MRO demand for approved replacement material across long service cycles.
What supports direct to OEM leadership in the sales channel category?
Direct OEM contracting gives airframers tighter control over approved aerospace lightweight materials and delivery windows for high-volume titanium programs. The channel also lets producers reserve qualified capacity against defined multi-year call-off schedules for scheduled production.
- Direct to OEM is set to lead the sales channel with 56.6% share in 2026 due to source-control and traceability requirements.
- ATI signed a multi-year Airbus agreement in May 2025 covering titanium plate and sheet plus billet as the airframer increased production. The arrangement supports downstream aerospace fastener manufacturing and other component routes by moving qualified material planning earlier in the program schedule.
What are the drivers, restraints and opportunities in the Aerospace Titanium Market?
Aircraft build rates raise qualified material demand while source qualification and import concentration restrict rapid substitution, and near-net-shape processing offers a route to lower titanium conversion loss.
- Driver: Long aircraft backlogs pull qualified titanium orders forward into melt and conversion schedules before final assembly begins.
- Restraint: Concentrated upstream supply and program-specific approvals slow source replacement when existing titanium routes face capacity or logistics pressure.
- Opportunity: Qualified near-net-shape processing reduces machining loss and gives producers a revenue route into parts with high buy-to-fly ratios.
Aircraft Backlogs Pull Material Orders Forward
Long aircraft backlogs pull titanium into rolling and forging schedules several tiers before final assembly. Boeing reported in April 2026 that first-quarter deliveries reached 143 commercial airplanes while its commercial backlog exceeded 6,100 aircraft. Approved mills and investment casting shops use that visibility to plan larger call-offs and reserve processing slots before aircraft rate increases reach tier schedules across major programs.
Qualification and Import Exposure Slow Substitution
Program approvals tie material chemistry and process history to named aerospace production routes, slowing source substitution during shortages. The European Commission's Joint Research Centre reported in January 2025 that EU titanium product imports were about six times exports. Import dependence exposes airframers to external processing capacity, while requalification limits how quickly an approved source can be replaced during production disruptions.
Near-Net-Shape Routes Reduce Conversion Loss
Near-net-shape processing reduces titanium removed during machining and shortens conversion routes for suitable aerospace parts. IperionX commissioned a 300-ton six-axis powder-metallurgy press in Virginia during May 2026 and said the machine tripled existing powder-metallurgy capacity. For suitable structures, qualified routes using aerospace 3D printing materials reduce buy-to-fly loss once producers demonstrate repeatable serial output across approved component families at commercial scale.
Which country CAGRs are profiled in the Aerospace Titanium Market?
| Country | CAGR |
|---|---|
| Canada | 10.0% |
| France | 9.7% |
| Japan | 9.4% |
| USA | 8.6% |
| Germany | 8.4% |
How do country-level CAGRs compare in the Aerospace Titanium Market?
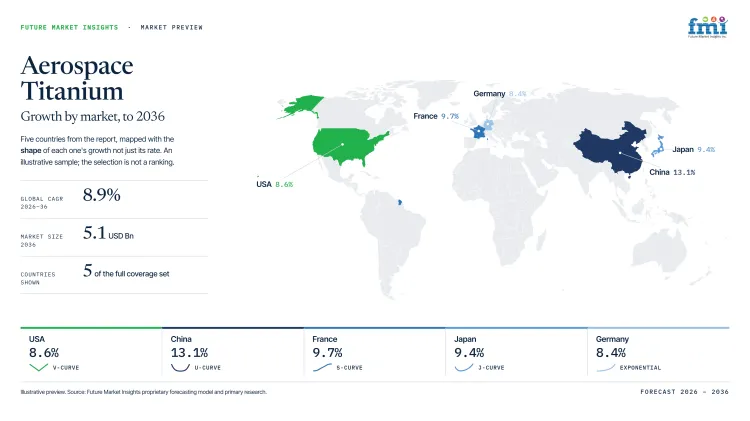
Five countries span 1.6 percentage points from Canada at 10.0% CAGR to Germany at 8.4%. Canada and France form the upper band while Japan occupies a distinct middle position. The USA and Germany cluster lower as mature program access and long qualification cycles narrow forecast differences despite aerospace footprints.
- Canada's tier and MRO mix rewards inventory near major aircraft production clusters.
- France closely follows Airbus build cadence and nearby qualified aerostructure conversion capacity.
- Japan's upstream sponge base rewards consistent metallurgy across long-duration global aircraft programs.
- USA programs favor approved domestic titanium routes across deep tier networks.
- Germany's civil base places greater weight on logistics discipline than primary expansion.
Comparable CAGRs mask qualification burdens and service costs across different national aerospace bases. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- Montreal and Toronto aerospace clusters generate titanium demand through both OEM production and aftermarket activity, supported by digital MRO networks coordinating maintenance requirements across Quebec and Ontario. Canada’s aerospace titanium market is expected to expand at a 10.0% CAGR through 2036, bolstered by the growing prominence of domestic aircraft manufacturing, particularly the A220 program. This momentum was highlighted in May 2026 when the Prime Minister of Canada announced AirAsia’s agreement to purchase 150 A220-300 aircraft for assembly at Mirabel. Beyond major OEM requirements, regional machining suppliers rely on responsive plate and bar availability for irregular orders, making inventory flexibility and localized processing capabilities important differentiators in a market still exposed to imported-material lead times.
- Toulouse-centered aircraft production continues to influence titanium procurement patterns across France’s tightly interconnected aerostructure supply chain, where access to qualified mills and forging facilities remains critical. France is forecast to record a 9.7% CAGR through 2036, supported by increasing production activity across Airbus programs and a broader recovery in commercial aerospace manufacturing. The sector’s momentum is reinforced by rising aircraft output rates and a substantial Airbus commercial aircraft backlog, which continues to support long-term demand visibility across the supply chain. As production schedules accelerate, suppliers that can align material reservations with confirmed build programs are likely to gain market share, particularly where traceability requirements and proximity to conversion facilities outweigh opportunities for alternative sourcing.
- Japan occupies a distinctive position within the aerospace titanium value chain through its concentration of sponge and alloy producers supplying global engine and structural programs. Demand is projected to increase at a 9.4% CAGR through 2036, reflecting the continued importance of high-purity titanium feedstocks in internationally qualified aerospace applications. Supporting this outlook, the Society of Japanese Aerospace Companies reported that engine production accounted for nearly two-thirds of monthly aerospace manufacturing output in May 2026, underscoring Japan’s strategic importance within global propulsion supply chains. Because qualification cycles for upstream materials are lengthy and highly regulated, manufacturers with a proven record of metallurgical consistency and international documentation coordination are better positioned to maintain participation in long-term aerospace programs.
- Commercial aviation and additive manufacturing applications collectively sustain broad titanium demand across the United States, often competing for access to qualified melt capacity. The USA aerospace titanium market is anticipated to grow at an 8.6% CAGR through 2036, driven by a diverse mix of airframe, engine, and advanced manufacturing requirements. Continued growth in civilian aircraft exports and sustained international demand for USA-manufactured aerospace platforms reinforce titanium consumption across both commercial and defense-oriented programs. While large OEMs secure significant volumes directly from producers, service centers continue to play a critical role by supplying smaller qualified orders, creating opportunities for distributors with established domestic supply routes during periods of capacity constraint.
- Hamburg-based civil aviation programs underpin German titanium consumption across export-oriented aerostructure and engine manufacturing operations. Germany’s market is projected to expand at an 8.4% CAGR through 2036, supported by stable OEM production schedules and long-standing participation in European aerospace supply chains. Civil aviation remains the largest component of Germany’s aerospace industry, reinforcing the sector’s importance to industrial titanium demand. Limited domestic primary titanium production maintains reliance on imported feedstock, increasing the value of dependable conversion partners and proven delivery performance for aerospace-grade materials during production-rate adjustments.
Who are the notable companies in the Aerospace Titanium Market?
ATI Inc. (Allegheny Technologies), Howmet Aerospace Inc., Carpenter Technology Corporation, Kobe Steel, Ltd., Toho Titanium Co., Ltd., IperionX Limited, Norsk Titanium AS, and Tekna Holding ASA are the notable companies serving this market.
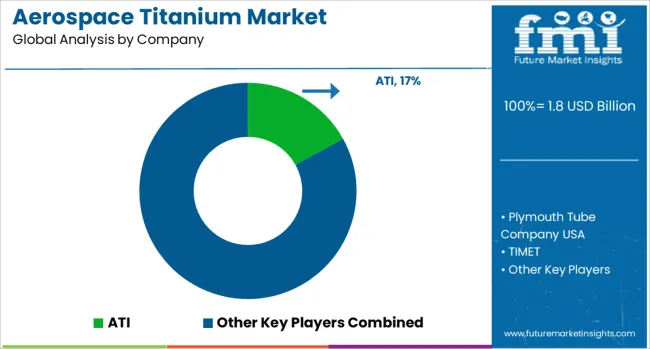
Eight profiled companies occupy three distinct positions across aerospace titanium material and conversion routes. ATI and Howmet span integrated material and conversion routes while Carpenter Technology and Toho Titanium focus upstream. IperionX and additive specialists compete closer to finished geometry where serial qualification limits entry.
- ATI Inc. (Allegheny Technologies), Howmet Aerospace Inc. and Kobe Steel, Ltd. span melt and conversion routes for qualified aerospace production.
- Carpenter Technology Corporation and Toho Titanium Co., Ltd. concentrate on premium alloy chemistry and qualified upstream feedstock.
- IperionX Limited, Norsk Titanium AS and Tekna Holding ASA focus on powder and near-net-shape production for qualified aerospace parts.
Competitive Benchmarking: Aerospace Titanium Market
| Company | Titanium Product Breadth | Aerospace Qualification Depth | Conversion Integration | Geographic Reach |
|---|---|---|---|---|
| ATI Inc. (Allegheny Technologies) | High | High | High | Global |
| Howmet Aerospace Inc. | High | High | High | North America and Europe |
| Carpenter Technology Corporation | Medium | High | Medium | North America |
| Kobe Steel, Ltd. | Medium | High | Medium | Japan and global programs |
| Toho Titanium Co., Ltd. | Medium | Medium | Medium | Japan and international markets |
| IperionX Limited | High | Medium | High | United States |
| Norsk Titanium AS | Low | High | Medium | United States and Norway |
| Tekna Holding ASA | Low | High | Low | Canada and France |
Scoring basis: Product breadth is High for three titanium forms, Medium for two and Low for one. Qualification depth is High for recurring serial supply, Medium for one current qualification and Low for one specialist approval. Conversion integration is High for three controlled stages, Medium for two and Low for one.
Key Developments in the Aerospace Titanium Market
- In June 2026, Norsk Titanium AS signed a Cooperation & Research Agreement with Airbus to industrialize and qualify RPD technology for high-criticality structural titanium parts.
- In October 2025, Tekna Holding ASA received NADCAP AC7143 accreditation for metallic powder manufacturing to support qualified titanium powder production for serial aerospace additive manufacturing.
- In June 2025, IperionX Limited received a USA Department of Defense Phase III IDIQ contract worth up to USD 99 million covering titanium fasteners and qualification work.
Key Players in the Aerospace Titanium Market
Integrated Titanium and Aerospace Conversion
- ATI Inc. (Allegheny Technologies)
- Howmet Aerospace Inc.
Specialty Alloy and Sponge Producers
- Carpenter Technology Corporation
- Kobe Steel, Ltd.
- Toho Titanium Co., Ltd.
Powder and Near-Net-Shape Specialists
- IperionX Limited
- Norsk Titanium AS
- Tekna Holding ASA
Aerospace Titanium Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product form, alloy category, end-market, sales channel and region. |
| Quantitative Units | USD billion. |
| Market Definition | Commercial aerospace-grade titanium forms and alloys supplied into qualified aircraft, engine, MRO and space production routes. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Canada, France, Japan, USA, Germany, and 20+ countries included in the full report. |
| Key Companies Profiled | ATI Inc. (Allegheny Technologies), Howmet Aerospace Inc., Carpenter Technology Corporation, Kobe Steel, Ltd., Toho Titanium Co., Ltd., IperionX Limited, Norsk Titanium AS, and Tekna Holding ASA. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Aerospace Titanium Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Aerospace Titanium Market by Segments
Aerospace Titanium Market segmented by Product Form:
- Mill Products
- Powder & AM Feedstock
- Forged Products
- Cast Products
Aerospace Titanium Market segmented by Alloy Category:
- Alpha-Beta Alloys
- Alpha & Near-Alpha Alloys
- Beta or Metastable Beta Alloys
- Commercially Pure (CP) Grades
Aerospace Titanium Market segmented by End-Market:
- Commercial Aviation
- Military Aviation
- MRO or Aftermarket
- Space & Launch Systems
Aerospace Titanium Market segmented by Sales Channel:
- Direct to OEM
- Tier-1 Aerospace Suppliers
- Tier-2 & 3 Component Manufacturers
- Distributors or Service Centers
Aerospace Titanium Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Airbus. (2026, June 15). Airbus inaugurates second A320 Family final assembly line in Toulouse.
- Aerospace Industries Association. (2026, June 25). 2026 AIA Facts & Figures: USA Aerospace & Defense Industry Leads the World with $1 Trillion in Sales.
- ATI Inc. (2025, June 12). ATI expands portfolio to produce Titanium Alloy Sheet for aerospace.
- Tekna Holding ASA. (2025, July 4). Tekna Receives CAD 1.6 Million Titanium Powder Order from USA Aerospace and Defense Tier-1 Supplier.
- Boeing. (2026, July 28). Boeing Reports Second Quarter Results.
- ATI Inc. (2025, May 28). ATI signs multi-year agreement with Airbus for titanium plate, sheet and billet.
- Boeing. (2026, April 22). Boeing Reports First Quarter Results.
- European Commission, Joint Research Centre. (2025, January 23). Closing the loop on the EU’s titanium supply chain.
- IperionX Limited. (2026, May 21). IperionX Commissions Six-Axis Powder Metallurgy Press, Expanding USA Titanium Component Manufacturing Capabilities.
- Prime Minister of Canada. (2026, May 6). Prime Minister Carney welcomes the largest order of commercial aircraft in Canadian history.
- GIFAS. (2025, May 19). 2024 Report: The French aerospace sector regains pre-Covid levels thanks to unprecedented industrial mobilisation.
- Society of Japanese Aerospace Companies. (2026, August 10). Aircraft production performance (May 2026).
- USA Census Bureau & USA Bureau of Economic Analysis. (2026, June 9). USA International Trade in Goods and Services, April 2026.
- German Aerospace Industries Association. (2025, May 22). Industry data 2024: German aerospace industry on the rise.
- JX Advanced Metals Corporation. (2026, April 24). Notice Regarding Conversion by JX Advanced Metals Corporation of Toho Titanium Co., Ltd. into a Wholly-Owned Subsidiary Company.
- Tekna Holding ASA. (2025, October 15). Tekna Advanced Materials World’s First NADCAP Accredited Metallic Powder Manufacturing.
- IperionX Limited. (2025, June 5). IperionX Awarded USA Department of Defense SBIR Phase III Contract for Up to US$99M.
- ATI Inc. (2026, February 20). Annual Report on Form 10-K for the fiscal year ended December 28, 2025.
- Howmet Aerospace Inc. (2026, May 7). Quarterly Report on Form 10-Q for the quarter ended March 31, 2026.
- Carpenter Technology Corporation. (2025, August 12). Annual Report on Form 10-K for the fiscal year ended June 30, 2025.
- Kobe Steel, Ltd. (2026, May 19). Progress on the Kobelco Group Medium-Term Management Plan (Fiscal 2024-2026).
- IperionX Limited. (2025, October 14). Annual Report 2025.
- Norsk Titanium AS. (2025, May 8). Norsk Titanium First Quarter Operational Update.
- Norsk Titanium AS. (2025, November 6). Norsk Titanium Third Quarter Operational Update.
- Tekna Holding ASA. (2026, April 9). 2025 Annual Report.
- ATI Inc. (2025, July 31). ATI and Boeing extend and expand titanium supply long-term agreement.
- IperionX Limited. (2025, September 2). IperionX Accelerates USA Titanium Buildout to Deliver Largest Scale and Lowest Unit-Cost Production.
- Norsk Titanium AS. (2026, June 2). Norsk Titanium and Airbus are partnering to industrialize and qualify Plasma DED RPD® technology for high criticality structural titanium parts.
- Tekna Holding ASA. (2026, January 6). TEKNA Receives 2nd significant Titanium Powder Order from a USA Aerospace and Defense Tier-1 Supplier.
- OSAKA Titanium Technologies Co., Ltd. (2026, March 16). Notice Concerning Change in the Investment Amount for Sponge Titanium Production Capacity Enhancement.
- Aerolloy Technologies Limited. (2026, February 10). Aerolloy Technologies Signs MoUs with Ministry of Steel under PLI Scheme 1.2 for Titanium Alloys and Super Alloys.
- Aerolloy Technologies Limited. (2026, August 6). Aerolloy Technologies Signs Landmark Agreement with Airbus for Titanium Castings for A320neo, A330neo and A350 Programmes.
- OSAKA Titanium Technologies Co., Ltd. (2026, May 14). Notice Regarding the Formulation of the Medium-Term Management Plan “OTC 2030”.
- The Perryman Company. (2025, November 22). Certificate of Registration: ISO 9001:2015 and AS9100D.
- Carpenter Technology Corporation. (2025, July 31). Carpenter Technology Reports Fourth Quarter and Fiscal Year 2025 Results.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the aerospace titanium market in 2026 and 2036?
- Which production conditions convert aircraft schedules into recurring qualified titanium orders?
- Why do mill products lead product-form demand in the aerospace titanium market?
- Why do alpha-beta alloys lead alloy-category demand in 2026?
- How does commercial aviation shape recurring titanium demand across aircraft supply chains?
- How do five profiled countries differ in forecast growth and market-entry conditions?
- Which companies cover the broadest titanium production and aerospace conversion routes?
- Where do qualification limits and near-net-shape processing change commercial opportunity?
Frequently Asked Questions
How big is the Aerospace Titanium Market in 2026?
The aerospace titanium market is valued at USD 2.2 billion in 2026 and is projected to reach USD 5.1 billion by 2036. Aircraft production ramps support recurring orders for qualified titanium forms across long-duration airframe and engine programs.
What is the CAGR of the Aerospace Titanium Market from 2026 to 2036?
The aerospace titanium market is projected to grow at a CAGR of 8.9% between 2026 and 2036. Expansion is supported by aircraft build schedules that require approved titanium several tiers before final assembly.
Which product form leads the Aerospace Titanium Market?
The mill products segment is expected to hold 51.0% of the aerospace titanium market in 2026, supported by qualified sheet and billet use across airframe and engine programs. Approved wrought forms limit route changes and preserve documented supply continuity across recurring aircraft orders.
Which alloy category leads the Aerospace Titanium Market?
The alpha-beta alloys segment is expected to hold 62.5% of the aerospace titanium market in 2026, attributable to Ti-6Al-4V use across established structural and engine applications. Familiar chemistry also supports established qualification records across wrought and additive production routes for aerospace components.
Which companies are active in the Aerospace Titanium Market?
Key companies operating in the aerospace titanium market include ATI Inc. (Allegheny Technologies), Howmet Aerospace Inc., Carpenter Technology Corporation, Kobe Steel, Ltd., Toho Titanium Co., Ltd., IperionX Limited, Norsk Titanium AS, and Tekna Holding ASA. They compete on qualification depth, delivery reliability and conversion control.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Mill Products
- Powder & AM Feedstock
- Forged Products
- Cast Products
- Mill Products
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Alloy Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Alloy Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Alloy Category, 2026 to 2036
- Alpha-Beta Alloys
- Alpha & Near-Alpha Alloys
- Beta or Metastable Beta Alloys
- Commercially Pure (CP) Grades
- Alpha-Beta Alloys
- Y-o-Y Growth Trend Analysis By Alloy Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Alloy Category, 2026 to 2036
- Global Market Analysis and Forecast, By End-Market, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Market, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Market, 2026 to 2036
- Commercial Aviation
- Military Aviation
- MRO or Aftermarket
- Space & Launch Systems
- Commercial Aviation
- Y-o-Y Growth Trend Analysis By End-Market, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Market, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to OEM
- Tier-1 Aerospace Suppliers
- Tier-2 & 3 Component Manufacturers
- Distributors or Service Centers
- Direct to OEM
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Alloy Category
- By End-Market
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- VSMPO-AVISMA Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ATI Inc. (Allegheny Technologies)
- Howmet Aerospace Inc.
- Precision Castparts Corp. (TIMET)
- Carpenter Technology Corporation
- Baoji Titanium Industry Co., Ltd.
- Sandvik AB
- Kobe Steel, Ltd.
- Toho Titanium Co., Ltd.
- IperionX Limited
- VSMPO-AVISMA Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


