
- Market Size (2026)
- USD 12.10 Bn
- Forecast (2036)
- USD 28.64 Bn
- CAGR (2026 to 2036)
- 9.0%
How Big Is the Construction Design Software Market in 2026?
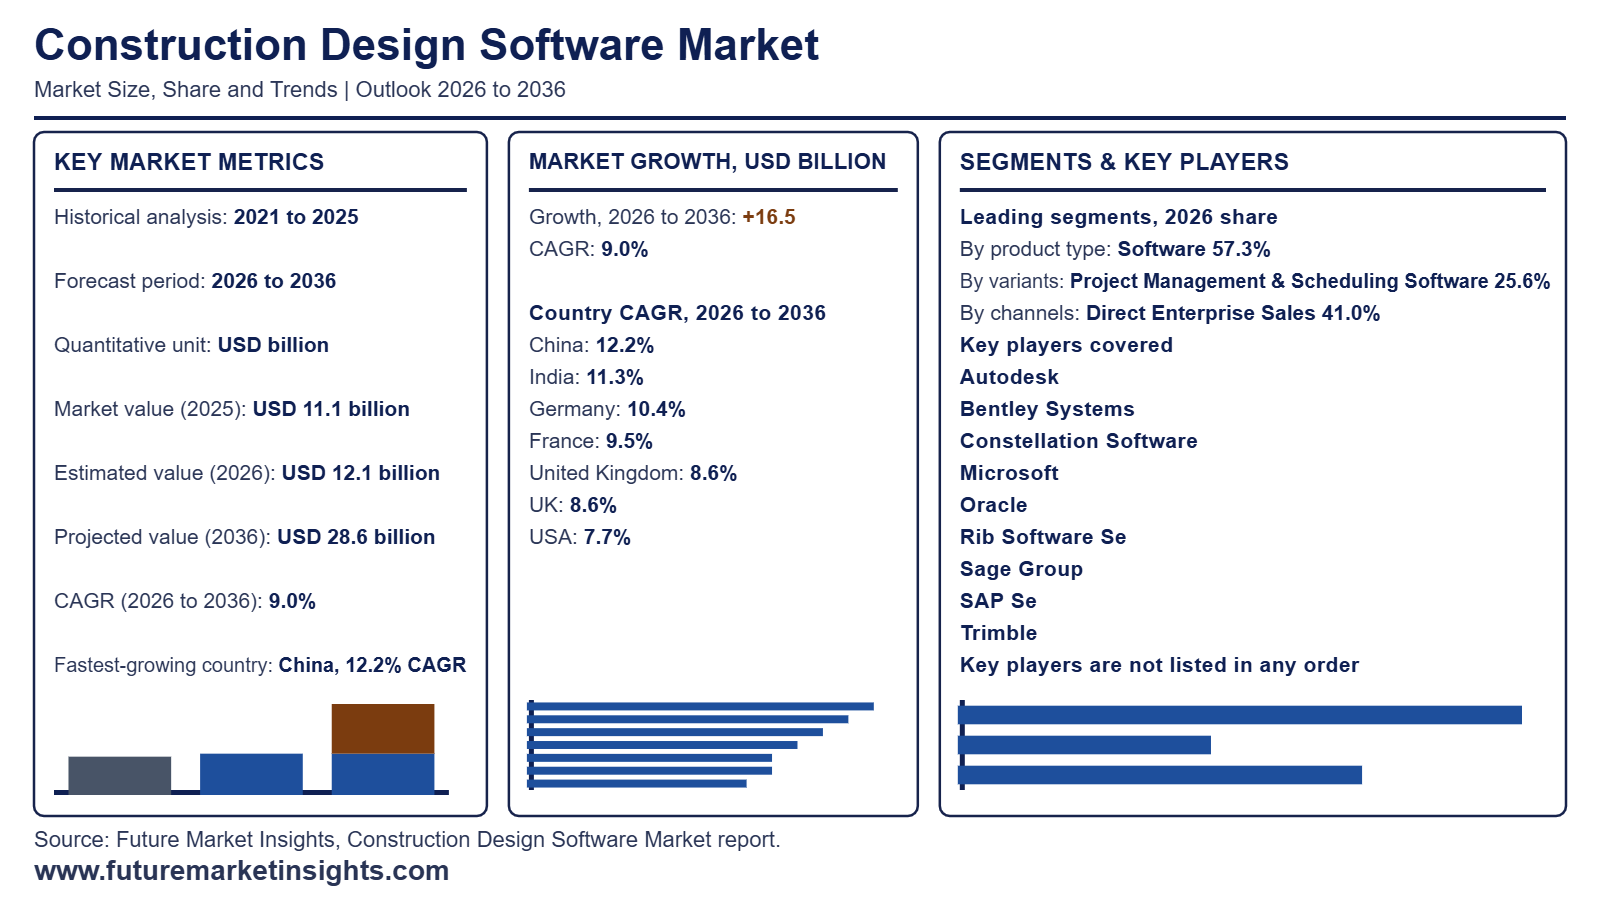
The global construction design software market is valued at USD 12.10 billion in 2026, up from USD 11.10 billion in 2025. Future Market Insights (FMI) expects the market to reach USD 28.64 billion by 2036, growing at a 9.0% CAGR from 2026 to 2036 and adding USD 16.54 billion in revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 11.10 billion |
| 2026 Market Size (Estimated) | USD 12.10 billion |
| 2036 Market Size (Projected) | USD 28.64 billion |
| Compound Annual Growth Rate (2026 to 2036) | 9.0% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 16.54 billion |
| Dominant Product Type (2026 to 2036 Share) | Software (57.3% in 2026, rising to 60.5% by 2036) |
| Leading & Fastest-Growing Variants | Project Management & Scheduling Software (25.6% share in 2026; 8.2% CAGR) | Field Service Management Software (11.6% CAGR) |
| Leading & Fastest-Growing Channels | Direct Enterprise Sales (41.0% share in 2026) | Cloud Marketplaces (12.4% CAGR) |
| Largest Country Markets (2026 Global Share) | United States (30.0%), Germany (7.5%), United Kingdom (6.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | Germany (10.4% CAGR), France (9.5% CAGR), United Kingdom (8.6% CAGR) |
| Leading Tier-1 Companies | Autodesk, Bentley Systems, Trimble, Oracle, RIB Software |
Source: Future Market Insights analysis of the construction design software market, 2026.
Executive Market Overview
Demand for construction design software is expected to be driven by architects and contractors moving drawings and schedules into shared digital models, along with building owners asking for model-based handover data. Software accounts for 57.3% of 2026 revenue, and cloud deployment makes up 61.8% of spending by deployment model. The United States is likely to remain the largest market, as its design firms and general contractors buy more software seats than those in any other country. Germany and the United Kingdom are set to remain important markets. Germany is expected to post the fastest growth, ahead of France and the United Kingdom, as dwelling permits there rose 10.6% in 2025, according to Destatis.
Most firms buy construction design software as annual subscriptions for each named user, and every member of a project team needs the same version to open shared models. Vendors are moving customers from desktop licenses to cloud platforms that link design models with site schedules, and they are adding AI tools that flag clashes between building systems. FMI expects field service management software tools to grow at an 11.6% CAGR and safety and reporting software tools at a 10.7% CAGR through 2036, ahead of the 9.0% overall market average. Cost accounting software tools trail at a 7.8% CAGR. Market sizing covers software used to design and manage building and civil construction projects, along with the implementation and training services sold with it. General office software and standalone accounting packages are excluded, as are equipment telematics, laser scanners, drones and other site hardware.
Analyst Perspective
"Construction design software revenue will rise faster than seat counts, because firms are moving to cloud plans that bundle model sharing and scheduling at a higher fee. The risk sits in the United States, where Census Bureau data put 2026 construction spending through September below 2025 levels, and fewer new projects would slow seat growth."
Sudip Saha, Principal Consultant, Future Market Insights (FMI)
Construction Design Software Market Definition
Construction design software represents the digital design, planning, and coordination technology layer for the built environment industry. The market spans BIM authoring engines, project scheduling and resource planning tools, structural analysis and MEP design platforms, safety compliance modules, and field management applications. As per FMI, the market is transitioning from isolated design tool purchases to integrated cloud-native platform subscriptions, driven by government digital delivery mandates and the operational necessity of real-time multi-disciplinary coordination across distributed project teams.
Construction Design Software Market Inclusions
Market scope covers BIM authoring and coordination software, project scheduling and resource planning tools, structural and MEP design applications, safety and compliance management modules, field service management platforms, and cost estimation engines for construction projects.
Construction Design Software Market Exclusions
General-purpose CAD software without construction-specific workflows, standalone document management systems, and enterprise resource planning suites not tailored to project-based construction accounting are excluded.
Construction Design Software Market Research Methodology
- Primary Research: Analysts conducted structured interviews with procurement managers, product engineers, and distribution channel operators to map purchase decision triggers and specification requirements across key verticals.
- Desk Research: Data collection aggregated regulatory filings, industry standards documentation, patent registries, trade body publications, and company annual reports across all target geographies.
- Market-Sizing and Forecasting: Baseline values derive from a bottom-up aggregation of product shipment volumes and average selling prices, validated against publicly disclosed revenue figures from leading suppliers.
- Data Validation and Update Cycle: Projections are cross-referenced against quarterly earnings data, import-export trade statistics, and industry association production reports to maintain forecast integrity.
Why is the Construction Design Software Market Growing?
The construction design software market is witnessing strong expansion, supported by the rising adoption of digital technologies to improve efficiency, collaboration, and accuracy across construction projects. Increasing complexity in architectural, engineering, and infrastructure development is encouraging the use of advanced design solutions that integrate 3D modeling, real-time collaboration, and data analytics.
The growing emphasis on reducing project delays and cost overruns is driving demand for platforms that offer seamless coordination between stakeholders, enhanced visualization, and predictive planning capabilities. Cloud integration and mobile accessibility are enabling greater flexibility and responsiveness in project execution, while regulatory requirements for sustainability and safety are influencing the adoption of software tools that improve compliance.
Rising investment in smart city infrastructure, coupled with increased demand for modular and prefabricated construction methods, is further accelerating market growth As the construction sector continues its digital transformation, the market is expected to experience sustained momentum, with vendors focusing on enhancing interoperability, scalability, and user experience to meet evolving industry needs.
Segmental Analysis
The construction design software market is segmented by component, deployment, application, end use, and geographic regions. By component, construction design software market is divided into Software and Service. In terms of deployment, construction design software market is classified into Cloud and On-premise. Based on application, construction design software market is segmented into Project management & scheduling, Project design, Safety & reporting, Field service management, Cost accounting, and Others. By end use, construction design software market is segmented into Architects & builders, Remodelers, Designers, and Others. Regionally, the construction design software industry is classified into North America, Latin America, Western Europe, Eastern Europe, Balkan & Baltic Countries, Russia & Belarus, Central Asia, East Asia, South Asia & Pacific, and the Middle East & Africa.
Insights into the Software Component Segment

The software component segment is projected to hold 57.3% of the construction design software market revenue share in 2026, making it the leading component category. This dominance is being driven by the increasing reliance on comprehensive digital platforms that integrate design, visualization, and analytical capabilities. Software solutions enable precise modeling, streamlined workflows, and real-time data sharing among project teams, reducing design errors and enhancing overall project outcomes.
The ability to customize functionalities based on project requirements is improving efficiency and scalability, making software an essential investment for construction firms of all sizes. Continuous advancements in artificial intelligence, building information modeling, and cloud-based collaboration tools are strengthening the appeal of dedicated software solutions.
The segment is further supported by growing demand for interoperability with other construction technologies, such as project management systems and cost estimation tools As organizations continue to prioritize digital adoption to enhance competitiveness and meet tighter project timelines, software is expected to remain the core revenue generator in the market.
Insights into the Cloud Deployment Segment
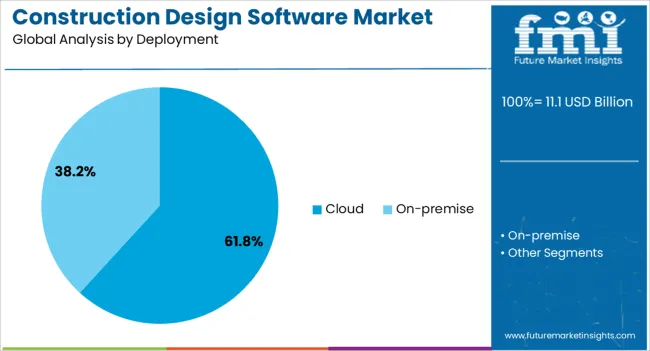
The cloud deployment segment is anticipated to account for 61.8% of the construction design software market revenue share in 2026, establishing itself as the dominant deployment model. Its leadership is being reinforced by the need for flexible, scalable, and cost-effective solutions that support remote collaboration and real-time project updates. Cloud platforms enable seamless data access from multiple locations, ensuring that design modifications and project changes are immediately available to all stakeholders.
This approach reduces the dependency on on-premises infrastructure, lowering maintenance costs while improving accessibility for geographically distributed teams. The ability to integrate cloud-based design tools with other construction technologies, such as IoT-enabled monitoring systems and mobile project management applications, is further enhancing operational efficiency.
Strong data security protocols and compliance with industry regulations are making cloud solutions more attractive to large enterprises and small firms alike. As the industry continues to embrace digital transformation and remote working practices, cloud deployment is expected to retain its leading position in the market.
Insights into the Project Management and Scheduling Application Segment
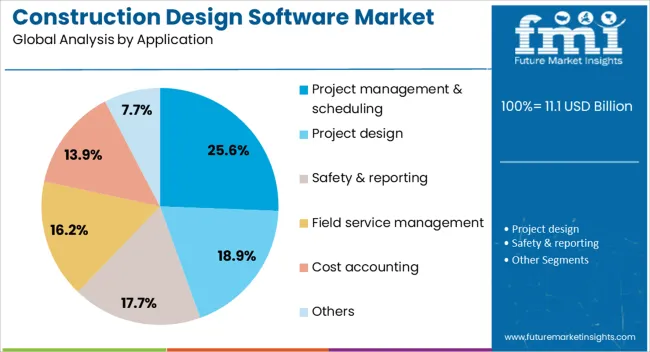
The project management and scheduling application segment is expected to hold 25.6% of the construction design software market revenue share in 2026, making it the leading application area. This dominance is being driven by the growing need to optimize timelines, resource allocation, and task coordination across increasingly complex construction projects. Software tools in this category provide real-time visibility into project progress, allowing stakeholders to identify bottlenecks and implement corrective measures promptly.
The integration of predictive analytics, automated scheduling, and scenario modeling capabilities is enabling more accurate planning and reducing the risk of delays and cost overruns. Adoption is further supported by the rising demand for collaborative platforms that consolidate project data, enabling synchronized decision-making between architects, engineers, and contractors.
Regulatory pressures to meet safety, quality, and sustainability benchmarks are also encouraging the use of advanced scheduling tools to ensure compliance. As project execution speed and efficiency become critical success factors, this application segment is expected to maintain its leadership in the market.
What are the Drivers, Restraints, and Key Trends of the Construction Design Software Market?
The construction design software market is projected to grow steadily as architects, engineers, and contractors prioritize coordinated models, faster approvals, and auditable design intent. Demand is reinforced by BIM authoring, clash detection, and multi-discipline collaboration that shorten design cycles and reduce rework. Opportunities are opening in cloud delivery, open APIs, and packaged workflows for verticals such as healthcare and infrastructure. Trends highlight model-based estimating, 4D scheduling links, and automated code checking. Challenges remain around training costs, license complexity, data standards, and integration with legacy CAD, document control, and on-prem archives across distributed teams.
Demand fueled by digitized workflows and compliance needs
Market demand has been reinforced by the shift to coordinated, model-centric delivery across architecture, structure, and MEP. Owners and public agencies are requesting BIM handover files, federated models, and transparent change histories that support procurement and facilities planning. Designers have relied on parametric modeling, clash detection, and rules-based drafting to reduce RFIs, compress review cycles, and raise drawing consistency. Cloud worksharing and model permissions are being used to align consultants, while reality capture inputs, such as point clouds, improve as-built accuracy. Energy code analyses, life safety layouts, and accessibility checks are being embedded into design reviews, which increases reliance on a single source of truth. The strongest pull comes from measurable rework reduction and cleaner submittals. When model coordination, sheet sets, and quantity takeoff live in the same platform, project teams move from reactive fixes to predictable, documented design control.
Opportunities expanding through integrations and industry playbooks
Opportunities are opening where platforms connect natively with estimating, scheduling, geospatial, and document control, so quantities, schedules, and transmittals flow without rekeying. Vendors are packaging discipline playbooks for hospitals, schools, data centers, and transit that include predefined families, detail libraries, and stamp-ready sheets. API ecosystems are enabling partners to add model checking, code compliance rules, and AR-based coordination, creating add-on revenue and deeper stickiness.
Mid-market firms are responding to tiered subscriptions, pooled licenses, and managed cloud hosting that reduce IT overhead. Training academies, template kits, and data migration services are shortening ramp time and boosting renewal rates. From our perspective, the richest upside comes when design software is sold with outcomes, not modules. Bundling onboarding, audit dashboards, and quarterly model health reviews raises sheet quality, improves clash resolution, and accelerates approvals, which in turn drives portfolio standardization across owner programs and repeat-bid contractors.
Trends leaning toward connected models and analytics
Trends point to connected design environments where authoring, coordination, and review live in a shared data backbone. 4D and 5D links are being adopted, so model objects carry schedule tasks and cost codes, allowing planners and estimators to work directly from design intent. Generative layout tools, parametric families, and automated detailing are reducing manual drafting while preserving standards. Model health analytics, issue heat maps, and element provenance are helping managers detect risk early. Interoperability via IFC, BCF, and open IDs is growing, enabling cross-platform collaboration with fewer exports. Reality capture from laser scans and photogrammetry is tied into fit-out and renovation, improving clash accuracy. In our opinion, the decisive trend is traceability. When every dimension, quantity, and change order links back to a timestamped element, closeout packages and digital handover become routine exports rather than rushed end-of-project compilations that invite disputes.
Challenges around adoption, pricing, and interoperability gaps
Challenges persist in change management as firms transition from file-based CAD to model-based delivery, which can expose skills gaps, template debt, and inconsistent families. Per-user pricing, storage tiers, and premium connectors create budgeting friction on multi-year programs with rotating teams. Integrations with legacy ERPs, DMS archives, and on-prem license servers are often complex, delaying go-live. Data standards vary across owners, causing rework in naming, classification, and level-of-detail, while mixed IFC implementations still generate translation issues. Hardware constraints on older laptops and remote connectivity limits in site offices hamper real-time coordination. Security reviews and data residency rules extend procurement cycles. Many setbacks can be mitigated through fixed-scope onboarding, template governance, offline-first sync, and transparent SKU packaging. Vendors that deliver repeatable implementation playbooks and measurable model health metrics will convert pilots to enterprise standards, while tool-only pitches risk shelfware.
Analysis of Construction Design Software Market By Key Countries

| Country | CAGR |
|---|---|
| China | 12.2% |
| India | 11.3% |
| Germany | 10.4% |
| France | 9.5% |
| UK | 8.6% |
| USA | 7.7% |
| Brazil | 6.8% |
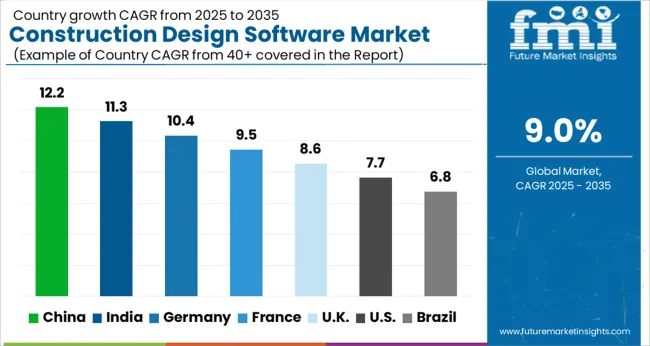
The global construction design software market is projected to grow at 9% from 2026 to 2036. China leads at 12.2%, followed by India at 11.3% and Germany at 10.4%, with the United Kingdom at 8.6% and the United States at 7.7% trailing. Demand is being pulled by model-based workflows, clash coordination, code-checked documentation, and tighter links between design studios and site teams.
Cloud collaboration, CDE alignment, and discipline-specific libraries are being prioritized to compress design cycles and control RFIs. Parametric modeling, rule-based automation, and reality-capture inputs are being adopted to reduce rework. Asia is set to outpace on volume deployments and localized toolsets; Germany is expected to emphasize precision and audit-ready records; the UK is likely to expand through framework standards; the US is projected to progress via steady upgrades across large AEC networks. This report includes insights on 40+ countries; the top markets are shown here for reference.
Sales Outlook for Construction Design Software Market in China
The construction design software market in China is expected to expand at 12.2%. Uptake is being led by public works, transport hubs, industrial parks, and high-rise schemes where coordinated models and compliant drawing sets are required. Cloud tenancy within national regions is being specified, and Chinese-language templates for codes and acceptance criteria are being requested at bid. Domestic suites and international platforms are both being adopted, with API connectors used to link estimation, coordination, and field capture. Prefab-heavy programs favor detailed shop-drawing workflows and clash matrices to protect lead times.
Owner dashboards that monitor model health, issue resolution, and submittal status are being used to rank design teams. Momentum is set to continue as procurement favors standardized deliverables, role-based approvals, and documented audit trails across tier-1 cities and fast-growing provincial capitals.
- Mandarin template packs are being mandated for annotation, dimension styles, and title blocks.
- Data-residency clauses are being used to shortlist vendors for government-led projects.
- QR-linked asset IDs are being embedded in room and equipment schedules for downstream handover.
Demand Analysis for Construction Design Software Market in India
The construction design software market in India is projected to grow at 11.3%. Activity is being driven by metro corridors, airports, data centers, campuses, and mixed-use clusters where model coordination and disciplined submittals reduce delays. Multilingual interfaces, mobile review tools, and geo-referenced markups are being preferred for dispersed teams. Public clients are issuing BEP requirements, level-of-information targets, and standardized naming, with acceptance tied to checkable model outputs. Cloud subscriptions with flexible seats are being adopted by EPC groups handling packages across states. University partnerships are expanding the trained-user pool, accelerating adoption in design studios and contractor design offices. It is expected that consistent gains will be recorded as tender documents enforce template libraries, audit trails, and clear approval paths that link models to payment milestones.
- BEP compliance checks are being attached to pre-award evaluations for large corridors.
- IS code–aligned families and detail libraries are being shared across framework partners.
- WhatsApp-ready review links are speeding redlines and sign-offs for remote stakeholders.
Growth Outlook for Construction Design Software Market in Germany
The construction design software market in Germany is forecast to increase at 10.4%. Demand is being anchored by industrial plants, hospitals, transport nodes, and precision-heavy commercial builds that require DIN-aligned outputs and traceable decisions. OpenBIM workflows with IFC exchanges are being favored to protect interoperability, while EU-region hosting and immutable logs satisfy audit needs. Parametric assemblies, discipline-specific content, and rule sets for model checks are being applied to curb rework. Acoustic, daylight, and code-driven performance studies are being linked to models to defend design choices. With emphasis on verifiable tolerances and certified documentation, Germany is positioned to sustain premium growth through rigorous acceptance protocols and well-governed CDEs that preserve records over long service lives.
- Vendor shortlists are being filtered for native IFC round-tripping without data loss.
- Calibrated QA checkers are being run at gateways to enforce DIN naming and status maps.
- EU cloud whitelists are being enforced for sensitive health and public projects.
Future Analysis for Construction Design Software Market in the United Kingdom
The construction design software market in the UK is anticipated to rise at 8.6%. Refurb programs, education estates, healthcare builds, and build-to-rent schemes are requiring ISO 19650 alignment, model-based coordination, and structured approval chains. CDEs with common naming, revision control, and transmittals are being used to reduce dispute risk. Designers are mapping RIBA stages to model gateways and deliverable checklists, while clients request evidence packs that tie drawings, models, and site photos. Offsite-friendly detailing and clash matrices are being emphasized to protect manufacture slots. Steady growth will be maintained as framework procurement standardizes template packs by trade and as owners insist on dashboards that surface issue aging and readiness for handover.
- RIBA stage checklists are being embedded to lock model gate reviews.
- Room data sheets are being linked to schedules for faster fixtures and finishes sign-off.
- Heritage refurb projects are favoring laser-scan overlays to control tolerance risk.
Opportunity Analysis for Construction Design Software Market in the United States

The construction design software market in the United States is projected to grow at 7.7%. Demand is being supported by healthcare, labs, logistics hubs, and corporate interiors where clash resolution, disciplined submittals, and defensible change records are essential. Large AEC networks are standardizing cloud hubs for model sharing, issue tracking, and automated audits. Interoperability across major suites, rule-based generative options, and reality-capture inputs are being adopted to compress schedules. Owners are requesting dashboards that connect model status to cost exposure and long-lead procurement. It is judged that migration from fragmented tools to integrated ecosystems will proceed steadily as GCs and design firms prioritize repeatable processes, cross-discipline accountability, and clean handovers to facilities teams.
- Digital twins are being referenced to align as-built records with O&M deliverables.
- API connectors are linking models to estimating, procurement, and schedule risk tools.
- Enterprise license pools with burst rendering are cutting bottlenecks on deadlines.
Competitive Landscape of Construction Design Software Market

Competition in construction design software has been organized around BIM depth, open formats, and clear brochure storytelling. Autodesk positions suites that span concept to detailing, with brochures that present Revit, Civil 3D, and AutoCAD as a coordinated toolchain with model coordination and reality capture support. Bentley Systems frames MicroStation and discipline twins in literature that stresses precision modeling, federated data, and IFC interoperability.
Trimble promotes constructible workflows in brochures that link SketchUp and Tekla to layout and fabrication, turning design intent into shop ready outputs. Vectorworks highlights flexible modeling, integrated rendering, and landscape workflows with concise comparison tables. RIB Software SE centers brochures on 5D planning, cost linked models, and quantity fidelity. Oracle sets Aconex and design collaboration as a governed common data environment. SAP SE positions integration with enterprise records and approvals. Constellation Software groups niche authoring and coordination brands under steady release roadmaps. Microsoft appears as the platform layer in brochures that feature Azure based CDE partners, Power BI reporting, and Teams driven design reviews. Strategy has been executed through documentation that removes doubt for principals, BIM managers, and estimators.
Key Players in the Construction Design Software Market
- Autodesk
- Bentley Systems
- Constellation Software
- Microsoft
- Oracle
- Rib Software Se
- Sage Group
- SAP Se
- Trimble
- Vectorworks
Scope of the Report

| Metric | Value |
|---|---|
| Quantitative Units | USD 12.10 Billionn to USD 28.64 Billion, at a CAGR of 9.00% |
| Market Definition | Construction design software covers BIM modeling platforms, project scheduling tools, structural and MEP design engines, safety compliance modules, and field management applications purpose-built for the planning, design, and coordination of building and civil engineering projects. |
| Component Segmentation | Software, Service |
| Deployment Segmentation | Cloud, On-premise |
| Application Segmentation | Project Management & Scheduling, Project Design, Safety & Reporting, Field Service Management, Cost Accounting, Others |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East & Africa |
| Countries Covered | China, India, Germany, France, UK, USA, Brazil, and 40 plus countries |
| Key Companies Profiled | Autodesk, Bentley Systems, Constellation Software, Microsoft, Oracle, Rib Software SE, Sage Group, SAP SE, Trimble, Vectorworks |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid bottom-up and top-down modeling validated against primary research inputs and publicly available industry data. |
Construction Design Software Market by Segments
Component:
- Software
- Service
Deployment:
- Cloud
- On-premise
Application:
- Project management & scheduling
- Project design
- Safety & reporting
- Field service management
- Cost accounting
- Others
End Use:
- Architects & builders
- Remodelers
- Designers
- Others
Region:
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Bibliography
- Clean Energy Wire. (2026, March 19). Q&A: Germany's EUR 500bln special fund for infrastructure and climate neutrality.
- Destatis (Federal Statistical Office of Germany). (2026, May 22). 18,0 % weniger fertiggestellte Wohnungen im Jahr 2025.
- European Commission. (Accessed 2026, November 13). Construction Products Regulation 2024 revision.
- ifo Institute. (2025, October 14). Special Fund Under Scrutiny: Economists Express Doubts.
- U.S. Census Bureau. (2026, November 2). Monthly Construction Spending, September 2026.
- U.S. Census Bureau. (2026, October 20). Monthly New Residential Construction, September 2026.
Table of Content
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
Read More...
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Company Annual and Sustainability Reports
- Peer-reviewed Journals and Academic Literature
- Corporate Websites, Product Literature, and Technical Notes
- Earnings Decks and Investor Briefings
- Statutory Filings and Regulatory Disclosures
- Technical White Papers and Standards Notes
- Trade Journals, Industry Magazines, and Analyst Briefs
- Conference Proceedings, Webinars, and Seminar Materials
- Government Statistics Portals and Public Data Releases
- Press Releases and Reputable Media Coverage
- Specialist Newsletters and Curated Briefings
- Sector Databases and Reference Repositories
- FMI Internal Proprietary Databases and Historical Market Datasets
- Subscription Datasets and Paid Sources
- Social Channels, Communities, and Digital Listening Inputs
- Additional Desk Sources
- Expert Input and Fieldwork (Primary Evidence)
- Primary Modes
- Qualitative Interviews and Expert Elicitation
- Quantitative Surveys and Structured Data Capture
- Blended Approach
- Why Primary Evidence is Used
- Field Techniques
- Interviews
- Surveys
- Focus Groups
- Observational and In-context Research
- Social and Community Interactions
- Stakeholder Universe Engaged
- C-suite Leaders
- Board Members
- Presidents and Vice Presidents
- R&D and Innovation Heads
- Technical Specialists
- Domain Subject-matter Experts
- Scientists
- Physicians and Other Healthcare Professionals
- Governance, Ethics, and Data Stewardship
- Research Ethics
- Data Integrity and Handling
- Primary Modes
- Tooling, Models, and Reference Databases
- Desk Research Programme (Secondary Evidence)
- Data Engineering and Model Build
- Data Acquisition and Ingestion
- Cleaning, Normalisation, and Verification
- Synthesis, Triangulation, and Analysis
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics
- Drivers
- Restraints
- Opportunity
- Trends
- Scenario Forecast
- Demand in Optimistic Scenario
- Demand in Likely Scenario
- Demand in Conservative Scenario
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter’s Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Market Dynamics
- Global Market Analysis 2021 to 2025 and Forecast, 2026 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis 2021 to 2025 and Forecast 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Components
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Components , 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Components , 2026 to 2036
- Software
- Service
- Software
- Y-o-Y Growth Trend Analysis By Components , 2021 to 2025
- Absolute $ Opportunity Analysis By Components , 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Deployment
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Deployment, 2026 to 2036
- Cloud
- On-premise
- Cloud
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Application
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Project management & scheduling
- Project design
- Safety & reporting
- Field service management
- Cost accounting
- Others
- Project management & scheduling
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Region
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- Latin America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- Western Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- Eastern Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- East Asia Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- Middle East & Africa Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Components
- By Deployment
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Components
- By Deployment
- By Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- Turkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Components
- By Deployment
- By Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Components
- By Deployment
- By Application
- Competition Analysis
- Competition Deep Dive
- Autodesk
- Overview
- Product Portfolio
- Profitability by Market Segments (Product/Age /Sales Channel/Region)
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bentley Systems
- Constellation Software
- Microsoft
- Oracle
- Rib Software Se
- Sage Group
- SAP Se
- Trimble
- Vectorworks
- Autodesk
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 29: Middle East & Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East & Africa Market Value (USD Million) Forecast by Components , 2021 to 2036
- Table 31: Middle East & Africa Market Value (USD Million) Forecast by Deployment, 2021 to 2036
- Table 32: Middle East & Africa Market Value (USD Million) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Components
- Figure 6: Global Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Deployment
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Components
- Figure 26: North America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Deployment
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Components
- Figure 36: Latin America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Deployment
- Figure 39: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Components
- Figure 46: Western Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Deployment
- Figure 49: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Components
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Deployment
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Components
- Figure 66: East Asia Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Deployment
- Figure 69: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Components
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Deployment
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 82: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East & Africa Market Value Share and BPS Analysis by Components , 2026 and 2036
- Figure 84: Middle East & Africa Market Y-o-Y Growth Comparison by Components , 2026-2036
- Figure 85: Middle East & Africa Market Attractiveness Analysis by Components
- Figure 86: Middle East & Africa Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 87: Middle East & Africa Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 88: Middle East & Africa Market Attractiveness Analysis by Deployment
- Figure 89: Middle East & Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 90: Middle East & Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 91: Middle East & Africa Market Attractiveness Analysis by Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the construction design software market in 2026?
Future Market Insights estimates the global construction design software market at USD 12.10 billion in 2026, up from USD 11.10 billion in 2025.
How fast is the construction design software market expected to grow through 2036?
FMI projects a 9.0% CAGR from 2026 to 2036, taking the global construction design software market to USD 28.64 billion by 2036 and generating USD 16.54 billion in incremental revenue.
Which product type leads the construction design software market?
Software licenses and subscriptions lead with 57.3% of 2026 revenue, and their global revenue share is projected to rise to 60.5% by 2036 as cloud subscriptions replace one-time implementation work.
Which variant leads the construction design software market?
Project management and scheduling software tools hold 25.6% of 2026 revenue (expanding at an 8.2% CAGR), while field service management software tools are projected to grow fastest at 11.6% per year, followed by safety and reporting software tools at 10.7%.
Which distribution channel leads the construction design software market?
Direct enterprise sales account for 41.0% of 2026 sales, whereas cloud marketplaces are expected to grow fastest at 12.4% per year from 2026 to 2036.
Which country is the largest construction design software market?
The United States leads the construction design software market, capturing 30.0% of global revenue in 2026 (USD 3.63 billion), followed by Germany at 7.5% (USD 907.5 million) and the United Kingdom at 6.0% (USD 726.0 million).
Which countries are expected to grow fastest in the construction design software market?
Germany and France are projected to grow fastest, expanding at 10.4% and 9.5% CAGRs from 2026 to 2036, followed by the United Kingdom at 8.6%.
What drives demand for construction design software?
Demand for construction design software rests on design firms and contractors that share digital building models across project teams, reinforced by the revised EU Construction Products Regulation, which began to apply in January 2026 and moves product data toward machine-readable digital passports.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
