

- Market Size (2026)
- USD 98.5 Bn
- Forecast (2036)
- USD 381.5 Bn
- CAGR (2026 to 2036)
- 14.5%
How big is Digital Transformation in Healthcare Market in 2026?
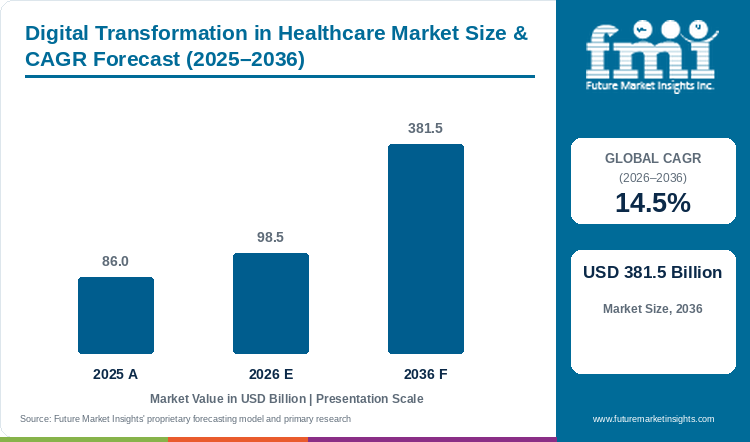
Demand is projected to expand at 14.5% CAGR from 2026 to 2036. Market value rises from USD 86.03 billion in 2025 to USD 98.5 billion in 2026 and USD 381.5 billion by 2036.
Spending follows the practical work of connecting records, staff and patient services within organizations whose starting points differ considerably. Japan's ministry identifies gaps in electronic-record adoption among smaller providers. [1] These conditions create distinct purchases, ranging from a manageable first record system to an extension of an established hospital workflow. Implementation and continuing assistance are consequently important alongside software functionality, particularly where clinical staff need to use the system during routine care. India's reported use of ABDM-enabled software across facilities offers another view of this deployment activity. [2] Through 2036, suppliers can develop stronger relationships by making digital systems workable within the provider's resources, with shared information and usable interfaces helping connect the investment to ordinary clinical and administrative tasks.
Key Market Trends & Insights
- Providers introducing a first electronic record need a different delivery arrangement from hospitals extending an established platform. [1][3]
- Professional use of shared information gives implementation and continuing support a practical place in digital-health purchasing. [3]
- Software functions become more useful when they fit the staff and administrative processes that sustain ordinary care.
Regional Highlights
- India's ABDM-enabled software base gives suppliers a practical route into provider workflows, with official reporting identifying more than 159,000 facilities using such software by February 2025 (FMI outlook: 15.8% CAGR, 2026 to 2036).
- Large provider networks and individual hospitals create different delivery requirements in China's healthcare digital-transformation market (FMI outlook: 15.2% CAGR, 2026 to 2036).
- The United States market is projected to grow at 14.2% CAGR from 2026 to 2036.
Market Size & Forecast
Table 1: Market Size and Forecast for Digital Transformation in Healthcare Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 86.03 billion |
| 2026 market value | USD 98.5 billion |
| 2036 market value | USD 381.5 billion |
| CAGR 2026 to 2036 | 14.5% |
| Revenue increase 2026 to 2036 | USD 283 billion |
| Market expansion 2026 to 2036 | 3.87 times |
The market covers implemented or funded digital-care systems, electronic records and workflow infrastructure. System launch and availability are distinguished from active provider or patient use.
Providers adding outside records to a clinical workflow need healthcare interoperability solutions that connect the participating systems and make the information accessible to the staff using it.
Provider adoption and the practical use of digital records
Official provider evidence identifies several stages of digital development, from first electronic-record adoption to the use of shared information across care services. These observations explain why implementation needs differ by provider and why further purchasing can arise within an already equipped hospital. [1][2][3]
Table 2: Industry evidence relevant to the digital transformation in healthcare market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Japan | Electronic-record adoption discussion | Smaller providers create a distinct first-implementation requirement | [1] |
| India | ABDM-enabled software use | More than 159,000 facilities reported using enabled software by February 2025 | [2] |
| United Kingdom | Notts shared record | More than one million views reported by September 2026 | [3] |
Analyst Perspective
"Healthcare digitisation becomes part of daily operations when staff can retrieve and use information during their work. Providers need connected applications and a manageable implementation, with training and continuing support helping the organisation keep its records useful as services and participating teams change."
- Sudip Saha, Co-founder, Future Market Insights
How is the Digital Transformation in Healthcare Market segmented?
The market is segmented by Solution, End User, and Region.
Solution coverage separates Software and Service. End User comprises Hospitals & Clinics, Pharma Companies, Life Science & Biotech Companies, and Healthcare Insurance Providers. Software supplies the digital functions used within those organizations, while services support delivery and continuing operation; each end-user group brings a different clinical, research or administrative workflow to the purchasing decision.
Why does the Software segment account for the larger share of solution demand?
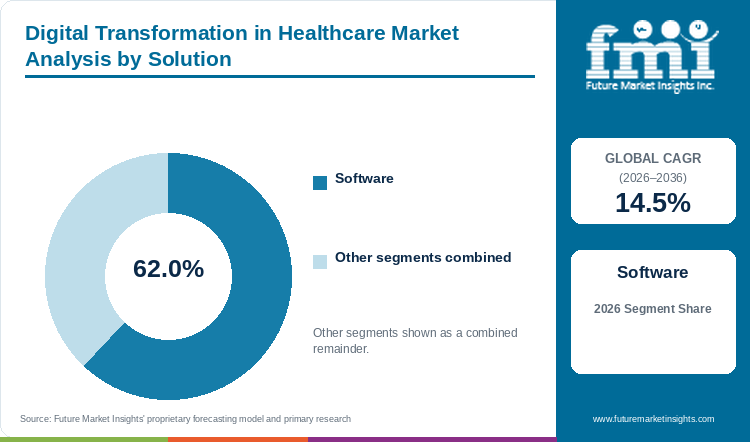
Table 3: Solution Share for Digital Transformation in Healthcare Market (percentage share), 2026
| Solution | Estimated share (2026) |
|---|---|
| Software | 62.0% |
| Service | 38.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Digital Transformation in Healthcare Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 14.5% |
| Profiled solution segment | Software |
Software organizes the records, tasks and information that staff need during care, giving it a central role when a provider introduces or expands a digital workflow. A hospital can use an established record platform as the foundation for additional patient-facing capabilities, while a smaller clinic may need a more manageable first implementation. Japan's electronic-record adoption discussion illustrates the purchasing requirements of smaller providers. [1] The Software segment is projected to account for 62.0% of solution demand in 2026 as these requirements support both initial systems and continuing development. Buyers evaluate the functions together with usability and the work required to maintain them, making a clear fit with ordinary clinical and administrative tasks important to the supplier's position.
The Software segment is projected to account for 62.0% of solution demand in 2026.
- Software: 62.0% of solution demand (2026 estimate), with Service accounting for the remaining 38.0%.
- Provider size and existing systems shape the software purchase, ranging from a first electronic record to an extension of an established hospital workflow. [1][3]
What sustains the substantial role of hospitals and clinics?
Table 5: End User Share for Digital Transformation in Healthcare Market (percentage share), 2026
| End User | Estimated share (2026) |
|---|---|
| Hospitals & Clinics | 50.0% |
| Other end users | 50.0% |
| Total | 100.0% |
Hospitals and clinics bring several care and administrative functions into the same organization, creating a continuing need for records and systems that staff can use together. The purchase can involve patient access, clinical information and the exchange of records with other providers, with implementation support helping the organization connect those functions to its existing work. The Hospitals & Clinics segment is projected to represent 50.0% of end-user demand in 2026 as providers invest across those requirements. The Notts Care Record offers a concrete example of information being used across a regional care service after launch. [3] Buyers consequently value a clear delivery arrangement and practical assistance, especially where a digital change affects several teams whose daily work depends on the same information.
The Hospitals & Clinics segment is projected to account for 50.0% of end user demand in 2026.
- Hospitals & Clinics: 50.0% of end-user demand (2026 estimate), reflecting the range of digital functions purchased within provider organizations.
- Shared-record use in the Notts service illustrates the operational importance of making information accessible within care workflows after a system is introduced. [3]
- Once digital records become part of ordinary work, healthcare business intelligence can help managers examine activity and resources, linking the operating information base with the decisions used to organize care.
What are the drivers, restraints, and opportunities in the Digital Transformation in Healthcare Market?
Digital spending becomes useful when staff can apply the available information during ordinary care, making implementation and continuing support central to the purchasing decision. Some providers need an accessible first record system, while others need functions that connect an established platform with more of the care pathway. These different starting points create distinct opportunities for software and service suppliers. [1][3]
Driver
Providers need usable information across care and administration, creating demand for systems that connect records, staff and patient services. Japan's adoption discussion shows a first-implementation requirement among smaller providers. [1] These different starting points sustain software and service opportunities, with the value of a purchase tied to the workflow it helps the organization operate.
Restraint
Introducing a digital system requires staff time, clear responsibilities and coordination with existing records and applications. A provider can therefore face a substantial operating commitment alongside the software price, particularly when several teams depend on the same information. Suppliers need to make the delivery plan and continuing support manageable, since difficult interfaces or poorly integrated tasks can slow routine use and reduce the value the buyer receives.
Opportunity
Implementation and continuing assistance give vendors a route to strengthen provider relationships after the initial software purchase. India's ABDM-enabled facility base and the operating use of the Notts shared record illustrate settings in which information services become part of everyday care. [2][3] Suppliers can address those requirements through practical integration, training and support that fit the provider's resources and help staff use the selected digital functions consistently.
A mobile clinic needs records that remain useful between outreach visits and follow-up care, giving software suppliers a practical deployment setting within a service that moves between locations.
Which country CAGRs are profiled in the Digital Transformation in Healthcare Market?
Table 6: Country CAGR Comparison for Digital Transformation in Healthcare Market (CAGR percentage), 2026 to 2036
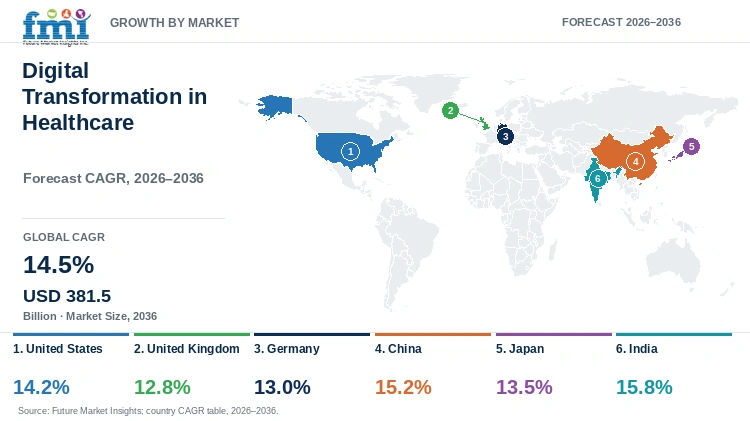
| Country | CAGR |
|---|---|
| United States | 14.2% |
| United Kingdom | 12.8% |
| Germany | 13.0% |
| China | 15.2% |
| Japan | 13.5% |
| India | 15.8% |
Country-wise Analysis
United States Digital Transformation in Healthcare Market Outlook (2026 to 2036)
A supplier's proposition needs to explain how a proposed function fits staff responsibilities and the patient's route through care. Implementation and ongoing assistance matter when several systems contribute information, giving vendors an opportunity to strengthen an established relationship through useful extensions and manageable integration.
United Kingdom Digital Transformation in Healthcare Market Outlook (2026 to 2036)
Regional record-sharing gives UK providers a practical setting in which the value of a digital investment develops through professional use. The Notts Care Record moved from its July 2025 launch to more than one million views by September 2026, providing an operating example of information accessed across a defined care service. [3] Purchasing therefore includes the delivery and support needed to make information usable across teams. Suppliers able to explain how a system fits the local care pathway can address both the initial implementation and the continuing work of maintaining a dependable service.
Germany Digital Transformation in Healthcare Market Outlook (2026 to 2036)
German provider organizations need digital systems that remain useful as information moves between clinical and administrative tasks, giving implementation and interoperability a practical place in purchasing. A hospital expanding an established platform has to coordinate staff responsibilities, interfaces and access to the information required during care, while a smaller provider faces a different resource commitment. The commercial opportunity consequently includes the work of connecting an investment with the provider's existing processes. Vendors can strengthen their position through clear deployment responsibilities and continuing assistance, helping the organization maintain a usable system while additional functions and information sources are introduced.
China Digital Transformation in Healthcare Market Outlook (2026 to 2036)
Large provider networks and individual hospitals create different delivery requirements in China's healthcare digital-transformation market. A system intended for several locations needs a consistent approach to records and access, while an individual department may prioritize a specific clinical or administrative task. Suppliers therefore need to connect the proposed software with the staff and information flows involved in its use, giving implementation support a continuing commercial role. A hospital can gain a more useful service when responsibilities for interfaces, updates and assistance are clear, especially as further applications are added to an established platform over time.
Japan Digital Transformation in Healthcare Market Outlook (2026 to 2036)
Smaller Japanese providers face a different starting point from hospitals extending an established digital platform. The ministry's electronic-record presentation identifies substantial non-adoption among clinics and hospitals below 200 beds and discusses lower-cost cloud-native systems as a way to support introduction. [1] The purchasing requirement includes the staff time and support needed during implementation, making simplicity and ongoing assistance commercially important. Vendors can address that need through a defined first deployment that fits the provider's resources, with additional functions introduced as users become familiar with the system and the organization develops its digital workflows.
India Digital Transformation in Healthcare Market Outlook (2026 to 2036)
India's ABDM-enabled software base gives suppliers a practical route into provider workflows, with official reporting identifying more than 159,000 facilities using such software by February 2025. [2] The opportunity extends into the work required to maintain records and use digital functions consistently during care, particularly where smaller facilities have limited implementation resources. A clear service arrangement can help organizations introduce software and connect it with the information they need to exchange. Suppliers therefore compete through usable interfaces, practical training and continuing support, with the provider's ordinary clinical and administrative tasks shaping the functions it chooses to purchase.
Who are the notable companies in the Digital Transformation in Healthcare Market?
Epic; Oracle Health; Microsoft; Philips; Siemens Healthineers
Healthcare software companies compete through the operating work their systems support, from creating a first electronic patient record to extending a hospital's established information environment. Record-platform suppliers, infrastructure providers and healthcare-technology companies enter these decisions from different commercial positions, giving implementation and interfaces a substantial role in selection. Japan's published digitization evidence and the use recorded by the Nottinghamshire shared-care record illustrate different stages of that purchasing environment. [1][3] A supplier's opportunity develops as its proposed system fits the provider's staff, information and care processes.
Competitive Benchmarking: Digital Transformation in Healthcare Market
Table 7: Competitive positioning for the digital transformation in healthcare market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Epic | Healthcare record and workflow software | Provider implementation and routine use |
| Oracle Health | Healthcare information systems | Record-system delivery and integration |
| Microsoft | Cloud and healthcare technology infrastructure | Infrastructure versus clinical-application scope |
| Philips | Healthcare systems and informatics | Defined care workflow and deployment responsibilities |
| Siemens Healthineers | Healthcare technology and digital applications | Application scope and provider integration |
Key Developments in the Digital Transformation in Healthcare Market
- The Notts Care Record exceeded one million views by September 2026 following its July 2025 launch, illustrating professional use within a regional shared-information service. [3]
- Japan's ministry discussed electronic-record adoption gaps among smaller providers and a lower-cost cloud-native direction in its March 2026 presentation. [1]
- India reported more than 159,000 facilities using ABDM-enabled software by February 2025, providing a concrete view of the implemented software base. [2]
Key Players in the Digital Transformation in Healthcare Market
Healthcare record and workflow software
- Epic
Healthcare information systems
- Oracle Health
Cloud and healthcare technology infrastructure
- Microsoft
Healthcare systems and informatics
- Philips
Healthcare technology and digital applications
- Siemens Healthineers
Digital Transformation in Healthcare Market Report Scope
Table 8: Report Scope for Digital Transformation in Healthcare Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | The market covers implemented or funded digital-care systems, electronic records and workflow infrastructure. System launch and availability are distinguished from active provider or patient use. |
| Quantitative units | USD billion |
| Historical reference year | 2025 |
| Forecast period | 2026 to 2036 |
| Market breakdown | Solution; End User; Region |
| Countries profiled | United States; United Kingdom; Germany; China; Japan; India |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Key companies profiled | Epic; Oracle Health; Microsoft; Philips; Siemens Healthineers |
Digital Transformation in Healthcare Market Research Methodology
Table 9: Research Methodology for Digital Transformation in Healthcare Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | The market covers implemented or funded digital-care systems, electronic records and workflow infrastructure. System launch and availability are distinguished from active provider or patient use. |
| Secondary research | Public institutional reports, regulator publications, technical literature and supplier documentation provide the operating context for the market. |
| Quantitative coverage | Market values are expressed in USD billion, with a 2025 base value, a 2026 estimate and a projection for 2036. |
| Segment and country assessment | Segment categories retain distinct demand measures, while each country profile is linked with its estimated CAGR for 2026 to 2036. |
| Company comparison | Representative participants are compared by the product or service offered, the customer application and the implementation requirements relevant to procurement. |
Digital Transformation in Healthcare Market by Segments
Digital Transformation in Healthcare Market segmented by Solution:
- Software
- Service
Digital Transformation in Healthcare Market segmented by End User:
- Hospitals & Clinics
- Pharma Companies
- Life Science & Biotech Companies
- Healthcare Insurance Providers
Digital Transformation in Healthcare Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Ministry of Health, Labour and Welfare. 12 March 2026. Promoting electronic medical-record adoption
- [2] Ministry of Health and Family Welfare / PIB. 11 February 2025. Implementation of Ayushman Bharat Digital Mission
- [3] NHS Digital Notts. 28 September 2026. Notts Care Record exceeds one million views
This Report Answers
- How large is the Digital Transformation in Healthcare Market in 2026?
- What is the growth outlook for the Digital Transformation in Healthcare Market through 2036?
- What is the 2026 share of Software?
- What is the 2026 share of Hospitals & Clinics?
- Which profiled market has the highest projected growth?
- Who are the notable participants in the Digital Transformation in Healthcare Market?
Frequently Asked Questions
How large is the Digital Transformation in Healthcare Market in 2026?
The market is estimated at USD 98.5 billion in 2026, compared with USD 86.03 billion in 2025.
What is the growth outlook for the Digital Transformation in Healthcare Market through 2036?
The market is projected to reach USD 381.5 billion by 2036, representing a CAGR of 14.5% from 2026 to 2036.
What is the 2026 share of Software?
The Software segment is estimated to account for 62% of solution demand in 2026. Provider size and existing systems shape the software purchase, ranging from a first electronic record to an extension of an established hospital workflow. [1][3]
What is the 2026 share of Hospitals & Clinics?
The Hospitals & Clinics segment is estimated to account for 50% of end user demand in 2026. Shared-record use in the Notts service illustrates the operational importance of making information accessible within care workflows after a system is introduced. [3]
Which profiled market has the highest projected growth?
India has the highest projected rate among the markets profiled, at 15.8% CAGR from 2026 to 2036.
Who are the notable participants in the Digital Transformation in Healthcare Market?
Representative participants include Epic, Oracle Health, Microsoft, Philips, Siemens Healthineers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Solution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Solution, 2026 to 2036
- Software
- Service
- Y-o-Y Growth Trend Analysis By Solution, 2021 to 2025
- Absolute $ Opportunity Analysis By Solution, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Hospitals & Clinics
- Pharma Companies
- Life Science & Biotech Companies
- Healthcare Insurance Providers
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Solution
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Solution
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Epic
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Oracle Health
- Microsoft
- Philips
- Siemens Healthineers
- Epic
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


