

- Market Size (2026)
- USD 272.2 Bn
- Forecast (2036)
- USD 501.5 Bn
- CAGR (2026 to 2036)
- 6.3%
How big is Automotive Tires Market in 2026?
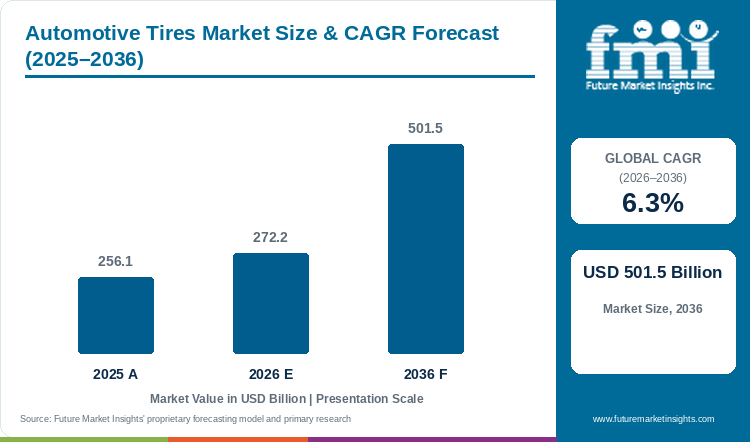
The automotive tires market is estimated at USD 256.1 billion in 2025 and is projected to reach USD 272.2 billion in 2026. Sales of automotive tires are likely to grow at a 6.3% CAGR over 2026 to 2036 and reach USD 501.5 billion by 2036.
Demand for automotive tires in 2025 is estimated near USD 256.1 billion, and FMI projects USD 272.2 billion for 2026. Through 2036 the automotive tires market is expected to expand at a 6.3% CAGR to USD 501.5 billion, as heavier electric cars and larger rims raise the value of each tire sold. Electric models are reaching more driveways each month. SMMT counted 99,201 new battery electric cars in the United Kingdom in September 2026, a 28.3% share of registrations.[1] Battery packs add weight and instant torque, so tread wears sooner and drivers return to the dealer for EV-rated replacements.
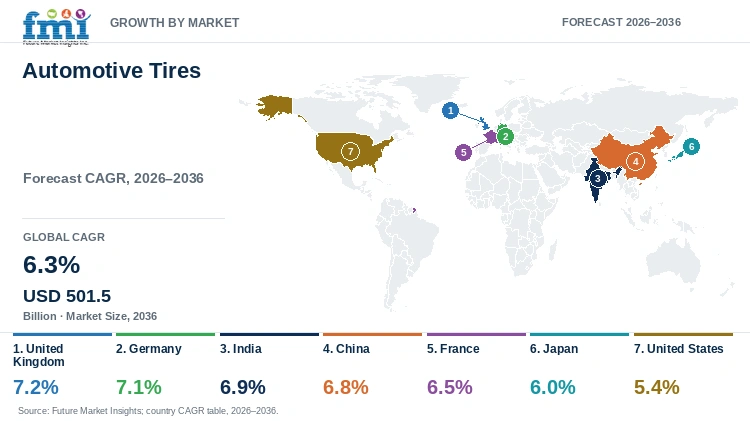
Battery car adoption puts the United Kingdom on a projected 7.2% CAGR through 2036, well ahead of the 5.4% expected for the United States. British buyers registered 454,947 battery electric cars in the first nine months of 2026, 26.2% of the market, and the Electric Car Grant supported September demand.[1] Each of those cars needs low rolling resistance, high load tires, which sell above standard patterns. The U.S. Tire Manufacturers Association expects total U.S. shipments to fall 1.8% to 330.3 million units in 2026.[2]
American drivers keep cars longer on long-tread all-season tires, so replacement intervals stretch. Growth in the United States will come from larger pickup and SUV sizes, and the British fleet will move faster to EV-specific tires.
Key Market Trends & Insights
- Four tires per car keep passenger vehicles ahead on vehicle type at an expected 48% in 2026, and commercial vehicles follow near 31.6%. Continental named a higher share of 18-inch and larger tires as a profit driver in Q2 2026.[3]
- Radial tires are projected to hold 62% of 2026 sales by tire structure, with bias and bias-ply designs at about 38% in two-wheeler, farm and off-road use.
- Within sales channel, the replacement and aftermarket route is likely to account for about 72.5% of 2026 sales. USTMA forecasts 218.3 million passenger replacement shipments in the United States for 2026, against 41.0 million original equipment units.[2]
- All-season patterns are estimated to lead tire type with 44.6% in 2026, as drivers in mild climates keep one set fitted all year, and summer and performance tires follow at roughly 27.9%.
Regional Highlights
- The United Kingdom grows at the quickest pace in the country table on FMI's forecast, a 7.2% CAGR, 0.9 points over the automotive tires market rate of 6.3%, as battery electric registrations rise.
- Premium carmakers keep Germany close behind on 7.1%. India, on 6.9%, and China, on 6.8%, follow as vehicle output expands, and France holds 6.5% on the back of a large replacement base. Mature fleets leave Japan on 6% and the United States on 5.4%, the two lowest rates.
- The European replacement market for passenger car and light commercial vehicle tires grew 3% in Q2 2026, and the North American market fell 1%, Continental reported.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Tires Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 256.1 billion |
| Estimated Market Size in 2026 | USD 272.2 billion |
| Projected Market Size by 2036 | USD 501.5 billion |
| CAGR, 2026 to 2036 | 6.3% |
| Added Revenue, 2026 to 2036 | USD 229.3 billion |
| Market Expansion Multiple | 1.8x |
Tire orders come in two streams with different timing. Carmakers call off original equipment tires a few weeks ahead of each build, and dealers restock replacement tires before the winter and summer changeovers. Michelin reported a 0.9% negative volume effect in H1 2026 from weaker original equipment and Tier-3 brands, and MICHELIN brand replacement volumes rose 5%.[4] Truck fleets retread worn casings to cut cost, and the tire retreading market, at a 2.8% CAGR, keeps some truck demand away from new tires. An added USD 229.3 billion of tire sales is expected by 2036 in FMI's model, so the automotive tires market will be about 1.8 times the 2026 size. Weak car production in the Americas is the main near-term risk, as original equipment volumes fall first.
Replacement Cycles, Rim Size and Tariffs
Replacement is the steadier stream. Bridgestone estimated that the North American replacement market fell 5% for passenger and light truck tires in H1 2026 and 13% for truck and bus tires, and own replacement sales were down 3% and 1%.[5] Goodyear reported Americas replacement volumes 13% lower in Q2 2026, and original equipment volumes 8.7% higher.[6] Dealers are running lean stock after a strong 2025, so replacement orders will recover when inventory normalises.
Larger rims and tariffs are changing the value of each tire. Pirelli said High Value products reached 82% of total sales in H1 2026, and 90% of new homologations were for rim sizes of 19 inches and above.[7] Goodyear cited USD 100 million of higher tariffs and other costs in the Q2 2026 operating income bridge.[6] Higher price per tire is carrying growth in mature markets, and unit counts are growing mainly in emerging countries.
Table 2: Replacement, Rim Size and Cost Indicators for the Automotive Tires Market (units, shares and costs), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| UK battery electric car registrations, September 2026 | 99,201; 28.3% share | EV-rated tire demand | [1] |
| US total tire shipments forecast, 2026 | 330.3 million units; down 1.8% | Mature market volume | [2] |
| Bridgestone North American replacement market, H1 2026 | Passenger and light truck down 5% | Replacement cycle stretch | [5] |
| Goodyear tire unit volume, Q2 2026 | 36.5 million; down 4% | Manufacturer volume trend | [6] |
| Pirelli High Value share of total sales, H1 2026 | 82% | Large-rim premium mix | [7] |
| Continental Tires adjusted EBIT margin, Q2 2026 | 15.3% | Value of 18-inch and larger sizes | [3] |
| Yokohama tire business sales, H1 2026 | Nearly USD 3.7 billion; up 10.8% | Premium and SUV tire growth | [8] |
Analyst Perspective
“Heavy electric cars and 19-inch rims will, I believe, decide which tire makers earn the most over the next ten years, since each replacement set now costs more and wears sooner. Makers with EV-rated, large-rim ranges in stock at dealers are unlocking a richer replacement cycle for battery cars, and I expect them to gain share in the United Kingdom and Germany first.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive tires market segmented?
The market is segmented into vehicle type, tire structure, sales channel, tire type, and region. Passenger vehicles are expected to lead vehicle type with 48% share in 2026, and radial construction leads tire structure with 62%.
By vehicle type: passenger vehicle, commercial vehicle (light, medium and heavy), two-wheeler, and off-the-road (OTR).
By tire structure: radial and bias/bias-ply.
By sales channel: OEM and replacement/aftermarket.
By tire type: all-season, summer/performance, winter, and ultra-high-performance (UHP).
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do passenger vehicles lead automotive tires sales by vehicle type?
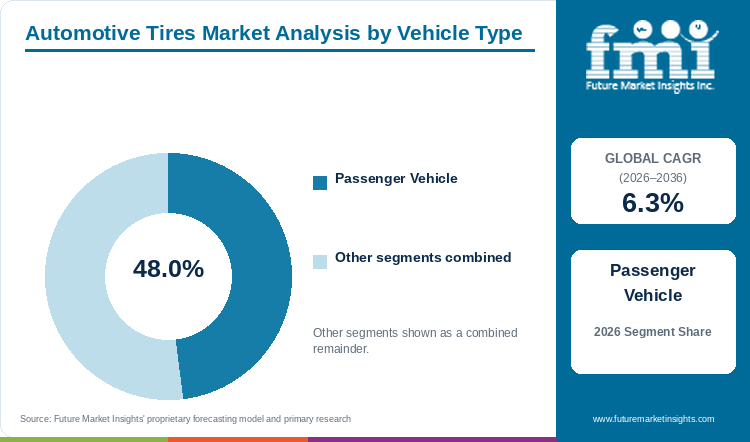
Passenger vehicles are expected to lead vehicle type sales with 48% share in 2026, ahead of commercial vehicles at an estimated 31.6%, two-wheelers at about 12.9% and off-the-road vehicles near 7.5%.
Table 3: Vehicle Type Share for the Automotive Tires Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Vehicle | 48% |
| Commercial Vehicle | 31.6% |
| Two-Wheeler | 12.9% |
| Off-the-Road (OTR) | 7.5% |
| Total | 100.0% |
Table 4: Vehicle Type Leadership and Market Growth for the Automotive Tires Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.3% |
| Leading Segment | Passenger Vehicle |
With the car parc the largest fleet on the road and four tires on every car, passenger vehicles are expected to lead with a 48% slice of 2026 sales. Commercial vehicles, about 31.6%, buy bigger and costlier tires, but fleets retread casings and run them longer. Two-wheelers, near 12.9%, sell in high numbers in Asia at a low price per tire. Off-the-road vehicles, an estimated 7.5%, buy very large mining and farm tires, and Michelin noted an agricultural original equipment market at a ten-year low in H1 2026.[4] Fitting tire pressure sensors on new cars also links the two products, and the tire pressure monitoring system market is forecast on a 5.9% CAGR, so carmakers will keep specifying sensor-ready passenger tires. Car tires will keep the volume lead, and truck tires will keep the higher value per unit.
- SUV and pickup fitments are pushing passenger tire sizes up, with hatchbacks and sedans still the volume base.
- Bridgestone credited continued growth in premium tires and an improved product mix for passenger and light truck gains in the Americas in H1 2026.[5]
Why do radial tires lead automotive tires sales by tire structure?
Radial tires are projected to lead tire structure sales with 62% share in 2026, against an estimated 38% for bias and bias-ply designs.
Table 5: Tire Structure Share for the Automotive Tires Market (percentage share), 2026
| Tire Structure | Estimated Share (2026) |
|---|---|
| Radial | 62% |
| Bias/Bias-Ply | 38% |
| Total | 100.0% |
Steel-belted radials run cooler, last longer and save fuel on highway trips, and radial tires are projected to lead tire structure with 62% in 2026. Bias and bias-ply tires, about 38%, stay common on two-wheelers, farm tractors, older trucks and some off-road machines, since a stiff sidewall resists cuts and the price is lower. Low rolling resistance designs are almost all radial, and the low rolling resistance tire market is projected on an 11.7% CAGR, so EV and fuel-saving fitments will pull more volume into radial lines. Truck fleets in emerging markets are already moving from bias to radial as roads improve.
- Passenger car, SUV and highway truck tires form most radial volume.
- Goodyear Asia Pacific raised tire unit volume to 7.9 million in Q2 2026, from 7.5 million a year earlier.[6]
Why does the replacement channel lead automotive tires sales by sales channel?
Replacement and aftermarket sales are likely to lead sales channel with about 72.5% share in 2026, against roughly 27.5% for OEM fitments.
Table 6: Sales Channel Share for the Automotive Tires Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Replacement/Aftermarket | 72.5% |
| OEM | 27.5% |
| Total | 100.0% |
Every car on the road needs several sets of tires over a typical life, and only the first set comes from the factory, so replacement and aftermarket buying is likely to lead with about 72.5% in 2026. OEM fitments, about 27.5%, follow vehicle builds and carmaker approval cycles, and margins there are thinner. Goodyear reported EMEA replacement volume down 7.1% and original equipment up 8.3% in Q2 2026.[6] Replacement buyers choose on price, brand and dealer advice, and many keep the size and brand the carmaker fitted. Makers will defend OEM approvals to protect the replacement sales that follow.
- Independent dealers, chain stores, carmaker dealerships and online sellers handle replacement sales.
- USTMA forecasts a 6.2% rise in original equipment truck tire shipments in the United States for 2026.[2]
Why do all-season tires lead automotive tires sales by tire type?
All-season tires are estimated to lead tire type sales with 44.6% share in 2026, followed by summer and performance tires at about 27.9%, winter tires near 17.2% and ultra-high-performance tires around 10.3%.
Table 7: Tire Type Share for the Automotive Tires Market (percentage share), 2026
| Tire Type | Estimated Share (2026) |
|---|---|
| All-Season | 44.6% |
| Summer/Performance | 27.9% |
| Winter | 17.2% |
| Ultra-High-Performance (UHP) | 10.3% |
| Total | 100.0% |
Drivers across North America and southern Europe keep one set on the car all year, and all-season tires are estimated to lead with 44.6% in 2026. Summer and performance tires, about 27.9%, sell in Europe alongside a winter set, and the seasonal swap doubles the tire count per car. Winter tires, near 17.2%, are standard in the Nordics, Germany and Canada, and sales swing with snowfall. Ultra-high-performance tires, around 10.3%, go on sports cars and powerful EVs at the highest price per tire. Yokohama launched the GEOLANDAR H/T4 in April 2026, an all-season highway tire for light trucks, SUVs and commercial vans.[8] All-season patterns will gain in Europe as more drivers skip the spring and autumn change.
- Touring, highway and crossover all-season patterns make up most all-season sales.
- Yokohama plans to extend the lineup of high-value-added tires to 18-inch and larger sizes, Modern Tire Dealer reported in August 2026.[8]
What are the drivers, restraints, and opportunities in the automotive tires market?
A growing car parc and heavier electric models keep replacement demand rising. Weak original equipment volumes and tariffs squeeze makers, and EV-rated and large-rim ranges open higher-value sales.
- Driver: More cars on the road and heavier electric models wear tread faster, so drivers return for replacement sets more often.
- Restraint: Carmaker build cuts and import tariffs reduce factory fitments and raise costs, and makers cannot always pass those costs on to dealers.
- Opportunity: Drivers of electric and premium cars pay more for quiet, high-load, large-rim tires, which rewards makers with dedicated EV ranges.
Car Parc Growth Feeds the Replacement Stream
Sales of replacement tires follow the number of cars in use and the distance driven. Michelin said the group strengthened the position in the replacement market, particularly in Europe, during H1 2026.[4] Goodyear Asia Pacific grew replacement volume 6.4% in Q2 2026.[6] Each year of fleet growth adds owners who will need a new set within three to four years.
Weak Original Equipment and Tariff Costs
Producers of automotive tires face soft factory demand in several regions. Michelin cited persistent weakness in the original equipment market in the Americas in H1 2026.[4] Bridgestone expects tariffs to cost about USD 367 million in 2026.[5] Original equipment volumes will recover more slowly than replacement, and makers will keep plant loading low until carmakers raise builds.
EV and Large-Rim Ranges Open Higher-Value Sales
Adoption of EV-rated tires is rising with every battery car registered. Continental reported a Tires adjusted EBIT margin of 15.3% in Q2 2026, helped by more 18-inch and larger sizes.[3] Pirelli High Value car and moto volumes grew 3.5% in H1 2026, and standard volumes fell 8%.[7] Makers that hold carmaker approvals on EV platforms will collect the replacement sets that follow.
Which country CAGRs are profiled in the automotive tires market?
Table 8: Country CAGR Comparison for the Automotive Tires Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| United Kingdom | 7.2% |
| Germany | 7.1% |
| India | 6.9% |
| China | 6.8% |
| France | 6.5% |
| Japan | 6% |
| United States | 5.4% |
How do country-level CAGRs compare in the automotive tires market?
The UK zero emission vehicle mandate pushes carmakers to sell more battery cars each year, and FMI's forecast puts the United Kingdom first at 7.2%. Germany, home to premium carmakers, follows on 7.1%, and demand for performance tires there stays high. India grows at 6.9% as vehicle production rises with a larger middle class. China, at 6.8%, combines a large EV fleet with domestic tire capacity. France, on 6.5%, keeps near the global rate with a strong replacement base. Slow fleet turnover holds Japan to 6%. The United States, with long replacement cycles, is lowest on 5.4%.
- Battery electric registrations under the ZEV mandate raise EV tire sales in the United Kingdom.
- Premium car output and performance fitments support Germany.
- Rising car and two-wheeler production adds tire volume in India.
- A large EV fleet and domestic makers shape the tire mix in China.
- French replacement buyers favour premium brands and all-season patterns.
- Japanese carmakers export many vehicles, and domestic replacement grows slowly.
- American replacement cycles are stretching on long-tread tires and older vehicles.
Full report country CAGRs cover: the United Kingdom, Germany, India, China, France, Japan and the United States, ranked from EV-led growth down to long-cycle replacement against the 6.3% global CAGR, plus the remaining standard countries by region.
Country-wise Analysis
United Kingdom Automotive Tires Market Outlook (2026 to 2036)
British car buyers registered 99,201 battery electric cars in September 2026, SMMT reported, and the new car market grew 12% that month.[1] The FMI outlook for the United Kingdom is a 7.2% CAGR, the top rate among profiled countries. Each battery car needs EV-rated tires with higher load and lower noise, and those replacements sell at a premium over standard patterns.
Key takeaway: Battery car growth gives the United Kingdom the fastest tire sales.
Germany Automotive Tires Market Outlook (2026 to 2036)
German carmakers build many premium and performance models, and those cars leave the factory on 18-inch and larger tires. FMI projects Germany at a 7.1% CAGR. Continental reported a 3% rise in the European replacement market for passenger car and light commercial vehicle tires in Q2 2026.[3] Winter tire use adds a second set per car for many German drivers.
Key takeaway: Premium cars and seasonal sets keep Germany near the top.
India Automotive Tires Market Outlook (2026 to 2036)
Car and two-wheeler makers in India are adding output for a growing middle class, and new highways are lengthening trips. Growth in India is expected near a 6.9% CAGR. Domestic makers such as Apollo Tyres, MRF, CEAT and JK Tyre compete on price, and radial truck tires are replacing bias designs on long-haul fleets.
Key takeaway: India gains from more vehicles on longer new highways.
China Automotive Tires Market Outlook (2026 to 2036)
China has a large EV fleet and many domestic tire makers, including Zhongce Rubber, Linglong Tire and Triangle Tyre. Across Asia Pacific, Goodyear raised replacement volume 6.4% and original equipment volume 4.2% in Q2 2026.[6] Domestic makers supply most standard fitments, so global brands compete for premium and EV tires. The Chinese forecast is a 6.8% CAGR.
Key takeaway: Premium and EV tires are the main prize for global brands in China.
France Automotive Tires Market Outlook (2026 to 2036)
French drivers buy many premium replacement tires, and all-season patterns are gaining among them. MICHELIN brand replacement volumes grew 5% in H1 2026, and the group strengthened the replacement position in Europe.[4] FMI's figure for France is 6.5%, just above the global CAGR, supported by EV incentives.
Key takeaway: France tracks the global rate on premium replacement sets.
Japan Automotive Tires Market Outlook (2026 to 2036)
Japan has an ageing car fleet, a shrinking population and export-led carmakers, so domestic replacement grows slowly. Japanese tire makers are moving into higher-value sizes, and Yokohama raised the full-year business profit forecast 2.4% in August 2026.[8] Premium mix carries Japan to a projected 6% CAGR.
Key takeaway: Premium mix offsets a flat car fleet in Japan.
United States Automotive Tires Market Outlook (2026 to 2036)
USTMA forecasts 22.9 million truck replacement shipments in the United States for 2026, 7.1% fewer than in 2025, and passenger replacement down 1.6%.[2] American drivers cover long distances, but long-tread tires and older vehicles stretch replacement cycles. In FMI's country table, the United States holds a 5.4% CAGR, the slowest of the seven, as growth shifts to larger pickup and SUV sizes.
Key takeaway: Long replacement cycles keep the United States at the bottom of the table.
Who are the notable companies in the automotive tires market?
Michelin, Bridgestone, Goodyear, Continental, Pirelli, Sumitomo Rubber Industries, Yokohama Rubber, Hankook Tire & Technology, Nokian Tyres, Toyo Tire and Kumho Tire are among the profiled companies, with Apollo Tyres, MRF, CEAT, JK Tyre, Giti Tire, Zhongce Rubber, Linglong Tire, Triangle Tyre and Maxxis International.
Tire makers compete for carmaker approvals first, since an original equipment fitment usually brings the replacement sale that follows. Michelin reported H1 2026 sales of EUR 12.7 billion, 0.5% higher at constant exchange rates.[4] Bridgestone grew H1 2026 revenue 9.7%, and Americas revenue rose 11%.[5] Goodyear sold 36.5 million tires in Q2 2026, 4% fewer than a year earlier.[6] Continental, Pirelli, Sumitomo Rubber Industries, Yokohama Rubber and Hankook Tire & Technology lead the next group, and Asian volume makers complete the field.
- Global premium makers: Michelin, Bridgestone, Goodyear, Continental and Pirelli.
- Asian and specialist makers: Sumitomo Rubber Industries, Yokohama Rubber, Hankook Tire & Technology, Toyo Tire, Kumho Tire, Nokian Tyres, Giti Tire and Maxxis International.
- Volume makers in China and India: Zhongce Rubber, Linglong Tire, Triangle Tyre, Apollo Tyres, MRF, CEAT and JK Tyre.
Competitive Benchmarking: Automotive Tires Market
Table 9: Competitive Benchmarking for the Automotive Tires Market (qualitative documentation ratings), 2026
| Company | Passenger Replacement | OE Approvals | Large-Rim and EV Range | Recency |
|---|---|---|---|---|
| Michelin | High | High | High | High |
| Bridgestone | High | High | Medium | High |
| Goodyear | High | Medium | Medium | High |
| Continental | High | High | High | High |
| Pirelli | Medium | High | High | High |
Market share has no bearing on these grades, which follow the depth of each maker's 2026 results on the column topic.
Key Developments in the Automotive Tires Market
- Early October 2026 brought SMMT data showing September registrations of battery electric cars in the United Kingdom 36.3% higher.[1]
- In mid-August 2026, Bridgestone kept the full-year 2026 forecast and put the tariff cost near USD 367 million.[5]
- By 12 August 2026, Yokohama had raised the full-year sales forecast 1.5% after a 10.4% rise in H1 revenue.[8]
- On 6 August 2026, total U.S. tire shipments for 2026 were forecast at 330.3 million units in the USTMA July forecast.[2]
- Goodyear, on 5 August 2026, linked the Fayetteville, North Carolina closure to about USD 270 million in annual savings from 2028.[6]
- On 4 August 2026, Continental said the sale of ContiTech leaves the group in the final phase of becoming a pure-play tire maker.[3]
- A 2.5% price and mix gain in H1 2026 came through at Pirelli, which reported on 29 July 2026.[7]
- On 27 July 2026, Michelin confirmed the full-year guidance for growth in segment operating income.[4]
Key Players in the Automotive Tires Market
Global Premium Makers
- Michelin
- Bridgestone
- Goodyear
- Continental
- Pirelli
Asian and Specialist Makers
- Sumitomo Rubber Industries
- Yokohama Rubber
- Hankook Tire & Technology
- Toyo Tire
- Kumho Tire
- Nokian Tyres
- Giti Tire
- Maxxis International
Volume Makers in China and India
- Zhongce Rubber
- Linglong Tire
- Triangle Tyre
- Apollo Tyres
- MRF
- CEAT
- JK Tyre
Automotive Tires Market - Report Scope
Table 10: Report Scope for the Automotive Tires Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Vehicle type; tire structure; sales channel; tire type; region |
| Quantitative units | USD billion |
| Market definition | New pneumatic tires for passenger vehicles, light, medium and heavy commercial vehicles, two-wheelers and off-the-road vehicles, sold as original equipment or replacement. Retreaded tires are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Michelin, Bridgestone, Goodyear, Continental, Pirelli, Sumitomo Rubber Industries, Yokohama Rubber, Hankook Tire & Technology, Toyo Tire, Kumho Tire, Nokian Tyres, Giti Tire, Maxxis International, Zhongce Rubber, Linglong Tire, Triangle Tyre, Apollo Tyres, MRF, CEAT, JK Tyre |
| Forecast period | 2026 to 2036 |
Automotive Tires Market - Research Methodology
Table 11: Research Methodology for the Automotive Tires Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Tire maker results, trade association shipment forecasts, vehicle registration data and tire trade press from May 2025 onward. |
| Desk Research | Desk research covers replacement cycles, original equipment builds, rim size mix, EV fitments and tariffs. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 272.2 billion and the 6.3% CAGR for 2026 to 2036. |
| Data Validation | Volume, sales and registration figures were matched to the release or table that first carried them. |
Automotive Tires Market by Segments
Automotive Tires Market segmented by Vehicle Type:
- Passenger Vehicle
- Commercial Vehicle
- Two-Wheeler
- Off-the-Road (OTR)
Automotive Tires Market segmented by Tire Structure:
- Radial
- Bias/Bias-Ply
Automotive Tires Market segmented by Sales Channel:
- OEM
- Replacement/Aftermarket
Automotive Tires Market segmented by Tire Type:
- All-Season
- Summer/Performance
- Winter
- Ultra-High-Performance (UHP)
Automotive Tires Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Society of Motor Manufacturers and Traders. (2026, October 5). Record electric car market powers bumper September. https://www.smmt.co.uk/record-electric-car-market-powers-bumper-september/
- [2] U.S. Tire Manufacturers Association. (2026, August 6). USTMA July 2026 Forecast. https://www.ustires.org/newsroom/ustma-july-2026-forecast
- [3] Continental AG. (2026, August 4). Continental Enters Final Phase of Realignment with Strong Second Quarter. https://www.continental.com/en/press/press-releases/results-first-half-2026/
- [4] Michelin. (2026, July 27). Financial information at June 30, 2026. https://www.michelin.com/en/publications/group/financial-information-at-june-30-2026
- [5] Modern Tire Dealer. (2026, August 13). Bridgestone Americas Sales Rise 11% as North American Share Grows. https://www.moderntiredealer.com/suppliers/news/55397897/bridgestone-americas-sales-rise-11-as-north-american-tire-share-grows
- [6] The Goodyear Tire & Rubber Company. (2026, August 5). Goodyear Announces Second Quarter 2026 Results (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000042582/000162828026053379/q22026nrearningsrelease_dr.htm
- [7] Pirelli & C. S.p.A. (2026, July 29). Pirelli Board Majority Approves Consolidated Results to 30 June 2026. https://press.pirelli.com/pirelli-board-majority-approves-consolidated-results-to-30-june-2026/
- [8] Modern Tire Dealer. (2026, August 12). Yokohama Reports Record First-Half Revenue. https://www.moderntiredealer.com/suppliers/news/55397308/yokohama-reports-record-first-half-2026-revenue
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive tires market during 2026?
- What market size is projected by 2036?
- Which vehicle type holds notable share?
- Which tire structure holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the automotive tires market expected in 2026?
Tire buyers are expected to take the automotive tires market to USD 272.2 billion in 2026 in FMI's estimate, up from USD 256.1 billion in 2025. Sales of automotive tires are expected to reach USD 501.5 billion by 2036.
What CAGR is projected for the automotive tires market through 2036?
Demand for automotive tires is likely to grow at a 6.3% CAGR over 2026 to 2036. Replacement sets for a growing car parc, heavier electric cars and larger rims carry that growth.
Which vehicle type holds a notable market share in 2026?
Passenger vehicles are expected to lead with 48% share in 2026. Commercial vehicles hold an estimated 31.6%.
Which tire structure holds a notable market share in 2026?
Radial tires are projected to lead with 62% share. Bias and bias-ply designs account for an estimated 38%.
Which country has a notable expansion outlook through 2036?
The United Kingdom heads FMI's country table at a 7.2% CAGR. Germany follows at 7.1%.
Who are the key companies in the automotive tires market?
Michelin, Bridgestone, Goodyear, Continental and Pirelli form the global premium group. Sumitomo Rubber Industries, Yokohama Rubber, Hankook Tire & Technology and volume makers in China and India complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Vehicle
- Commercial Vehicle
- Two-Wheeler
- Off-the-Road (OTR)
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Tire Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Tire Structure, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Tire Structure, 2026 to 2036
- Radial
- Bias/Bias-Ply
- Y-o-Y Growth Trend Analysis By Tire Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Tire Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Replacement/Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Tire Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Tire Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Tire Type, 2026 to 2036
- All-Season
- Summer/Performance
- Winter
- Ultra-High-Performance (UHP)
- Y-o-Y Growth Trend Analysis By Tire Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Tire Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Vehicle Type
- By Tire Structure
- By Sales Channel
- By Tire Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Michelin
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bridgestone
- Goodyear
- Continental
- Pirelli
- Sumitomo Rubber Industries
- Yokohama Rubber
- Hankook Tire & Technology
- Toyo Tire
- Kumho Tire
- Nokian Tyres
- Giti Tire
- Maxxis International
- Zhongce Rubber
- Linglong Tire
- Triangle Tyre
- Apollo Tyres
- MRF
- CEAT
- JK Tyre
- Michelin
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


