

- Market Size (2026)
- USD 1.8 Bn
- Forecast (2036)
- USD 4.0 Bn
- CAGR (2026 to 2036)
- 8.3%
How big is Pea Protein Market in 2026?
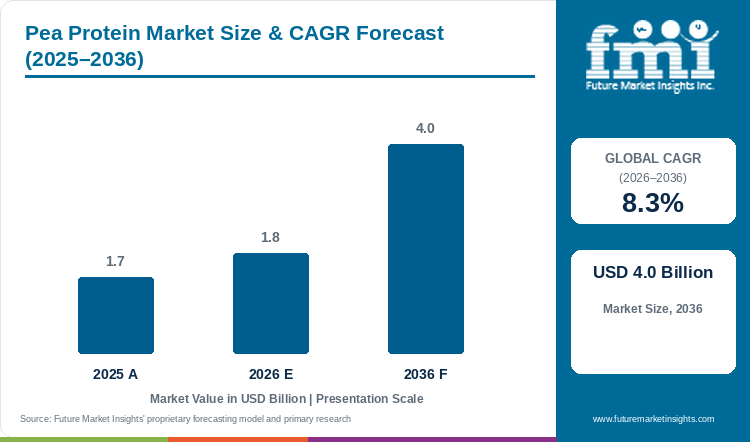
Future Market Insights projects the global pea protein market to grow from USD 1.8 billion in 2026 to USD 4.0 billion by 2036, recording an 8.3% CAGR over the ten-year period.
Sports nutrition brands, dairy-free beverage makers, and meatless food processors are buying more yellow field pea protein to replace soy and dairy whey without triggering allergen warnings or GMO label claims. Future Market Insights estimates global pea protein market value at USD 1.7 billion in 2025 and USD 1.8 billion in 2026, with the market forecast to reach USD 4.0 billion by 2036 at an 8.3% CAGR. Growing faster than the broader pea protein ingredients category at a 3.0% CAGR, wet-fractionated pea protein isolates (80% to 85% protein) capture 47.3% of 2026 sales because water-based extraction removes hull fibers and starches that would otherwise thicken shakes or dull meat-alternative texture. Research published in Food Chemistry highlights why yellow pea protein isolate has become such a popular sustainable ingredient, combining low allergenicity and balanced legumin and vicilin proteins with reliable emulsification, while noting that processors still have to manage grassy bean flavors and natural plant antinutrients[1]. In addition, dry weather swings across Canadian and European pea farms, high water treatment costs at wet-milling plants, and excess pea starch co-products continue to tighten processor margins.
Key Market Trends & Insights
- By product type: Pea Protein Isolates are projected to capture 47.3% in 2026 because 80% to 85% protein purity prevents starch thickening in drinks and meat alternatives.
- By physical form: Spray-Dried Soluble Powder is estimated to command 75.1% in 2026 as dry powder simplifies warehouse storage and automated mixing.
- By end-use application: Industrial Meat Analogues are expected to concentrate 50.1% in 2026 because soy-free patties and sausages rely on pea protein gelling.
- By nature: Conventional Non-GMO Pea is forecast to generate 77.9% in 2026 owing to naturally non-GMO yellow field pea farming across Canada, Europe, and the USA.
- By sales channel: B2B Food Processors are anticipated to account for 64.2% in 2026 through bulk industrial supply contracts.
Regional Highlights
- Top national expansion: Brazil is projected to lead major national markets at a 9.6% CAGR through 2036, propelled by meat-packer plant-based exports and allergen-free drink launches.
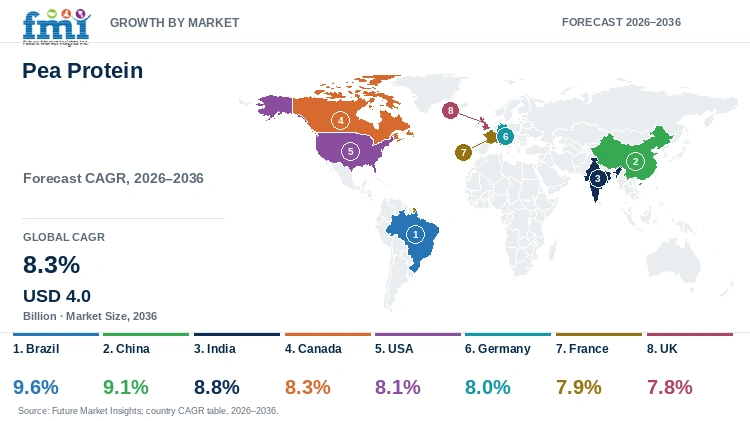
- Broader country progression: China is expected to expand at 9.1% CAGR ahead of India (8.8%), Canada (8.3%), the United States (8.1%), Germany (8.0%), France (7.9%), and the United Kingdom (7.8%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Pea Protein Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.7 billion |
| Estimated Market Size in 2026 | USD 1.8 billion |
| Projected Market Size by 2036 | USD 4.0 billion |
| CAGR, 2026 to 2036 | 8.3% |
| Added Value, 2026 to 2036 | USD 2.2 billion |
Food and supplement companies moving away from soy and dairy allergens need plant proteins that mix smoothly into water without leaving gritty sediment or a bitter aftertaste. Early dry-milled pea flours carried leftover starch and natural enzymes that turned oils rancid during storage. Meanwhile, raw seed supply requires careful contracting: the USDA Economic Research Service Vegetables and Pulses Outlook reported that U.S. dry pea planted area fell 18% in 2026 to 909,000 acres, with harvested area down 17% to 854,900 acres as growers rotated crops[2]. To lock in consistent quality despite tighter harvests, beverage and meat-alternative makers are signing multi-year contracts for wet-fractionated pulse ingredients with guaranteed protein purity and neutral flavor.
Yellow Pea Crushing and Fractionation-Volume Sizing
Table 2: Yellow Pea Crushing and Fractionation-Volume Sizing for the Pea Protein Market (2025, 2026, and 2036)
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.7 | 1.8 | 4.0 |
| Commercial pea protein volume (thousand tonnes) | 390.0 to 430.0 | 415.0 to 460.0 | 860.0 to 950.0 |
| Dry yellow pea crushing intake (million tonnes) | 2.1 to 2.4 | 2.3 to 2.6 | 4.7 to 5.2 |
| Average wholesale price per kg (USD) | 3.9 to 4.4 | 4.0 to 4.5 | 4.2 to 4.7 |
Operational note: Crushing-volume ranges apply dry yellow field pea intake at 21.0% to 24.0% raw seed protein content and 17.0% to 20.0% isolate extraction yield.
Wet-fractionation mills must find buyers for every part of the yellow pea kernel to stay profitable, since protein makes up less than a quarter of the dry seed weight. Processors sell co-product pea starch into glass noodles, paperboard adhesives, and pet food kibbles while turning outer hulls into dietary fiber.
Per Capita & Wet-Milling Facility Sizing
Table 3: Per Capita and Facility Spending Indicators for the Pea Protein Market (2025, 2026, and 2036)
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 207.3 | 216.9 | 444.4 |
| Annual output per wet-fractionation plant (USD thousand) | 38,000 to 45,000 | 40,000 to 48,000 | 72,000 to 86,000 |
| Wet-fractionated isolate & textured share (%) | 68.0% to 72.0% | 69.0% to 73.0% | 74.0% to 78.0% |
Table 4: Wet-Milling & Dry-Fractionation Plant Revenue Indicators for the Pea Protein Market (2026)
| Metric | Value | Industrial Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.8 billion | 2026 global demand baseline |
| Commercial pea fractionation plants | 42 plants | Global wet-milling and air-classification plant registry |
| Average revenue per fractionation plant | USD 42,857.1 thousand | Annualized isolate, concentrate, and textured output |
| Industrial meat-analogue demand, 2026 | USD 0.9 billion | 50.1% end-use application segment allocation |
Blending extracted pea protein with inner cotyledon pea fiber helps plant-based nuggets, burgers, and bakery fillings hold moisture through freezing and reheating.
Analyst Perspective
"Pea protein has grown from a niche allergen-free substitute into a mainstream industrial protein as well as soy and whey. Wet-fractionation processors that remove grassy off-notes and find steady buyers for co-product pea starch will win multi-year contracts across sports nutrition and meat alternatives."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the pea protein market segmented?
The pea protein market is segmented by product type (pea protein isolates, pea protein concentrates, textured & hydrolyzed pea), physical form, end-use application, nature, sales channel, and region.
By product type: Pea Protein Isolates, Pea Protein Concentrates, Textured & Hydrolyzed Pea, and Others.
By physical form: Spray-Dried Soluble Powder, Extruded Crisps & Chunks, Liquid Slurry Dispersions, and Others.
By end-use application: Industrial Meat Analogues, Sports & Vegan Powders, Dairy-Free Milk & Bakery, and Companion Animal Nutrition.
By nature: Conventional Non-GMO Pea, Certified Organic Yellow Pea, and Identity-Preserved Traceable Pea.
By sales channel: B2B Food Processors, Contract Supplement Packers, Specialty Ingredient Distributors, and Others.
Why do Pea Protein Isolates lead the product type category?
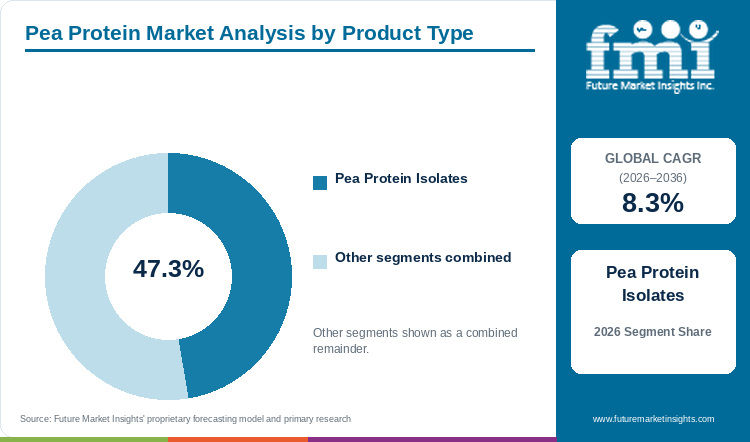
Pea Protein Isolates are projected to capture 47.3% of product type demand in 2026 because 80% to 85% wet-fractionated purity eliminates starch thickening in dairy-free beverages and meat analogues.
Table 5: Product Type Share for the Pea Protein Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Pea Protein Isolates | 47.3% |
| Other Segments Combined | 52.7%* |
| Total | 100.0% |
*Note: Remaining product type categories sum to 100.0% of 2026 commercial pea protein shipments.
Table 6: Product Type Leadership and Market Growth for the Pea Protein Market (2026 to 2036)
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.3% |
| Leading Segment | Pea Protein Isolates (47.3%) |
Beverage, dairy-free yogurt, and meat-alternative makers specify wet-fractionated isolates (80% to 85% dry-basis protein) because removing native pea starch and hull fiber prevents unwanted thickening during high-heat pasteurization, while also serving as the starting material for plant protein hydrolysate ingredients.
- Pea Protein Isolates are projected to secure 47.3% of product type demand in 2026 by delivering reliable fat binding, light color, and firm cooking texture.
- Research in Food Research International shows that crosslinking pea protein isolate with sodium alginate in plant-based meat analogues cuts cooking moisture loss from 21.48% down to 16.52% and raises water-holding capacity to 72.50%[3].
Why does Spray-Dried Soluble Powder define the largest physical form segment?
Spray-Dried Soluble Powder is estimated to secure 75.1% of the physical form segment in 2026 as low-moisture powder enables ambient global shipping and rapid dry-blend dosing.
Turning wet protein curds into free-flowing spray-dried powders with under 7% moisture allows unrefrigerated global shipping and easy dosing into dry mix canisters, where brands often blend pea with chickpea protein or brown rice protein to round out essential amino acids.
- Spray-Dried Soluble Powder is estimated to command 75.1% of the physical form segment in 2026 because drink plants, supplement packers, and extrusion lines feed dry powder directly into high-speed mixers.
- Experiments published in Food Chemistry evaluating blended pea protein high-moisture extrudates show that combining spray-dried pea protein isolate with complementary plant proteins strengthens fibrous layering and chew elasticity[4].
What keeps Industrial Meat Analogues ahead by end-use application?
Industrial Meat Analogues are expected to command 50.1% of end-use application demand in 2026 because soy-free burgers, sausages, and nuggets rely on pea protein gelling and water binding.
Soy-free burgers, breakfast sausages, and chickenless strips use 16% to 24% pea protein to build a chewy meat-like texture and hold vegetable oil droplets during frying, while hydrolyzed protein inputs add savory broth flavor.
- Industrial Meat Analogues are expected to hold 50.1% of end-use application demand in 2026 because supermarket and fast-food brands specify allergen-free yellow pea proteins to replace soy.
- Product specifications from AGT Food and Ingredients Inc. detail how its dry-processed PulsePlus line supplies Pea Protein 55 concentrate (at least 55% protein) and Pea Protein 80 isolate (at least 80% protein) for meat alternatives, snacks, and bakery items[5].
Why does Conventional Non-GMO Pea lead the nature category?
Conventional Non-GMO Pea is forecast to generate 77.9% of nature segment demand in 2026 owing to naturally non-GMO yellow field pea cultivation across Canada, Europe, and the USA.
Unlike corn and soybeans, commercial yellow field peas (Pisum sativum) are bred entirely through conventional non-GMO farming across Canada, the United States, France, and Eastern Europe.
- Conventional Non-GMO Pea is forecast to account for 77.9% of nature segment demand in 2026 because food brands can print Non-GMO Project Verified labels without paying the 35% to 55% price premium charged for certified organic peas.
- A study in the Journal of Food Science demonstrated that cold-plasma-treated soy and non-GMO yellow pea protein blends extruded with mango peel powder achieve fast water rehydration and firm meat-like chew[6].
What gives B2B Food Processors the leading position in sales channel?
B2B Food Processors are anticipated to account for 64.2% of sales channel demand in 2026 through bulk tote-bin and truckload procurement for commercial food and beverage plants.
Commercial meat-alternative plants, dairy-free milk bottlers, and pet food factories buy pea protein in bulk tote bins and multi-tonne truckloads directly from wet-milling mills.
- B2B Food Processors are anticipated to capture 64.2% of sales channel demand in 2026 ahead of Contract Supplement Packers and Specialty Ingredient Distributors.
- Formulation guidance from PURIS Proteins, LLC notes that the 2026 U.S. Dietary Guidelines recommend 1.2 to 1.6 grams of protein per kilogram of body weight daily, and highlights that PURIS pea protein isolate delivers 8% leucine by weight (2.5 grams per 30-gram serving) with roughly 90% digestibility[7].
What are the drivers, restraints, and opportunities in the pea protein market?
In the pea protein market, allergen-free soy and dairy replacement drives wet-fractionated isolate demand, while grassy off-notes, low methionine content, and surplus pea starch co-products restrain processor margins.
- Driver: Soy-free and dairy-free clean-label recipes make yellow pea isolates and textured proteins staple B2B ingredients.
- Restraint: Grassy bean flavors, lower methionine levels, and excess pea starch co-products squeeze wet-milling margins.
- Opportunity: Clear hydrolyzed pea peptide drinks, extruded protein crisps, and pea-rice blends open higher-margin nutrition sales.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Food makers are replacing imported soy concentrates with yellow pea proteins that link together into chewy fibers inside twin-screw extruders without synthetic binders. Within the wider protein ingredient sector, research in the Journal of Food Science showed that food-grade reducing agents help open up pea protein structures and speed up fiber alignment during high-moisture extrusion[8].
Risk Assessment of the Pea Protein Market: Operational and Formulation Friction
Standard wet-milled pea protein powders can settle out in neutral drinks if particle size and surface charge are not carefully controlled. Research in Food Chemistry proved that combining fine media milling with an alkaline pH shift at pH 10 raises pea protein isolate water solubility more than threefold from 24.80% to 74.85%[9], directly improving mixability across protein powder canisters and ready-to-drink shakes.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Pre-splitting pea and rice protein isolates with natural enzymes improves extrusion flow and texture in snacks and meat bites, expanding the vegan protein aisle beyond thick shakes. A study in Foods examining extruded hydrolyzed rice and pea protein isolates confirmed that enzymatic pre-treatment modifies protein network stiffness and improves crispness and digestibility[10].
Pea Protein Market by Country (2026 to 2036)
As per FMI, Brazil is projected to lead pea protein expansion across tracked markets at a 9.6% CAGR from 2026 to 2036, followed by China at 9.1% and India at 8.8%.
Table 7: Country CAGR and Primary Growth Levers for the Pea Protein Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 9.6% | Soy-free meat-analogue exports and domestic sports supplement blending |
| China | 9.1% | Shandong fractionation upgrades and domestic plant-beverage fortification |
| India | 8.8% | Vegetarian sports-nutrition powders and pulse-fortified extruded snacks |
| Canada | 8.3% | Prairie wet-fractionation plant capacity and non-GMO yellow pea harvests |
| USA | 8.1% | Allergen-free clinical and sports shakes and Midwest wet-milling plants |
| Germany | 8.0% | Clean-label meatless sausage extrusion and grain-free pet food |
| France | 7.9% | Domestic yellow pea biorefineries and clinical nutrition validation |
| UK | 7.8% | Non-GMO supermarket meat alternatives and high-protein extruded snacks |
Source: Future Market Insights analysis
Brazil Pea Protein Market Outlook (2026 to 2036)
Unlike traditional soy-only South American markets, Brazil's multinational meat packers and sports-nutrition blenders are rapidly adopting yellow pea isolates to make soy-free export burgers, sausages, and protein shakes. Research in the Journal of the Science of Food and Agriculture showed that pairing pea protein isolate with konjac glucomannan forms firm, heat-stable binary gels that lock in moisture inside restructured meat products[11]. Domestic pea protein demand is projected to expand at a leading 9.6% CAGR through 2036.
Key takeaway: In Brazil, export-focused soy-free meat alternatives and domestic sports supplement blending are projected to drive a 9.6% CAGR.
China Pea Protein Market Outlook (2026 to 2036)
Industrial pea protein production and demand in China are expected to climb at a 9.1% CAGR from 2026 to 2036, anchored by Yantai and Shandong wet-fractionation mills that extract pea protein as well as starch for vermicelli glass noodles. A study in Food Chemistry demonstrated that treating pea protein with high-pressure microfluidization and plant polyphenols builds stable high-internal-phase emulsions suitable for 3D-printed and structured foods[12]. Chinese processors are upgrading spray-drying towers to supply 85% isolates to domestic dairy-free beverage and nutrition brands.
Key takeaway: In China, Shandong fractionation upgrades and domestic plant-beverage fortification are expected to sustain a 9.1% CAGR.
India Pea Protein Market Outlook (2026 to 2036)
In contrast to Western markets centered on burger patties, India's pea protein growth is fueled by urban vegetarian protein demand, direct-to-consumer vegan workout powders, and protein-fortified biscuits and snacks. Ingredion Incorporated reported second-quarter 2026 net sales of USD 1.85 billion and higher operating profit in Protein Fortification as food and beverage brands expanded pulse protein orders[13]. India is forecast to record an 8.8% CAGR between 2026 and 2036 as local supplement packers blend pea and brown rice isolates.
Key takeaway: In India, vegetarian sports-nutrition powders and pulse-fortified snacks are forecast to support an 8.8% CAGR.
Canada Pea Protein Market Outlook (2026 to 2036)
Whereas importing countries rely on shipped dry peas, Canada anchors global yellow field pea farming across Saskatchewan, Alberta, and Manitoba as well as world-scale wet-fractionation and air-classification mills in Portage la Prairie and Vanscoy. Research in the Journal of Dairy Science confirmed that vegetable oil emulsions stabilized by pea protein and steviol glycoside complexes restore creamy texture and cut whey separation in fat-free yogurt[14]. Canada is projected to advance at an 8.3% CAGR through 2036.
Key takeaway: In Canada, Prairie wet-fractionation plant capacity and farmgate non-GMO yellow pea supply are projected to sustain an 8.3% CAGR.
USA Pea Protein Market Outlook (2026 to 2036)
Allergen-safe school foodservice rules, GLP-1 muscle-support shakes, and grain-free pet food drive United States pea protein buying across Minnesota, Nebraska, and Iowa wet-milling plants. Extrusion trials published in Gels show that tuning moisture and barrel heat in isolated pea-protein high-moisture meat analogues produces dense, layered fibers with strong water retention[15]. United States demand is forecast to grow at an 8.1% CAGR from 2026 to 2036.
Key takeaway: In the USA, allergen-free nutrition shakes and domestic Midwest wet-milling plants are predicted to anchor an 8.1% CAGR.
Germany Pea Protein Market Outlook (2026 to 2036)
What sets Germany apart in Western Europe is the combination of domestic clean-label pea processing in Lower Saxony with Europe's largest supermarket private-label vegan sausage, cold-cut, and pet food market. Research in Foods evaluating high-moisture extruded plant-based meat analogues confirmed that natural polyphenol extracts protect protein structures against lipid oxidation and improve chewiness[16]. German pea protein demand is estimated to expand at an 8.0% CAGR through 2036.
Key takeaway: In Germany, clean-label meatless sausage extrusion and grain-free pet food recipes are estimated to drive an 8.0% CAGR.
France Pea Protein Market Outlook (2026 to 2036)
France leads European Union yellow pea farming across Hauts-de-France and Grand Est, supplying domestic wet-fractionation biorefineries in Vic-sur-Aisne. Clinical summaries published by Roquette Freres S.A. reviewing human trials on NUTRALYS pea protein show documented benefits for muscle mass maintenance, satiety, and blood glucose control in healthy adult volunteers[17]. French pea protein demand is projected to grow at a 7.9% CAGR from 2026 to 2036 under national plant-protein farming programs.
Key takeaway: In France, domestic yellow pea biorefineries and clinical nutrition studies are projected to support a 7.9% CAGR.
UK Pea Protein Market Outlook (2026 to 2036)
Supermarket chilled plant-based ready meals, high-protein crisps, and meal-replacement shakes shape United Kingdom buying, where grocery chains avoid genetically modified soy. A study in Food Chemistry: X examining pea-protein-enriched corn extrudates demonstrated that adjusting feed moisture and barrel temperature controls acrylamide formation while keeping roasted aroma and crispness[18]. The UK market is forecast to progress at a 7.8% CAGR between 2026 and 2036.
Key takeaway: In the UK, non-GMO supermarket meat alternatives and high-protein extruded snacks are forecast to maintain a 7.8% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the pea protein market?
Roquette Freres S.A., PURIS Proteins, LLC, Cosucra Groupe Warcoing S.A., Ingredion Incorporated, Emsland-Starke GmbH, AGT Food and Ingredients Inc., Archer Daniels Midland Company, and Cargill, Incorporated represent the notable companies in the pea protein market.
FMI analysis indicates that the competitive arena divides between dedicated European and North American wet-fractionated isolate specialists, dry air-classification concentrate millers, and global diversified grain processors.
- Dedicated Wet-Fractionated Pea Isolate Specialists: Roquette Freres S.A., PURIS Proteins, LLC, Cosucra Groupe Warcoing S.A., and Emsland-Starke GmbH operate specialized water-extraction and spray-drying plants.
- Dry Air-Classification & Pulse Milling Leaders: Ingredion Incorporated and AGT Food and Ingredients Inc. mill North American yellow field peas into functional 50% to 70% concentrates and textured pulse extrudates.
- Global Diversified Agribusiness & Protein Platforms: Archer Daniels Midland Company and Cargill, Incorporated integrate pea protein isolates, concentrates, and textured blends into global B2B formulation contracts.
Competitive Benchmarking: Pea Protein Market
Table 8: Competitive Benchmarking for the Pea Protein Market (qualitative capability tiers), 2026
| Company | Isolate & Concentrate Breadth | Sensory & Solubility Depth | B2B Formulator Access | Geographic Reach |
|---|---|---|---|---|
| Roquette Freres S.A. | High | High | High | High |
| PURIS Proteins, LLC | High | High | High | Medium |
| Cosucra Groupe Warcoing S.A. | High | High | High | High |
| Ingredion Incorporated | High | High | High | High |
| Emsland-Starke GmbH | High | Medium | High | High |
| AGT Food and Ingredients Inc. | Medium | Medium | High | High |
| Archer Daniels Midland Company | High | High | High | High |
| Cargill, Incorporated | High | High | High | High |
Scoring basis: Capability tiers evaluate documented isolate and concentrate purity breadth, sensory debittering and solubility depth, B2B food and supplement access, and regional pea-belt sourcing footprint.
Key Developments in the Pea Protein Market
- Roquette Freres S.A. launched its breakthrough clean-tasting NUTRALYS pea protein isolate in February 2026 to eliminate beany off-notes in dairy-free beverages and high-protein shakes[19].
- Cosucra Groupe Warcoing S.A. introduced its PISANE P960 pea protein isolate in December 2025, delivering 33% lower powder cohesion and eightfold faster water wetting for high-protein bars and savory snacks[20].
- Emsland-Starke GmbH published technical guidance in November 2025 on formulating nutrient-dense, clean-label foods using yellow pea protein isolates, native starches, and fibers[21].
Key Players in the Pea Protein Market
Dedicated Wet-Fractionated Pea Isolate Specialists
- Roquette Freres S.A.
- PURIS Proteins, LLC
- Cosucra Groupe Warcoing S.A.
Dry Air-Classification & Clean-Label Pulse Millers
- Ingredion Incorporated
- Emsland-Starke GmbH
- AGT Food and Ingredients Inc.
Global Diversified Agribusiness & Protein Platforms
- Archer Daniels Midland Company
- Cargill, Incorporated
Pea Protein Market - Report Scope
Table 9: Report Scope for the Pea Protein Market (coverage fields and definitions)
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Physical Form; End-Use Application; Nature; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Commercial demand for wet-fractionated pea protein isolates (80%-85%), dry air-classified concentrates (50%-70%), and textured or hydrolyzed yellow pea proteins |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, China, India, Canada, USA, Germany, France, UK, plus regional aggregations |
| Key Companies Covered | Roquette Freres S.A., PURIS Proteins, LLC, Cosucra Groupe Warcoing S.A., Ingredion Incorporated, Emsland-Starke GmbH, AGT Food and Ingredients Inc., Archer Daniels Midland Company, Cargill, Incorporated |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up yellow field pea crushing and fractionation reconciliation |
Pea Protein Market - Research Methodology
Table 10: Research Methodology for the Pea Protein Market (research methods and analytical approach)
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with pulse wet-milling plant directors, sports-nutrition formulators, and B2B meat-analogue procurement managers |
| Secondary Research | Analysis of USDA Economic Research Service pulse reports, SEC filings, and peer-reviewed pea protein extraction studies |
| Market Sizing and Forecasting | Top-down yellow pea fractionation capacities reconciled against bottom-up beverage, meat-analogue, and pet-food inclusion volumes |
| Country Forecasting Model | Country projections weight domestic yellow pea acreage, wet-milling capacity additions, and allergen-free foodservice adoption |
| Operational Benchmark Traceability | Crushing tonnage and plant output indicators in Tables 2, 3, and 4 cross-checked against 17% to 20% isolate extraction yields |
| Data Triangulation and Validation | Demand estimates validated against supplier shipment disclosures and pulse trade association audits |
Pea Protein Market by Segments
Pea Protein Market segmented by Product Type:
- Pea Protein Isolates
- Pea Protein Concentrates
- Textured & Hydrolyzed Pea
- Others
Pea Protein Market segmented by Physical Form:
- Spray-Dried Soluble Powder
- Extruded Crisps & Chunks
- Liquid Slurry Dispersions
- Others
Pea Protein Market segmented by End-Use Application:
- Industrial Meat Analogues
- Sports & Vegan Powders
- Dairy-Free Milk & Bakery
- Companion Animal Nutrition
Pea Protein Market segmented by Nature:
- Conventional Non-GMO Pea
- Certified Organic Yellow Pea
- Identity-Preserved Traceable Pea
Pea Protein Market segmented by Sales Channel:
- B2B Food Processors
- Contract Supplement Packers
- Specialty Ingredient Distributors
- Others
Pea Protein Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Li, Z., Shang, X., Xu, Z., Xu, J., Tang, Y., & Yang, R. (2026, May 22). Pea protein isolate as a versatile and sustainable protein: basic characteristics, applications, and limitations. Food Chemistry, 520, 149765 (PubMed PMID 42190379).
- [2] Davis, W. V., Weber, C., & Wakefield, H. (2026, September 11). Vegetables and Pulses - Market Outlook: Pulse and Potato Plantings Lose Ground in 2026. USDA Economic Research Service.
- [3] Ali, K., Liu, C., Niaz, N., Ul Haq, F., Xu, M., Sun, R., Zhu, T., Yin, P., & Wu, M. (2026, April 30). Pea protein isolate-sodium alginate-based plant-based meat analogue: dual crosslinking and molecular insight mechanisms. Food Research International, 230, 118568 (PubMed PMID 41794456).
- [4] Zhang, J., Xiao, P., Peng, Y., Li, Q., Liao, X., Han, Q., & Zhao, J. (2025, October 28). Evaluating the effect of protein blending on the characteristics of pea protein-based high moisture extrudates. Food Chemistry, 496(Pt 3), 146860 (PubMed PMID 41175618).
- [5] AGT Food and Ingredients Inc. (2026, January 15). PulsePlus Protein Concentrates and Isolates. AGT Food and Ingredients Inc.
- [6] Rout, S., & Srivastav, P. P. (2026, January 15). Development of Cold Plasma-Treated Soy-Pea Protein Meat Analogues Incorporating Mango Peel Powder as a Texturant by Low-Moisture Extrusion: Evaluation of Rehydration Kinetics and Textural Properties. Journal of Food Science, 91(1), e70801 (PubMed PMID 41502215).
- [7] PURIS Proteins, LLC. (2026, January 20). Protein Needs at a Glance: What the updated guidelines mean for your formulations. PURIS Proteins, LLC.
- [8] Bernin, J. B., Watanabe, P., Smith, B., Kowalski, R. J., & Ganjyal, G. M. (2026, January 22). Reducing Agents Aid in the Texturization of Pea Protein Isolate During High Moisture Extrusion. Journal of Food Science, 91(1), e70797 (PubMed PMID 41527678).
- [9] Li, C., Dai, T., Jiang, D., Feng, Y., Deng, L., Li, T., Wang, Y., Liu, C., & Chen, J. (2025, December 25). Enhancing pea protein functionality via media milling and pH-shifting. Food Chemistry, 496(Pt 1), 146580 (PubMed PMID 41075662).
- [10] Munoz, M. M., Garrido, M. D., & Penaranda, I. (2025, October 22). Effects of Extrusion on Protein Textures of Hydrolysed Rice and Pea Isolates. Foods, 14(21), 3590 (PMCID PMC12610216).
- [11] Khamis, Y. M., Zhou, T.-Q., Liu, J.-C., Li, L., & Wu, H.-T. (2026, August 6). Construction and characterization of binary hydrogels based on pea protein isolate and konjac glucomannan. Journal of the Science of Food and Agriculture (PubMed PMID 42563233).
- [12] Dong, L., Sheng, G., Li, Y., Guo, T., Ni, Y., Bai, H., Han, Q., & Zhou, Q. (2026, April 15). Modifying pea protein via dynamic high-pressure microfluidization and polyphenol/polysaccharide incorporation to stabilize high internal phase Pickering emulsions for 3D printing. Food Chemistry, 508(Pt A), 148234 (PubMed PMID 41679218).
- [13] Ingredion Incorporated. (2026, August 4). Ingredion Incorporated Reports Second Quarter 2026 Results (Form 8-K Exhibit 99.1). U.S. Securities and Exchange Commission EDGAR.
- [14] Wang, W., Zhang, M., Zhao, R., Xie, G., Zhang, T., & Wang, C. (2026, May 4). Enhancing the quality of milk fat-free yogurt with vegetable oil emulsion stabilized by pea protein and steviol glycosides complexes. Journal of Dairy Science (PubMed PMID 42092542).
- [15] Zhang, Y., Choi, H.-W., Lee, Y., Ryu, G.-H., & Gu, B.-J. (2026, January 1). Effects of Formulation and Extrusion Conditions for Isolated Pea Protein-Based High-Moisture Meat Analogs: Insights into Gelation and Structural Development. Gels, 12(1), 42 (PubMed PMID 41590068).
- [16] Bulgaru, V., Sensoy, I., Netreba, N., Gurev, A., Altanlar, U., Paiu, S., Dragancea, V., Sturza, R., & Ghendov-Mosanu, A. (2025, August 23). Qualitative and Antioxidant Evaluation of High-Moisture Plant-Based Meat Analogs Obtained by Extrusion. Foods, 14(17), 2939 (PMCID PMC12427645).
- [17] Guerin-Deremaux, L., Babault, N., Re, R., Pompo, S., Lefranc-Millot, C., Sharma, J., & Allaert, F. A. (2026, January 16). The Health Benefits of NUTRALYS Pea Protein in Healthy Volunteers. Roquette Freres S.A.
- [18] Goncuoglu Tas, N., Balagiannis, D. P., Ghawi, S. K., Gokmen, V., & Parker, J. K. (2026, May 22). Effect of extrusion parameters and feed composition on physical characteristics, aroma profile and acrylamide content in pea protein-enriched corn extrudates. Food Chemistry: X, 36, 104019 (PMCID PMC13226939).
- [19] Roquette Freres S.A. (2026, February 23). Launch of Breakthrough Clean-Tasting Pea Protein Isolate. Roquette Freres S.A.
- [20] Cosucra Groupe Warcoing S.A. (2025, December 18). PISANE P960 pea protein: Powering the Savoury Protein Shift. Cosucra Groupe Warcoing S.A.
- [21] Emsland-Starke GmbH. (2025, November 6). Ultra-Processed Food - A Differentiated Perspective. Emsland Group.
- [22] Archer Daniels Midland Company. (2026, February 24). Archer Daniels Midland Company Annual Report (Form 10-K for the Fiscal Year Ended December 31, 2025). U.S. Securities and Exchange Commission EDGAR.
- [23] Cargill, Incorporated. (2026, April 20). Cargill wins two 2026 Edison Awards for advancing the future of food. Cargill Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report draws on additional primary interviews, trade statistics, and proprietary Future Market Insights databases.
This Report Answers
- How large is the pea protein market in 2026 and what is forecast for 2036?
- Which allergen-free and clean-label pressures support demand for pea protein?
- Why do Pea Protein Isolates lead the product type category?
- Why does Spray-Dried Soluble Powder lead the physical form category globally?
- How do growth rates differ across Brazil, China, India, and Canada?
- Which leading companies supply wet-fractionated pea isolates and air-classified concentrates today?
- What limits adoption or supplier switching in the pea protein market?
- What should buyers evaluate before purchasing a pea protein ingredient?
Frequently Asked Questions
How big is the pea protein market in 2026, and what is forecast for 2036?
According to FMI, global pea protein demand is estimated to reach USD 1.8 billion in 2026 from USD 1.7 billion in 2025. Demand is forecast to hit USD 4.0 billion by 2036 as food and supplement brands replace soy and dairy allergens.
What is the CAGR for the pea protein market from 2026 to 2036?
Future Market Insights projects an 8.3% compound annual growth rate between 2026 and 2036, generating USD 2.2 billion in incremental demand over the ten-year period.
Which product type segment leads the pea protein market?
Pea Protein Isolates (80% to 85% wet-fractionated) are projected to capture 47.3% of product type demand in 2026 because high protein purity prevents starch thickening in beverages and meat analogues.
Which physical form segment leads the pea protein market?
Spray-Dried Soluble Powder is estimated to secure 75.1% of the physical form category in 2026 owing to ambient shelf stability and rapid dry-blend dosing.
Which country has a notable growth outlook during the assessment period?
Brazil is projected to lead national growth at a 9.6% CAGR through 2036, supported by soy-free meat-analogue exports and sports supplement blending.
Who are the key players in the market?
Roquette Freres S.A., PURIS Proteins, LLC, Cosucra Groupe Warcoing S.A., Ingredion Incorporated, Emsland-Starke GmbH, AGT Food and Ingredients Inc., Archer Daniels Midland Company, and Cargill, Incorporated are the leading suppliers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Pea Protein Isolates
- Pea Protein Concentrates
- Textured & Hydrolyzed Pea
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Physical Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Physical Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Physical Form, 2026 to 2036
- Spray-Dried Soluble Powder
- Extruded Crisps & Chunks
- Liquid Slurry Dispersions
- Others
- Y-o-Y Growth Trend Analysis By Physical Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical Form, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Industrial Meat Analogues
- Sports & Vegan Powders
- Dairy-Free Milk & Bakery
- Companion Animal Nutrition
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional Non-GMO Pea
- Certified Organic Yellow Pea
- Identity-Preserved Traceable Pea
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- B2B Food Processors
- Contract Supplement Packers
- Specialty Ingredient Distributors
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Physical Form
- By End-Use Application
- By Nature
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Roquette Freres S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- PURIS Proteins, LLC
- Cosucra Groupe Warcoing S.A.
- Ingredion Incorporated
- Emsland-Starke GmbH
- AGT Food and Ingredients Inc.
- Archer Daniels Midland Company
- Cargill, Incorporated
- Roquette Freres S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


